Property tax in New York City is one of those things everyone complains about and nobody actually understands until the bill lands on their doorstep
The NYC Department of Finance runs property tax assessments for all five boroughs, and the system they use has roots going back to the 1980s. I have spent several years working with property records, filing appeals, and dealing with the quirks that come up when a system this old meets modern real estate. Most people never look at their tax lot information until something goes wrong. By then, the window to fix things has usually closed. New York City divides property into four classes. Class 1 covers one-to-three family residential properties. Class 2 is everything else residential including condos, co-ops, and apartment buildings. Class 3 is publicly owned property. Class 4 is utility and railroad property. This classification matters because each class gets assessed differently and at different times. The assessor does not use market value to determine your property tax. They use assessed value, which is a fraction of what the property would sell for. For residential classes, that fraction is called the assessment ratio and it varies by class and by how many units a building has. A single-family home in Queens might have an assessment ratio around 6 percent while a large apartment building in Manhattan could be assessed at a completely different percentage. The gap between assessed value and market value is where most confusion starts.
How Assessments Actually Get Determined
The Department of Finance uses mass appraisal techniques. They pull data from sales transactions, building permits, and their own inspections to estimate values across the city. Every twelve years there is a comprehensive revaluation that resets all assessed values. The last major revaluation cycle happened in 2015 when the city moved from the old fixed assessment system to a new one tied more closely to market sales. Before that, assessments could stay frozen at 1930s or 1940s values for decades. I worked on a project involving a small commercial building in Brooklyn where the assessed value had not been updated since the early 2000s. The owner was paying property taxes based on a valuation that was roughly half of what similar buildings in the area had sold for. When we pulled recent comparable sales data and filed an appeal, the assessment was adjusted upward, but the process took eight months and required hiring a separate appraisal firm. The initial filing fee was $175 per property and each subsequent appeal cost another $500. That is important context because people often assume the first appeal is free or cheap. It is not.
The Review Cycle and Deadlines That Matter
Every year the DOF sends assessment notices to property owners around mid-July. The notice shows your assessed value, your tax class, and the calculated tax liability. The deadline to file a complaint against that assessment is typically August 25th for the upcoming fiscal year. If you miss that date, you are stuck with that assessment for the entire fiscal year starting July 1st. There are very few exceptions and they require showing that the department made a mathematical error or failed to follow proper procedure. I learned about this the hard way with a client who owned a mixed-use property in the Bronx. The assessment came in at $890,000 but comparable sales in the neighborhood had dropped significantly after a major redevelopment project changed the character of the street. The attorney handling the case missed the August deadline by three days because the mail got delayed. The tax increase for that year ended up being over four thousand dollars. After that, every client of mine gets calendar reminders set for August 1st and August 15th. The risk of missing a window is not theoretical.
Get the Full Details

Where to Find Your Assessment Data
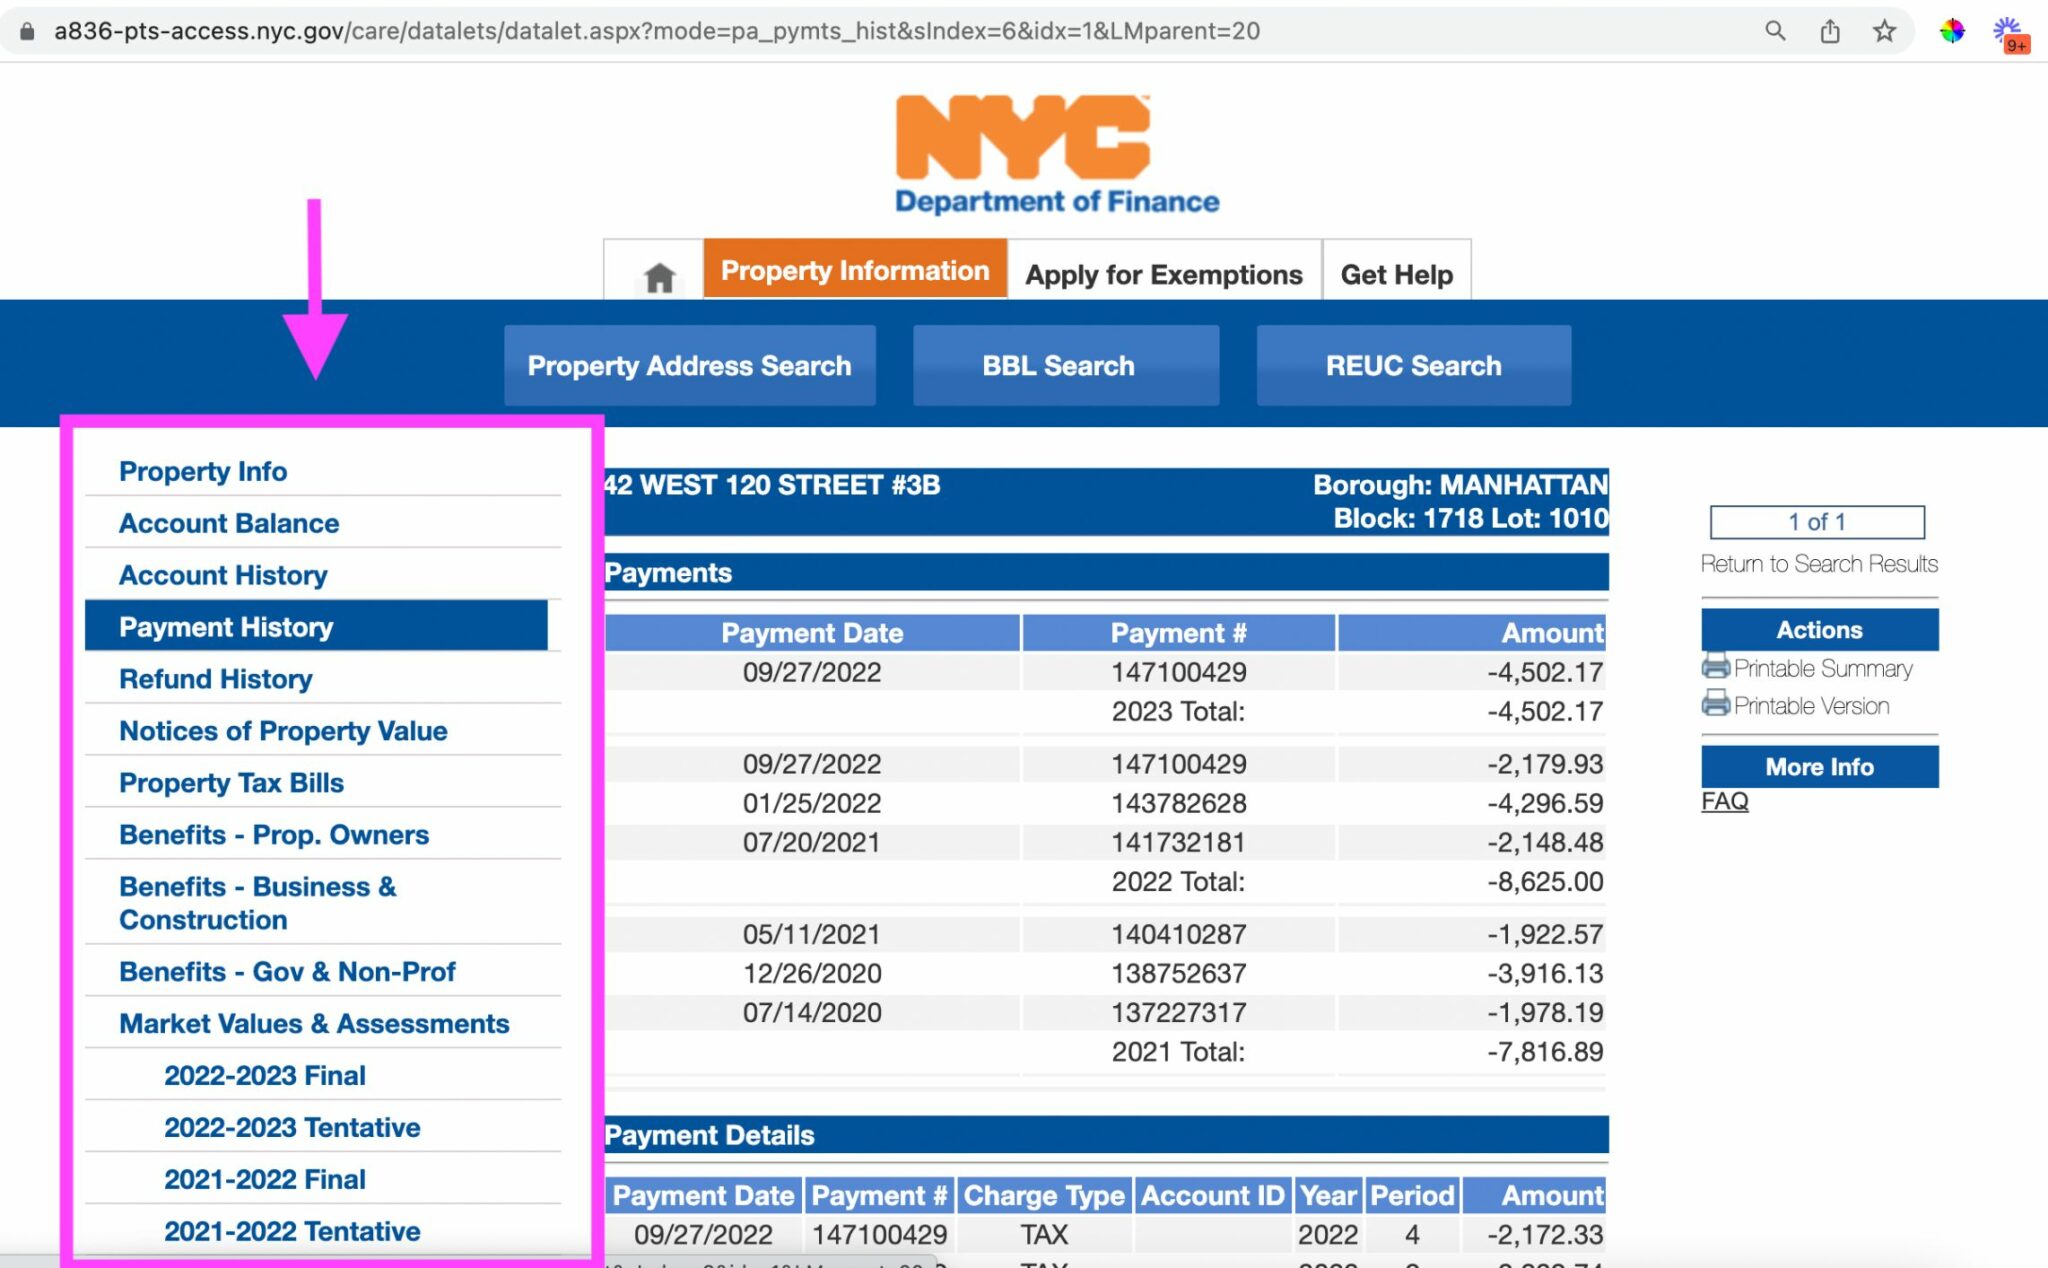
The NYC Department of Finance publishes all assessment information online through their automated tax information system. You can look up any property by address or by tax lot number. The interface is functional but dated. It will show you the current assessed value, the historical assessment history going back to the last revaluation, the property classification, and the ownership record. What it does not show you directly is the market value estimate or the comparable sales that informed the assessment. That information lives elsewhere and requires a different approach to access. The system also lets you download your property tax bill as a PDF. This is useful because the online display can be unreliable during peak filing seasons when the servers slow down or temporarily go offline. I always recommend printing or saving a copy of your current bill immediately after it arrives rather than relying on the online portal later. Digital records get updated and sometimes the version you see today will not be available next week when you need it for an appeal.
Filing an Assessment Appeal
If you believe your assessment is incorrect, the formal mechanism is called an RP-5217 form. You file this with the NYC Department of Finance and it triggers a review process. The form asks for your property information, your reasons for disputing the assessment, and supporting evidence such as recent sales of comparable properties or documentation of physical conditions that affect value like structural damage or environmental contamination. The review process happens in stages. First, a review examiner looks at your submission. If the examiner agrees the assessment needs adjustment, they can correct it without further action. If the examiner denies your complaint, you get the option to appeal to the Green Bench, which is the informal arbitration program run by the state Division of Budget and Management. The Green Bench hearing is less formal than a court proceeding and usually scheduled within 60 to 90 days of your request. An arbitrator reviews the evidence from both sides and issues a binding decision. There is a deeper issue here that most guides do not mention. The Department of Finance uses a methodology called the sales comparison approach for most residential properties, but they weight recent sales heavily and tend to discount older transactions even when those older sales are more comparable to your property. I have seen cases where a property on a quiet tree-lined street was compared to sales of units in high-rise developments three blocks away simply because those high-rise sales were more recent. The arbitrator on the Green Bench caught this in one case I was involved with and reduced the assessment by nearly 20 percent. The key was bringing in a licensed appraiser who could explain why the department's comparables were fundamentally mismatched.
Common Mistakes That Cost Property Owners Money
The biggest mistake is assuming the assessed value equals market value. They are not the same thing. The assessed value is a statutory calculation that produces a number used to determine your tax bill. The market value is what a willing buyer would pay a willing seller. For many residential properties, especially owner-occupied ones, the assessed value may already be below market value and filing an appeal could actually increase your taxes. Before you dispute an assessment, do the math on your actual tax bill under the current assessment and under a hypothetical higher or lower one. The tax rate varies by borough and by school district and sometimes a lower assessment does not produce the savings people expect. Another frequent error is relying on online valuation tools from real estate websites. Those estimates are algorithmic approximations and they are not accepted as evidence in an assessment appeal. The DOF requires documented comparable sales with recorded transaction data, not estimated values from a search engine. I have seen several appeals fail because the property owner brought printouts from Zillow or Redfin instead of county recording documents and actual closing statements.

When Professional Help Makes Sense
For simple residential properties where the assessment appears reasonable relative to neighborhood sales, self-filing an appeal is straightforward and the forms are available on the DOF website. For commercial properties, mixed-use buildings, or residential properties in neighborhoods with rapid price changes, the complexity increases significantly. Commercial assessments involve income capitalization approaches and vacancy rate assumptions that are difficult to challenge without understanding how the department applies them. A property with an existing lease, a vacant upper floor, or a zoning change pending will require documentation that most property owners do not know how to assemble properly. I handle a handful of appeals each year for commercial clients in Manhattan and Brooklyn. The ones that succeed usually share one characteristic: the owner has assembled a complete evidence package before filing the initial complaint rather than trying to supplement it later. The DOF reviewer gets dozens of complaints every week and incomplete filings get quick dismissals. Complete filings with recorded sales, photos of property conditions, and a written narrative explaining the discrepancy have a substantially higher success rate at the review examiner level.
Tax Abatements and Exemptions Worth Checking
Even when your assessment is accurate, you may be eligible for programs that reduce your tax liability. The basic STAR exemption applies to primary residences and reduces the taxable portion of your assessment. There is a full STAR exemption for seniors age 65 and older and a partial STAR exemption for middle-income homeowners. These are automatic for most qualifying properties but not all. I encountered a situation where a homeowner in Staten Island had not filed the necessary paperwork to enroll in partial STAR and was overpaying by over two thousand dollars annually. The application process is through the DOF and it takes about six weeks to process. Beyond STAR, there are targeted abatement programs for certain neighborhoods, historic properties, and properties that meet affordability requirements. The 421-a exemption program for new construction has undergone multiple legislative changes and currently operates under different rules depending on when the building was completed. Navigating these programs without professional guidance is possible but the penalties for getting it wrong are real and usually involve retroactive tax bills with interest. The system has structural limitations. Assessments are based on historical data and lag behind rapid market changes. The review process is adversarial by design and the burden of proof rests on the property owner. Success rates for appeals vary significantly by borough and by property type, and the DOF corrects its own errors about as often as it dismisses valid complaints. None of this makes the system broken, but it does mean that understanding how it works before you need it is the only realistic strategy.