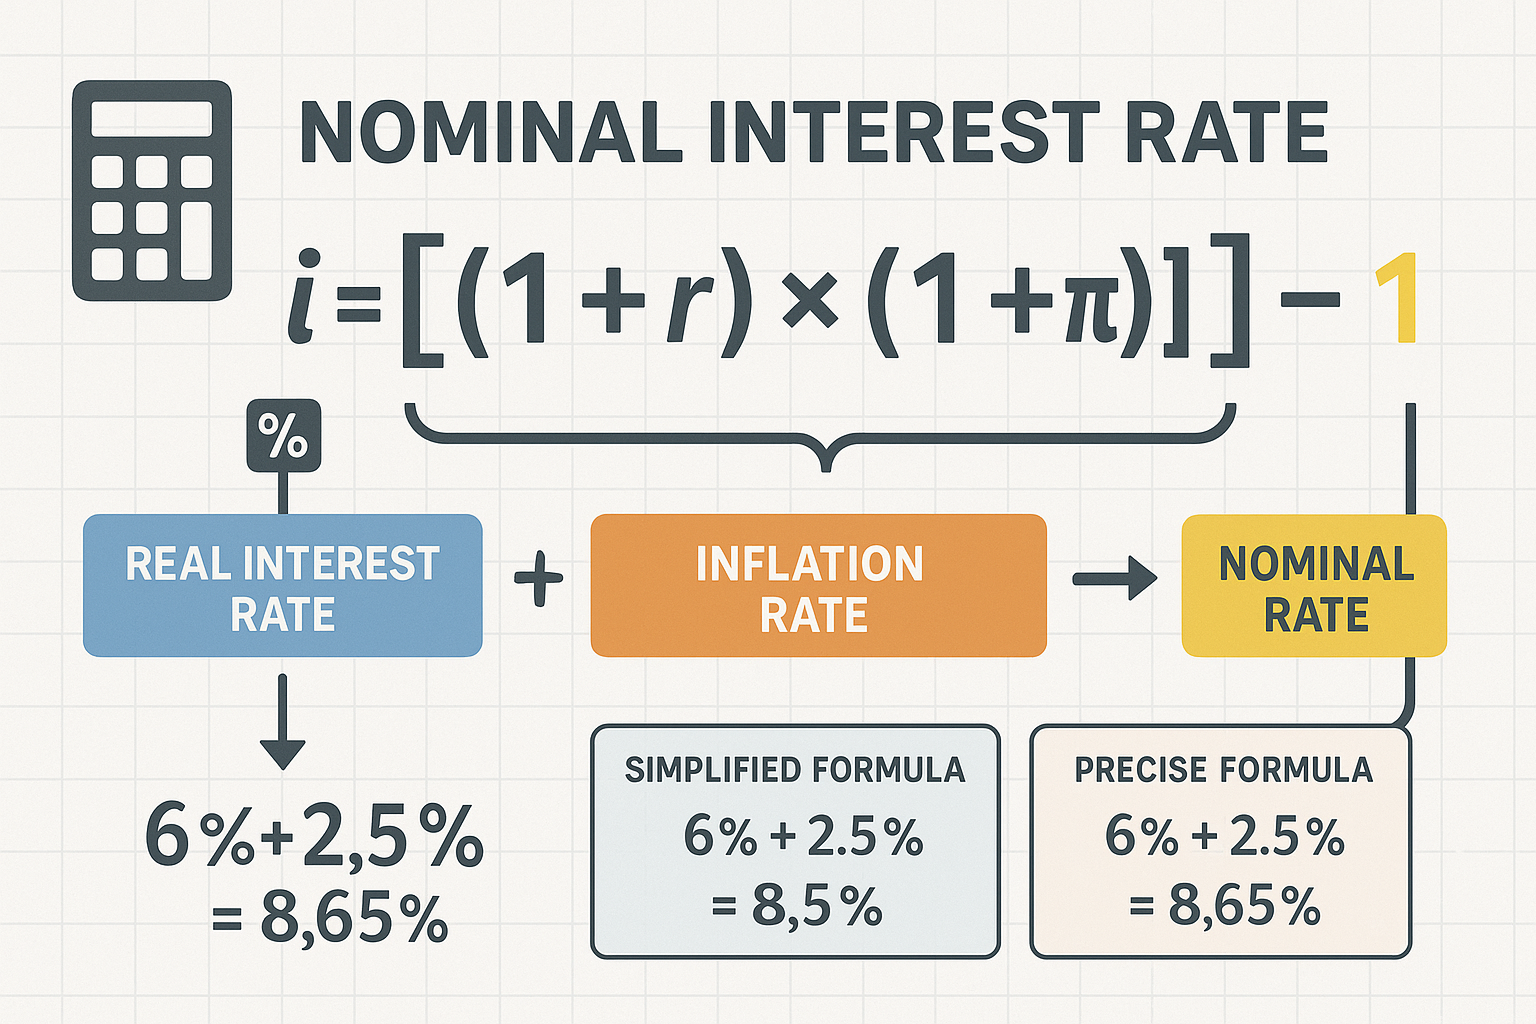
Understanding What The Nominal Rate Actually Represents
The nominal interest rate is the stated percentage on a loan or investment before you account for compounding. That's it. Most people stop there and make expensive mistakes because the nominal rate is not the real rate you pay or earn. I've watched borrowers take out personal loans at 6% and think they're getting a deal, only to realize the effective rate was closer to 8.2% once monthly compounding kicked in. The gap between nominal and effective is where the confusion lives. The formula connects nominal and effective rates through compounding frequency. You take the nominal rate, divide it by the number of compounding periods per year, add one, raise that to the power of the compounding periods, then subtract one again. The equation looks like this: Effective Annual Rate (EAR) = (1 + r/n)^n - 1
Where r is the nominal rate expressed as a decimal and n is the number of compounding periods annually. If you have a 6% nominal rate compounded monthly, you plug in 0.06 for r and 12 for n. The calculation gives you approximately 6.17%. The difference seems small on a $1,000 loan, but on a mortgage it adds up to thousands over the life of the loan. For the reverse calculation, when you need to find the nominal rate from a known effective rate, you rearrange the formula. The nominal rate equals n times ((1 + EAR)^(1/n) - 1). This comes up more often than you'd think, especially when comparing investment products that advertise different compounding structures.
Why The Nominal Rate Misleads People
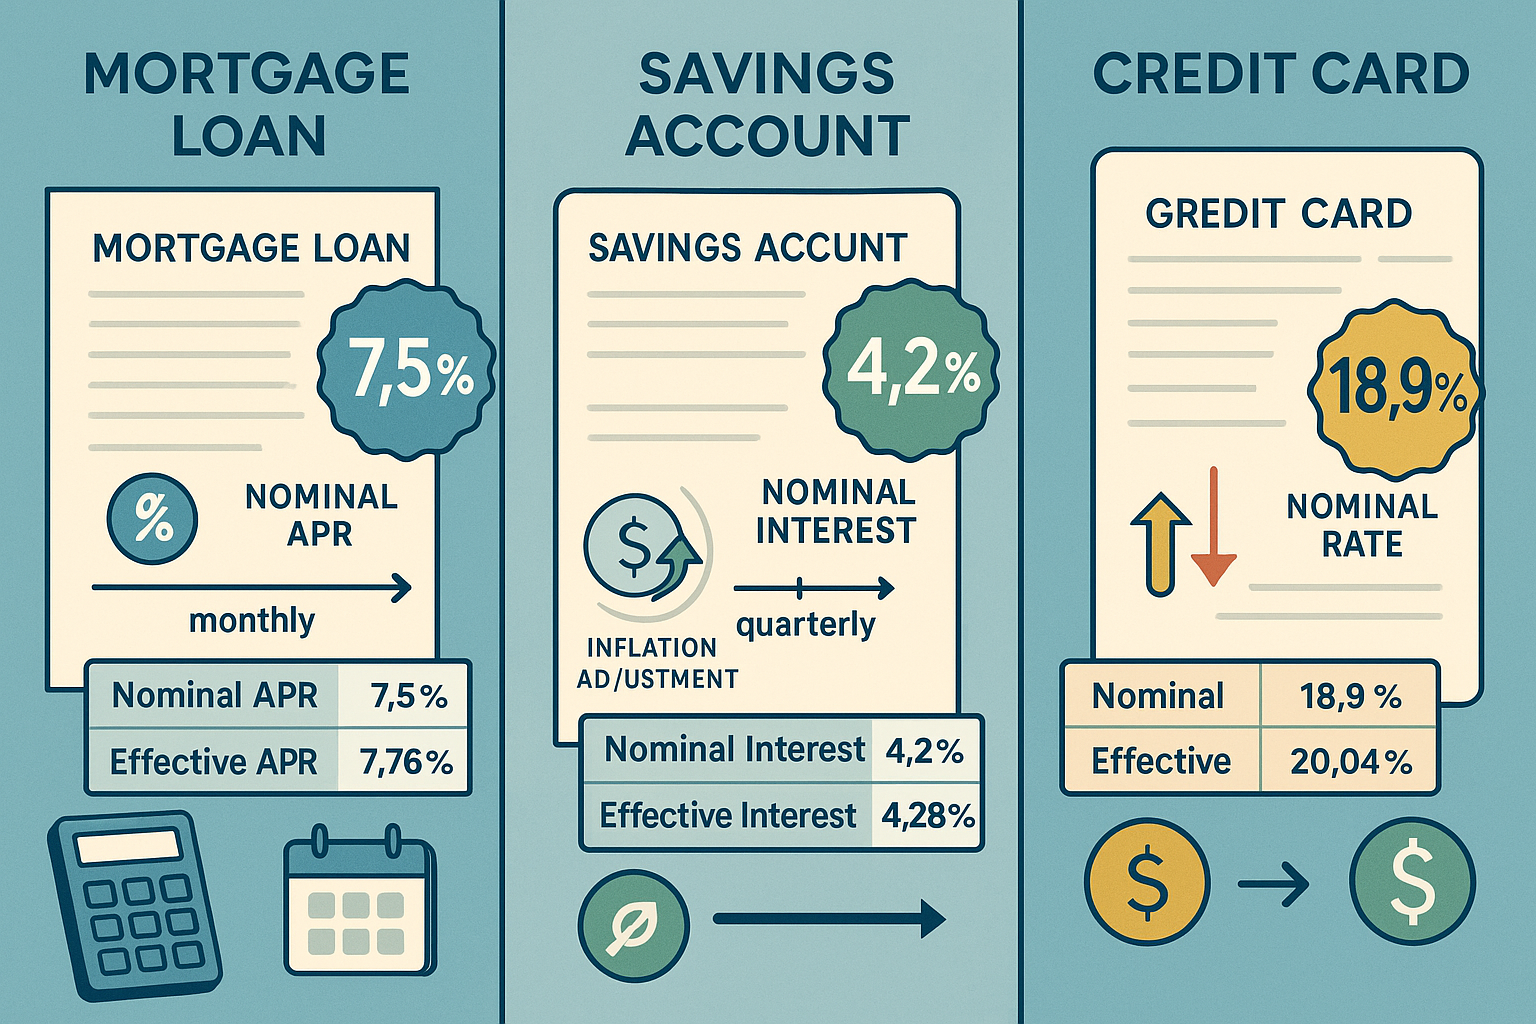
Lenders know that nominal rates look lower. A credit card advertising 19.9% nominal rate compounded daily actually costs you about 22% effective annual rate. That's a significant difference, and most consumers never do the conversion. The regulatory requirement to disclose APR helps, but APR assumes you'll make minimum payments and carry the balance indefinitely, which doesn't match how most people actually use credit. I worked through a commercial lending file last year where a borrower was comparing two equipment financing offers. One advertised 7.5% nominal compounded quarterly. The other showed 7.2% nominal compounded monthly. The second looked cheaper on the surface, but the quarterly compounding on the first offer actually made its effective rate lower. That's the kind of thing that traps people who only glance at the headline number.
Get the Full Details
Compounding Frequency Matters More Than Most Realize
Daily compounding pushes the effective rate further above the nominal rate than monthly or quarterly compounding. Here's the breakdown for a 6% nominal rate across different frequencies: Annual compounding: 6.00% effective Semi-annual compounding: 6.09% effective
Quarterly compounding: 6.09% effective Monthly compounding: 6.17% effective Daily compounding: 6.18% effective
The gap between annual and daily compounding at this rate is less than a quarter point, but at higher rates or longer time horizons the difference compounds literally. At 12% nominal with daily compounding, the effective rate jumps to about 12.75%. That extra 0.75% on a $200,000 mortgage over 30 years is roughly $43,000 in additional interest.
The Continuous Compounding Edge Case
When compounding happens continuously, you use the exponential function instead of the standard formula. The effective rate becomes e raised to the power of r, minus one. For a 6% continuous compounding rate, the effective annual yield is about 6.18%. It's marginally higher than daily compounding, but the formula is cleaner for certain theoretical applications and derivative pricing models. I ran into a situation where an investment product used continuous compounding in its disclosures but presented the nominal rate in a way that made the effective yield nearly impossible to back out without knowing the exact methodology. I ended up requesting the amortization schedule directly and working backward from the actual cash flows rather than trusting the stated nominal figure. Took about twenty minutes of spreadsheet work that saved the client from a significant overpayment.
Pitfalls That Cost Money
The biggest mistake people make is comparing nominal rates across different compounding frequencies as if they were equivalent. Another common error is ignoring fees when calculating true cost. A loan with a slightly higher nominal rate but no origination fees can be cheaper than a lower nominal rate loan with points and closing costs baked in. You need to calculate the effective rate on the total amount funded, not just the face value. There's also the trap of treating the nominal rate as fixed when it's actually variable. Some adjustable-rate products advertise a teaser nominal rate that resets after a set period. The nominal rate at origination is essentially irrelevant to what you'll actually pay over the full term. Always look at the fully indexed rate, not the initial teaser. Inverse problems show up too. Sometimes you're given the effective rate and need to find the nominal rate for a specific compounding frequency. This happens when you're evaluating bond yields or municipal instruments where the quoted yield is already effective. Converting that back to a nominal rate with a different compounding frequency requires the rearranged formula I mentioned earlier, and getting the decimal places wrong by even a few basis points can shift your comparison results noticeably.
Practical Calculation Walkthrough
Let's say you're looking at a student loan with a 5.5% nominal rate compounded daily. You want to know the true annual cost. Divide 0.055 by 365, which gives you 0.00015068. Add one to get 1.00015068. Raise that to the 365th power, giving approximately 1.0565. Subtract one, and the effective annual rate is 5.65%. The nominal rate was 5.5%, but you're actually paying 5.65% because of daily compounding. Now flip it. An investment advertises a 7% effective annual return with monthly compounding. What nominal rate does that imply? Take the effective rate of 0.07, add one to get 1.07. Raise it to the one-twelfth power, which is approximately 1.00565. Subtract one, giving 0.00565. Multiply by 12 compounding periods, and the nominal rate is about 6.78%. The investment pays you 7% effective, but the nominal rate you'd see quoted is lower because of the monthly compounding effect.
What The Formula Can't Tell You
The nominal to effective conversion is mathematically clean, but it doesn't account for everything. It ignores prepayment penalties, balloon payments, fee structures, and tax implications. A high-yield savings account might show a competitive nominal rate, but if it has withdrawal limits that force you into a lower tier, the effective rate drops. A loan might have a decent nominal rate but include mandatory mortgage insurance that pushes your total cost well above the calculated effective rate. The formula also assumes the rate stays constant. In reality, variable rates move with the market, and the nominal rate you lock in today might not reflect what you're actually paying next year. The conversion tells you the cost at a single point in time, not the trajectory. If you're evaluating a five-year loan with an adjustable rate, you need to model the expected rate path, not just convert the starting nominal figure. For quick comparisons between similar products with the same compounding frequency, the nominal rate works fine as a shorthand. But when compounding frequencies differ, or when fees and terms vary significantly, doing the full effective rate calculation takes about three minutes and saves you from making a decision based on incomplete information.


