The New 100 Bill A Comprehensive Look At Security History And Public Perception
Samantha
2025-07-21
Counterfeit Deterrence On The Current Series $100 Note
The Federal Reserve introduced the redesigned $100 bill in October 2013, pushing the most advanced security features into circulation at that point. Before that redesign, the series 1996 note had been the standard for seventeen years and it showed its age. The new note was meant to close gaps that counterfeiters had been exploiting for years, particularly in the three-color portrait and the motion inkwell features that followed. It also aimed to make authentication faster for cash handlers who process thousands of notes per day, from retailers to armored car drivers.
What changed on the note itself
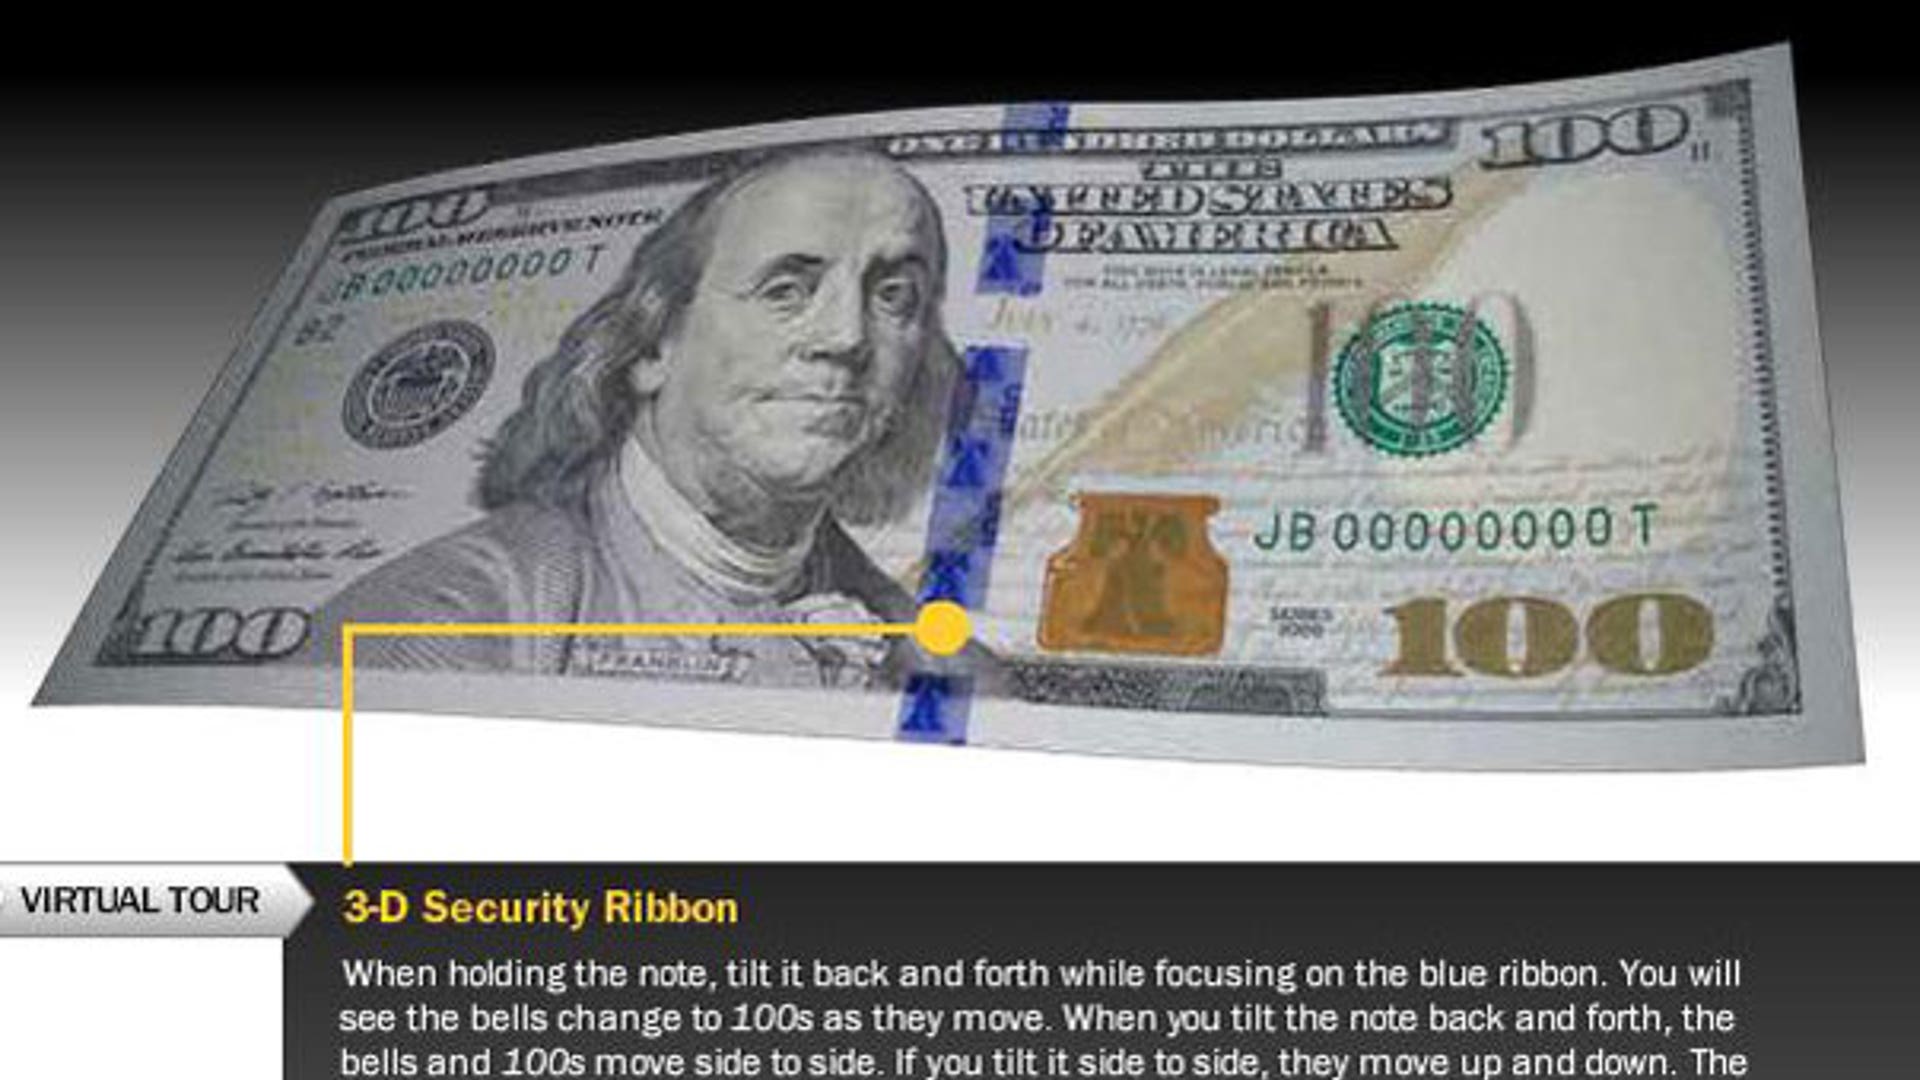
The most obvious difference is the color barrier ribbon embedded in the paper rather than printed on the surface. If you hold the note up to light, the ribbon runs vertically to the right of Benjamin Franklin's portrait and shows alternating 100s and bells. Under normal light, it looks like a thin blue stripe. Tilt the note and the icons shift. That was a deliberate move away from the security thread used on lower denominations, which sits inside the paper and requires backlighting to see clearly. The ribbon is meant to be visible without any extra equipment, which matters when someone is handing you cash at a checkout counter and you need to verify it in under two seconds.
Next to the ribbon is the color-shifting bell in the inkwell to the right of Franklin's portrait. It shifts from copper to green when you tilt the note. The inkwell used to contain a plain bell on the series 1996 note and that feature survived into the early redesigns before being replaced. The movement of the color shift is fairly quick, but it does depend on the lighting angle and the surface texture of the note. A heavily worn bill might not show the shift as sharply, which has caused confusion at points of sale.
The portrait itself uses three-color offset printing. Franklin's image combines black, blue, and crimson inks that overlap in precise registers. Counterfeiters using standard digital or toner-based printers struggle to reproduce that kind of layered color separation. The registration tolerance on genuine notes is usually within a fraction of a millimeter, and misregistration is one of the first red flags experienced handlers look for.
Below the portrait is the size-reduced portrait watermark. It appears when you hold the note up to a light source and shows a faint Franklin face to the right of the main portrait. The watermark is created by changing the density of the cotton-linen paper during the manufacturing process, not by printing an image on top. That makes it difficult to replicate with standard photocopying or scanning. The watermark on the current design is smaller than the one introduced on the $50 note in 2004, which some observers found harder to spot quickly.
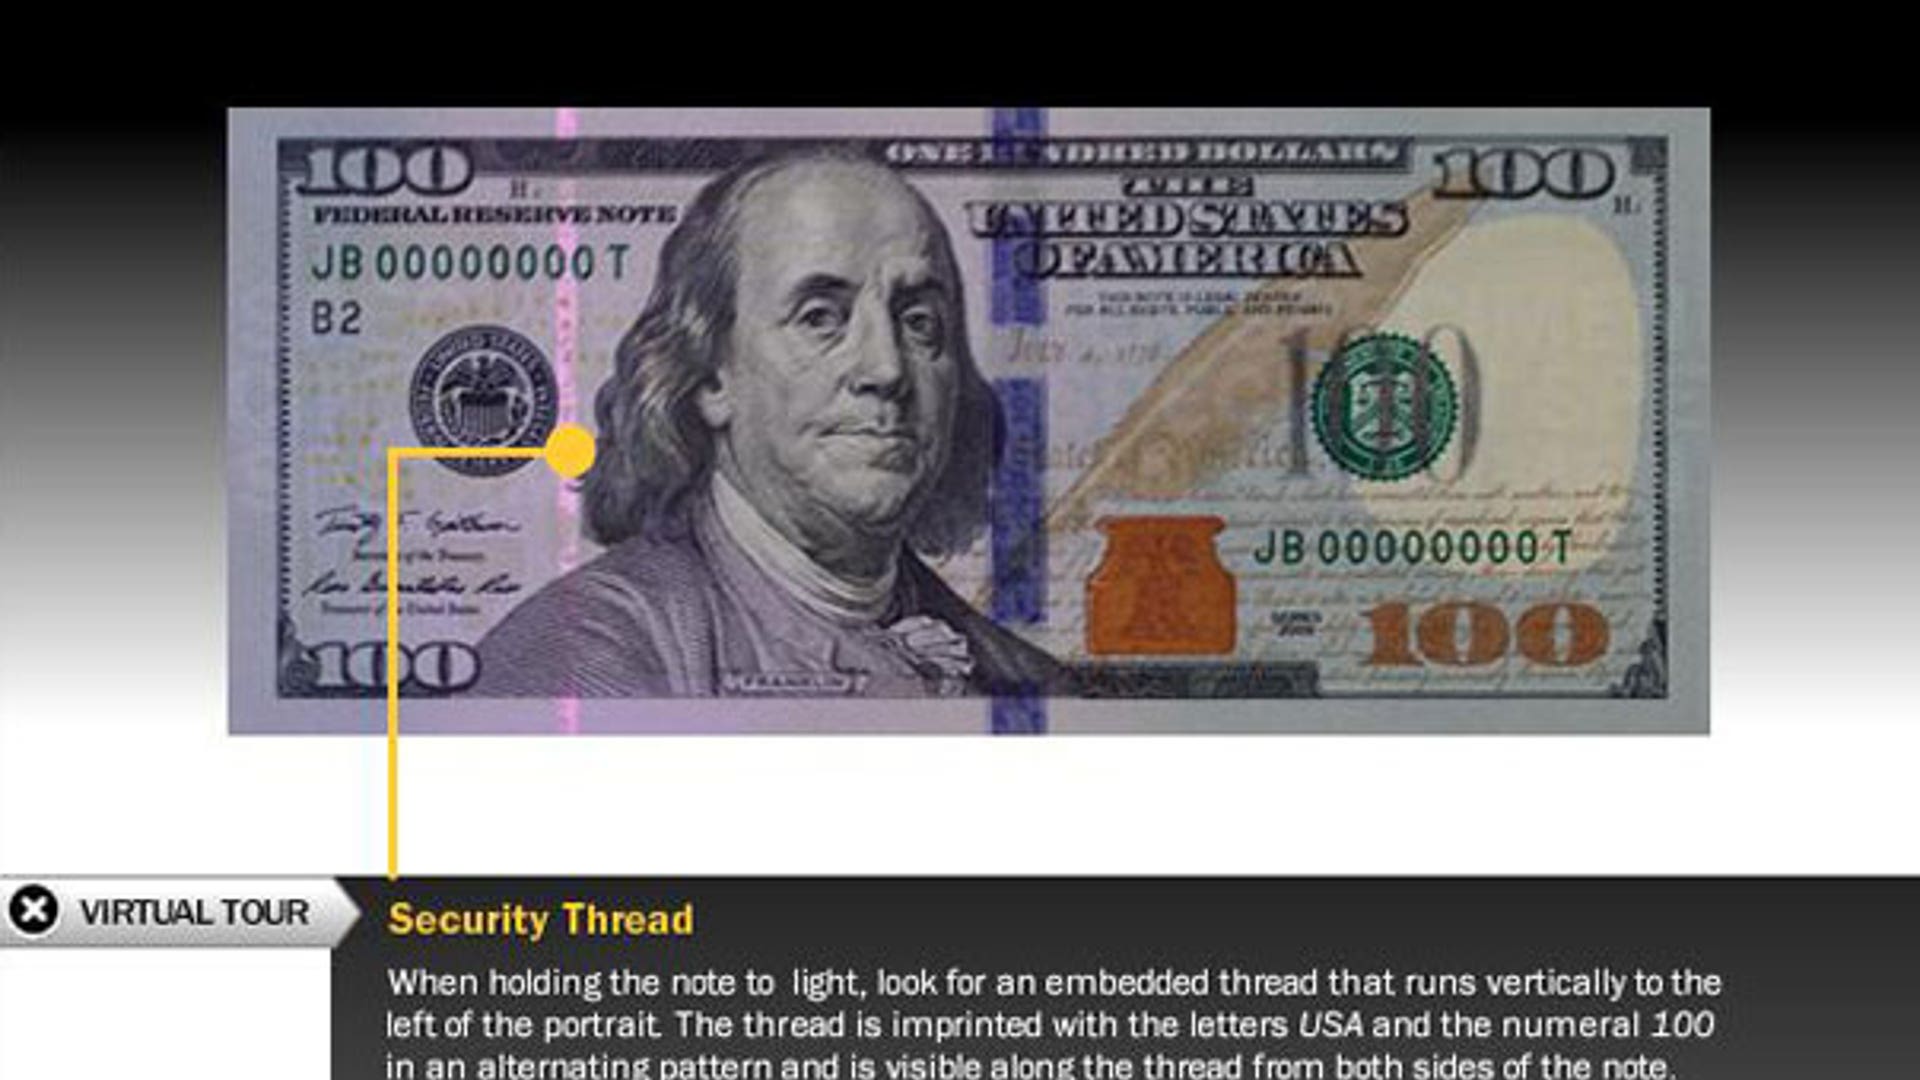
The security thread runs vertically to the left of the portrait and glows pink under ultraviolet light. It is embedded in the paper substrate, not printed, and carries the text "USA 100" in microprinting that is readable with low magnification. The thread was previously used on earlier series notes in different colors, but the UV response here is consistent across the current production run.
Microprinting appears in several locations: along Franklin's collar, on the pedestal of Independence Hall on the reverse, and within the borders. The text reads "THE UNITED STATES OF AMERICA" and "USA 100". It looks like a solid line to the naked eye but resolves into readable text under magnification. Many counterfeit notes smear this text into an unintelligible blob because standard printing presses cannot maintain the required resolution.
raised printing is another tactile feature. Run your fingertip along Franklin's shoulder or the border of the note and you should feel slight roughness. That comes from intaglio printing, which uses engraved copper plates to deposit ink in raised layers. Flat notes that feel completely smooth are almost always counterfeit. This feature has been on US currency since the 1860s and remains one of the most reliable quick-check methods because it is cheap to reproduce on genuine notes and expensive to fake accurately.
The New 100 Bill A Comprehensive Look At Security History And Public Perception
The history of US currency security goes back well before 2013. The first anti-counterfeiting measures on paper money date to the Civil War era, when the Treasury Department added complex woodcut patterns and color shifts to make reproduction harder. By the 1990s, the Secret Service had been tracking counterfeiting with increasing sophistication, and the introduction of the portrait watermark and security thread on the series 1996 $100 note was a direct response to high-quality Chinese counterfeits that were flooding the market. Those fake notes, sometimes called superdollars, were so good that even trained handlers struggled to distinguish them without magnification or UV light.
The Secret Service estimated that counterfeiting of US currency peaked in the mid-1990s, with roughly 70,000 fake notes in circulation at the time. Most of those were high-denomination bills because the profit margin is higher when you fake a $100 note than a $1 note. The total value of counterfeit detected annually has fluctuated since then, but the trend has generally declined as security features improved and enforcement tightened. The current design was partly intended to push the counterfeit rate even lower and to give cash handlers tools that work without specialized equipment.
Public perception of the redesigned $100 bill has been mixed. Some people appreciate the color and the more intuitive features, while others find the changes confusing, especially older customers who grew up with the green-and-black design. Retail workers have reported complaints from customers who assume a genuine note is fake because they do not recognize the ribbon or the color shift. That is a real problem in environments where cash handling speed matters and disputes over can slow down transactions.
I ran into a specific issue last year while working with a small retailer who refused to accept the redesigned $100s. They had a policy of rejecting any note that did not match the old design because they had been scammed before. The workaround was straightforward but annoying: I set up a simple UV flashlight at the register and trained the staff to check the security thread glow and the tactile features. It took about twenty minutes to explain the new features and another hour to build a checklist they could follow consistently. After that, the dispute rate dropped significantly, though a few older employees still preferred the old notes out of habit.
Authentication in practice
The fastest way to verify a $100 bill is to check three things in sequence: the ribbon, the color shift, and the raised printing. That process takes about five seconds and catches the vast majority of counterfeits in circulation. If the ribbon is missing or looks printed on rather than embedded, the note is likely fake. If the inkwell does not shift color, same thing. If the portrait feels flat, another red flag. Advanced handlers add the watermark and UV thread checks, which take another ten to fifteen seconds but provide stronger confirmation.
Counterfeit detection machines used in retail and banking follow a similar logic but with added layers. Most modern validators use magnetic sensors, UV fluorescence, infrared absorption, and sometimes image recognition to verify multiple features simultaneously. A basic bill validator costs between $200 and $800 depending on speed and features, and it can process a note in under a second. Higher-end models used in banks cost several thousand dollars but can handle thousands of notes per hour with very low false rejection rates.
The Secret Service recommends that the public rely on the three basic checks and report suspicious notes rather than trying to dig deeper. Their guidance has not changed much since the redesign: look at the ribbon, tilt for color shift, feel for texture. Anything that fails those checks should be turned over to law enforcement, not returned to the person who handed it to you.
Limitations and edge cases
No security feature is foolproof, and the current $100 note has known weaknesses. The most significant is wear. Heavily circulated notes lose some of their tactile texture, the color shift becomes less vivid, and the ribbon can fray or lift at the edges. I have seen notes from active retail use that failed the ribbon check simply because the stripe had started to separate from the paper surface. In those cases, the UV thread and watermark checks become more important, but they require good lighting conditions that are not always available at point of sale.
Another limitation is that counterfeiters are continuously improving their techniques. High-resolution scanning and specialized inks have narrowed the gap on some features, particularly the color shift and microprinting. The Secret Service has noted that sophisticated counterfeits occasionally pass basic checks and require advanced validation equipment to detect. This is not a common problem, but it is real and it means that relying solely on visual inspection is never a complete solution.
Some experts argue that the next step should be a digital serial number embedded in the note, similar to what some European currencies have experimented with. That would allow validators to cross-reference notes against a central database and track individual bills through the supply chain. The technical challenges are significant, and the cost would be substantial, but the potential fraud reduction could justify it for high-denomination notes. The Federal Reserve has not announced any plans to pursue that direction, so the current design remains the standard for the foreseeable future.
What to do if you suspect a fake
Do not confront the person who handed you the note. Keep the bill if you can do so safely, note the person's description and any details about the transaction, and contact local law enforcement. The Secret Service can be reached through local field offices, and they will typically take the note for forensic analysis. Do not try to destroy or discard the suspected counterfeit yourself, as it may be needed as evidence.
For businesses that handle cash regularly, investing in a quality bill validator and training staff on the basic authentication steps is the most effective long-term strategy. A single rejected counterfeit can save hundreds or thousands of dollars, and the validation equipment pays for itself quickly in high-volume environments. The cost-benefit calculation is straightforward: a $400 validator that processes 500 notes per day and catches even one fake per month will save more than its purchase price within the first year.
The broader context is that US currency remains one of the most secure paper currencies in the world, and the current $100 design reflects decades of iterative improvement. The security features are not perfect, and they will continue to evolve, but the combination of embedded ribbons, color-shifting ink, microprinting, watermarks, and tactile printing creates a layered defense that is difficult and expensive to replicate at scale. That is the point, and it has worked well enough that counterfeiting of US currency remains a small fraction of the total money supply.
Gallery The New 100 Bill A Comprehensive Look At Security History And Public Perception
New $100 bill security features sparkle
New 100 Dollar Bill: A Comprehensive Guide | MUNBYN Blog - MUNBYN® POS
New $100 Bill Has All the Bells and Whistles
Meet the new $100 bill | Fox News
Meet the new $100 bill | Fox News