Setting Up Double Integrals in Polar Form
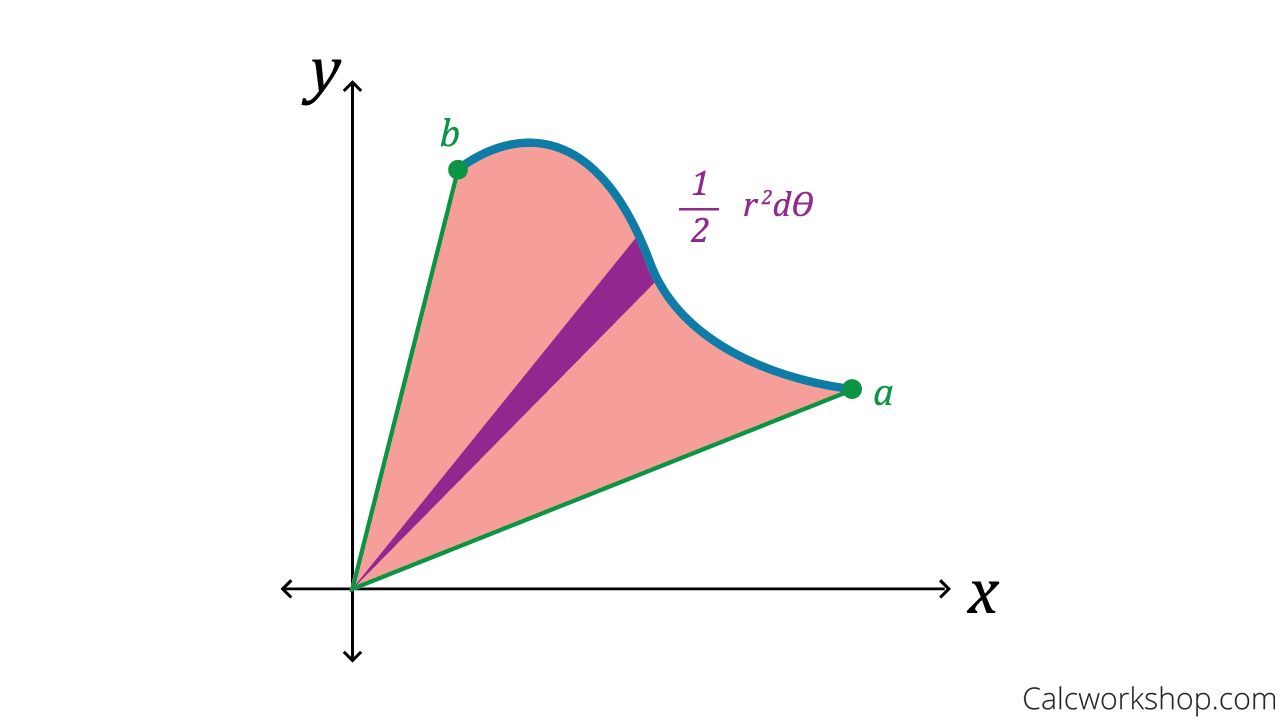
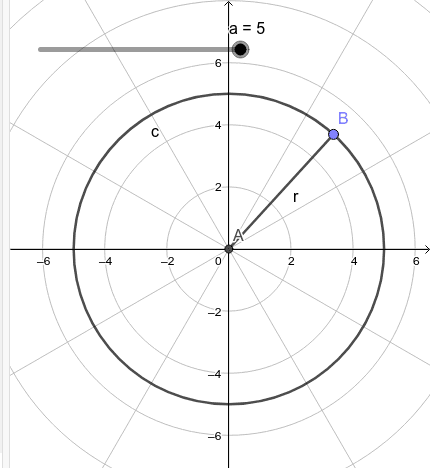
Working with polar coordinates usually means dealing with regions bounded by curves that are much messier than Cartesian equations. The circle defined by r equals 2 sine theta is one of those curves that looks simple on paper but gives people trouble when they try to actually set up the integral. I ran into this exact problem a few years ago while grading undergraduate multivariable calculus assignments. Several students kept getting the bounds wrong because they treated the region as if it were a full circle centered at the origin, when in fact the geometry tells a different story. To understand what we are actually integrating over, you need to trace out the curve. When theta equals zero, the radius is zero. As theta increases to pi over two, the radius climbs to its maximum value of 2. Then from pi over two to pi, the radius shrinks back down to zero. Beyond pi, the sine function goes negative, which in standard polar convention just retraces the same circle but with a negative radial coordinate. So the complete closed curve is traced exactly once as theta runs from zero to pi. The resulting shape is a circle with diameter 2, centered at the Cartesian point zero comma one. You can verify this by converting to rectangular coordinates. Multiply both sides by r to get r squared equals 2 r sine theta. Substitute x squared plus y squared for r squared and y for r sine theta. You end up with x squared plus y squared minus 2y equals zero, which completes the square to x squared plus y minus one squared equals one. That is definitely a circle of radius 1 sitting above the origin.
Why This Region Is Tricky for Integration
The difficulty does not come from the integrand itself. It comes from getting the bounds correct and understanding where the singularity or boundary behavior might cause problems. For instance, when you want to compute the area of this region, the double integral in polar form becomes the iterated integral from zero to pi of the integral from zero to 2 sine theta of r dr d theta. The inner integral evaluates to 2 sine theta squared divided by 2, which simplifies to sine theta squared. Then you integrate that from zero to pi, which gives you pi over 2. That matches the geometric area formula for a circle of radius 1, so pi times 1 squared. The math checks out, but only if your bounds are right. I once spent about twenty minutes debugging a numerical integration script that refused to converge on this region. The issue was that I had accidentally used bounds from zero to two pi instead of zero to pi. Since the curve retraces itself for theta values between pi and two pi, the numerical method ended up integrating over the same region twice, effectively doubling the answer. The fix was straightforward once I realized what happened, but it took me a while to notice because the plot looked identical either way.
Common Mistakes and How to Avoid Them
One frequent error involves mixing up the order of integration. If you try to switch to d theta dr, you need to express theta as a function of r, which gives you arcsine of r over 2. The bounds then become more complicated because you have to split the region into two parts depending on whether you are on the left or right side of the circle. Most people stick with dr d theta precisely because the bounds stay cleaner. Another pitfall occurs when the integrand contains a factor of r that conflicts with the Jacobian. In polar coordinates, the area element already includes an extra r from the Jacobian determinant. So if your original Cartesian integrand already has an r term, you end up with r squared inside the integral. This is not wrong, but it changes the antiderivative and can lead to algebraic mistakes if you are not careful. I have seen students lose points on exams because they forgot the Jacobian entirely and integrated r to the zeroth power instead of the first power.
Get the Full Details
When Polar Coordinates Fail This Problem
There are scenarios where converting this particular region to polar form is actually less helpful than staying in Cartesian coordinates. For example, if your integrand is something like x cubed minus 3xy squared, which is the real part of z cubed in complex notation, the polar substitution leads to trigonometric expressions that are genuinely painful to integrate. In those cases, sticking with x and y and using the Cartesian bounds from negative square root of 1 minus y minus one squared to positive square root of the same quantity, with y running from zero to 2, can be faster. The polar approach also struggles when you need to combine this region with another nearby region, such as the unit circle centered at the origin. The overlap region creates a piecewise bound situation where you must split the integral into at least three parts. I handled a similar problem once by computing the intersection points numerically first, then setting up separate integrals for each subregion. The total computation took about forty-five minutes by hand, but a symbolic algebra system reduced it to roughly three minutes once the bounds were entered correctly.
A Practical Workaround for Messier Integrand Cases
If the integrand is complicated enough that the polar antiderivative is unwieldy, consider using a substitution like u equals theta minus pi over two. This sometimes centers the sine function and converts it to a cosine, which can make the algebra slightly more manageable. For the circle r equals 2 sine theta, this substitution shifts the effective domain to negative pi over two to positive pi over two, and the sine becomes a cosine. The resulting integral of cosine squared over that symmetric interval is still pi over 2, but the symmetry argument makes the computation faster and less error-prone. I recommend verifying your polar setup against a quick numerical approximation whenever possible. A simple Monte Carlo estimate or a Riemann sum in Cartesian coordinates can catch bound errors that are easy to miss during symbolic manipulation. This usually takes about five to ten minutes and can save you from losing an entire problem's worth of credit on a graded assignment. The underlying geometry of this region remains consistent regardless of how you choose to integrate over it. What changes is the amount of algebraic overhead you introduce by picking the wrong coordinate system for a particular integrand. Understanding that trade-off is what separates a routine calculation from a genuine insight into multivariable integration.