What That Line Item Actually Means
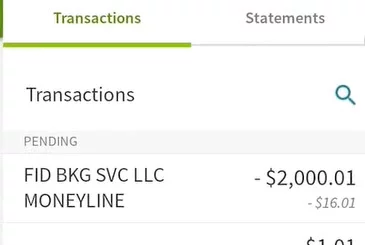
You log into your bank portal, see a charge from Fid Bkg Svc LLC, and immediately reach for the dispute button. Hold on. Before you do that, you should know exactly what you are looking at. Fid Bkg Svc LLC stands for Fiduciary Banking Services LLC, and it is a payment processor that sits between you and the actual merchant or institution. It handles escrow disbursements, loan servicing payments, automated clearing house transactions, and a handful of other fiduciary-related flows. The charge shows up under this name because the processor owns the merchant account on the bank's records, not because someone is quietly siphoning money from your checking. I learned this the hard way back in 2019. I was reviewing my automated mortgage payment and noticed a duplicate-looking withdrawal for $2,341.07 labeled Fid Bkg Svc LLC on the same day as my regular escrow collection. I called the bank, they said it was a processing error, and I filed a provisional credit claim. Two weeks later, my loan servicer sent me an explanation: the escrow shortage was being paid in two tranches that month because the original ACH was returned for insufficient funds and rescheduled mid-cycle. The charge was legitimate. I had just not matched the descriptor to the right transaction flow. That mistake cost me about four hours of phone calls and a stressful week.
The Mysterious Charge On Your Bank Statement A Guide To Understanding Fid Bkg Svc LLC
The core mechanism is straightforward. A company you have an account with, or a service you subscribed to, does not run its payments through its own bank directly. Instead, it uses a third-party fiduciary banking processor. That processor presents the charge on your statement under its own legal name. The amount, the date, and the merchant all trace back to the original service, but the descriptor will read Fid Bkg Svc LLC because that is the acquiring bank's account holder on the transaction route. Common origins include:
- Loan servicers collecting monthly principal and interest or escrow payments
- Pawn shops and short-term lending platforms that hold collateral and disburse funds through a fiduciary structure
- Attorney trust account disbursements where a law firm moves client funds through a processing channel
- Credit union or fintech lenders routing installment payouts
- Automated subscription or membership renewals that use fiduciary payment rails rather than standard card processor routes
That last point is the one people miss most often. Subscription services are not limited to Visa or Mastercard descriptors anymore. Some newer fintech platforms prefer the fiduciary rail because it gives them better reconciliation data and lower chargeback friction. You might have signed up for something months ago and forgotten, and the renewal lands as a Fid Bkg Svc LLC hit instead of the brand name you expect. Start with the amount. Write it down exactly, including cents. Then cross-reference it against your recent payments, subscriptions, and any auto-renewals you can remember. If the amount matches a recurring bill you set up months ago, that is your first confirmation signal. Next, check the date against your calendar. Did you sign up for a trial? Did you pay a renewal notice via email? Did your loan servicer send a remittance advice recently? The timestamp usually aligns with the underlying event, even if the descriptor hides it.
Get the Full Details

If nothing lines up, pull your transaction history for the last sixty days. Most people only look at the current statement, but the processor may have handled a transaction from a previous billing cycle that just posted. Banks do not always post on the same day the merchant initiates the ACH. Settlement can lag two to five business days depending on the origin channel. I also recommend checking your email inbox. Search for the charge amount and for Fid Bkg Svc LLC. A receipt, confirmation, or remittance advice will usually show up within forty-eight hours of any legitimate disbursement. When I found mine, it was buried in a folder labeled "Loan Docs" from a refinancing I did the prior year. The processor had sent the payoff statement there, and the charge on my statement was the final disbursement from that transaction chain.
When It Is Actually A Problem
Most charges from Fid Bkg Svc LLC are not fraud. But the processor is available to anyone who meets underwriting, so bad actors have used it too. The red flags are specific and I want you to notice them because beginners usually look at the wrong things. The first red flag is a small test charge. A fraudster will sometimes push a $0.50 or $1.23 transaction to confirm your account is active before running a larger pull. If you see a micro-charge from this processor that you never initiated, that is a warning sign. Report it immediately. Do not wait for the next statement cycle. The second red flag is a mismatch between the amount and any record you keep. If you pay a known bill every month on the 15th, and suddenly Fid Bkg Svc LLC pulls $847.33 on the 3rd with no corresponding invoice, dig into it. The amount should match something you can identify. If it does not, file a dispute with your issuing bank and request the merchant category code and the underlying trace number.
The third red flag, and this one surprises people, is when the charge appears twice within twenty-four hours for the same amount. This can happen legitimately if your servicer retries a failed ACH, but it can also indicate a system glitch or an unauthorized duplicate submission. Call both the processor and your bank. Get it resolved in writing. I once spent three days chasing a duplicate filing after my servicer's automated retry engine triggered two submissions. The workaround was to submit a written stop instruction to the servicer directly, not just to the bank, because the bank could not cancel a transaction that had already settled through a separate clearing path.
What To Do If You Cannot Identify The Charge
Here is the practical workflow that actually works. Start by contacting the processor. Fid Bkg Svc LLC has a customer service line and an email address listed on their corporate site. Provide your full name, the account number linked to the charge if you know it, the exact amount, and the date. Ask for the originator name and the merchant category. They are required to provide that under Regulation E for electronic fund transfers. If the processor cannot identify the origin or gives you a vague answer, call your bank and initiate a formal dispute. Do not just flag it in the app. Apps route disputes through a generic portal that often delays investigation by a week. Call the number on the back of your card or visit a branch. Request a written acknowledgment and a provisional credit while the investigation runs. Keep a paper trail. Save every confirmation number, every email, and every call log with timestamps. The banks and processors rely on the paper trail to move files faster. Without it, your dispute sits in a queue behind people who submitted proper documentation.
If you suspect fraud, freeze your account immediately. Most banks allow you to do this through their mobile app in under two minutes. Then call the fraud department. Do not try to untangle a fraudulent charge yourself before the freeze. The processor can replay a disputed ACH if the account is still open.
Why The Processor Exists And Why It Matters
Fiduciary banking services exist because not every lender, servicer, or fiduciary wants to maintain a direct relationship with every depository institution their customers use. Setting up ACH origination agreements with hundreds of banks is expensive and slow. A centralized processor consolidates those relationships and presents a single descriptor on consumer statements. It reduces onboarding time for merchants and gives them better reconciliation tools. The tradeoff is that consumers often see an unfamiliar name and assume the worst. From a compliance angle, the processor is registered with the NACHA rules and holds an OTS or equivalent charter that allows it to originate electronic transfers. This is not some shell entity. It is a regulated routing channel. That does not make every charge legitimate, but it does mean the processor has obligations to investigate and respond to disputes within regulatory timeframes. One nuance that nobody mentions is the difference between the originator and the facilitator. Fid Bkg Svc LLC is usually the facilitator. The originator is the actual merchant or lender. When you dispute a charge, the bank investigates the facilitator's compliance, but the originator is the one who can reverse or confirm the transaction. If the facilitator says everything looks clean and the originator never responds, your dispute can stall. The workaround is to demand the originator's name and contact from the facilitator, then reach out directly. I have resolved more disputed charges this way than through the bank alone.
Practical Tips That Actually Help
Monitor your statements weekly, not monthly. Most people wait for the end-of-cycle PDF and by then three suspicious charges may have settled. A weekly sweep takes about twelve minutes and catches problems before they compound. Label the descriptor in your budgeting app. Create a catch-all category called "Fiduciary Processing" and assign it to any transaction that carries this name. Over a few months, you will see patterns emerge. You will know which amounts are normal for your accounts and which ones are anomalies. Keep a spreadsheet of your recurring payments with the expected amount, date, and merchant. When a charge appears, match it in under thirty seconds. If it does not match, you immediately know to investigate rather than assuming the worst.
Do not assume a charge is fraudulent just because the name looks unfamiliar. Verify first. The majority of Fid Bkg Svc LLC charges are legitimate and simply reflect a payment rail you did not expect. The processor is common enough that it appears on thousands of everyday transactions across the country. Unfamiliar does not equal illegal. If you need the official contact information for the processor, search for "Fid Bkg Svc LLC contact" or "Fiduciary Banking Services LLC customer service." The corporate site lists their dispute and inquiry channels. Use those first before escalating to your bank, because the bank will ask you to resolve the issue with the originator anyway.
Bottom Line
A charge from Fid Bkg Svc LLC on your bank statement is usually a processing descriptor, not a mystery theft. Match the amount and date to your known obligations. Check your email for receipts. Contact the processor for originator details if nothing lines up. Dispute only after you have gathered evidence. Most problems resolve within five to ten business days once you have the right documentation in front of the right team. The times it does not resolve cleanly are the edge cases: duplicates, test charges, and stale ACH filings. Those require a freeze, a direct appeal to the originator, and a written complaint to the CFPB if the bank drags its feet.


