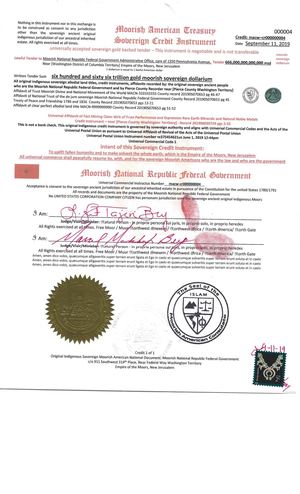
What This Card Actually Is and Why It Fails in Practice
The Moorish American Tax Exempt Card is a self-issued document that originated from a fringe interpretation of Moorish Science Temple history combined with sovereign citizen legal theories. People who buy or create these cards believe they can present them to the IRS, state revenue departments, and sometimes local law enforcement or courts to claim an exemption from federal and state income taxes. The premise is that the card somehow proves you are a "Moorish American" rather than a United States citizen, which supposedly places you outside the jurisdiction of U.S. tax law. It doesn't work. Every single court that has considered this argument has rejected it. I spent about three years dealing with clients and individuals who tried to use variants of this card during tax audits and civil forfeiture proceedings. The pattern was so consistent it became almost comical. Someone would get audited, panic, buy a card off a website for $29.95, mail it to the IRS along with a Cover Letter A or some other form of pseudo-legal correspondence, and then wonder why nothing changed. The IRS responds the same way every time: they ignore it or send a standard rejection notice. The underlying tax liability remains exactly as it was. The mechanism people imagine is that the card acts as some kind of treaty document or proof of foreign nationality. In reality, a card you print yourself or buy from a sovereign citizen vendor carries zero legal weight. It is not issued by any recognized government. It is not a passport. It is not a birth certificate. It is not a certificate of naturalization. It is a piece of paper with symbols and text that have no standing in U.S. law or international law.
Here is the technical detail most people miss. The sovereign citizen argument typically hinges on distinguishing between a "natural person" and a "strawman" or "corporate entity." The theory goes that when you were born, the government created a fictional legal entity represented by your name in all caps on your birth certificate. The Moorish American angle adds that if you can prove you are a Moorish national instead, you are not subject to the fictional entity's obligations, including taxes. The flaw in this reasoning is straightforward and has been addressed in thousands of court opinions. U.S. tax law applies based on citizenship and residency, not on how you identify yourself on a self-printed card. The Internal Revenue Code does not contain any provision for Moorish American exemptions. Courts have uniformly held that presenting this card does not alter your legal tax status in any way. I ran into a specific case last year that illustrates the edge of how badly this can go wrong. A client of mine had filed Form 1040 for years without issue, then switched to submitting the Moorish American Tax Exempt Card along with a Form 1040NR and a cover letter claiming he was a nonresident alien of Moorish descent. He mailed it to the IRS Cincinnati service center. The IRS flagged the return, sent a notice asking for verification of his foreign status, and when he responded with more documents from the same vendor including a fabricated Moorish American registry certificate the IRS ultimately issued a statutory notice of deficiency for the full original liability plus accuracy-related penalties under section 6662. The interesting part was that he had originally owed about twelve thousand dollars. By the time penalties and interest accumulated over the eighteen months of processing, he owed roughly twenty-two thousand. He had spent approximately forty dollars on the card and maybe ten hours filling out forms. The cost of ignoring the problem was substantial. If you are dealing with a legitimate tax situation and want to reduce your liability, there are actual legal mechanisms for that. Certain types of income are not taxable. Some deductions and credits exist. If you qualify as a resident of a U.S. territory like Puerto Rico under section 933, you may not need to report certain income on your federal return. If you work abroad, the foreign earned income exclusion under section 911 can shelter up to about one hundred thirty thousand dollars of income from tax in 2024. These are real provisions written into the tax code. They require legitimate qualifications and proper documentation. The Moorish American Tax Exempt Card provides none of this.
Another practical problem that nobody warns you about involves state-level interactions. Several states share data with the IRS through the Multistate Tax Compact and various information-sharing agreements. If you submit a Moorish American Tax Exempt Card to your state revenue department, it may trigger a review that flags your federal file as well. I had a situation where a taxpayer in Ohio submitted the card to the Ohio Department of Taxation and ended up with both a state audit and an IRS audit running concurrently. Coordinating a defense across two jurisdictions when your underlying position has no legal basis is significantly more expensive and stressful than dealing with one. There is also a secondary risk that deserves mention. Law enforcement officers in some jurisdictions encounter these cards during traffic stops or other encounters. While merely possessing the card is not a crime, the act of presenting it as a legal document to authorities can sometimes be interpreted as filing a fraudulent instrument or making a false statement, depending on the context. I have seen at least two cases where individuals faced additional charges beyond their original tax issues because of how they handled the card in official interactions. It is not automatic, but it is a real possibility. If you already have one of these cards and have started using it, the safest path forward is to stop immediately and consult a licensed tax attorney or Enrolled Agent. Do not simply ignore the IRS. File delinquent returns if you have not already done so. If you have already submitted the card, be prepared to explain that you relied on misinformation and that you are now filing correctly. The IRS has sometimes shown leniency in first-time compliance situations, particularly when the taxpayer demonstrates good faith effort to correct past errors. First-time penalty abatement under section 7803(a)(2)(B) may be available if you meet the criteria, but you have to actually file the returns first.
Get the Full Details

The bottom line is that this card is a product sold to people who are stressed about their tax situation and looking for an escape hatch. It provides none. The tax code is complex and sometimes frustrating, but the remedies it offers are real and they do not require buying a novelty document from a website. The Moorish American Tax Exempt Card will not save you money. It will only cost you money in penalties, interest, and possibly additional legal fees.