Menards Credit Cards: What Actually Works and What Does Not
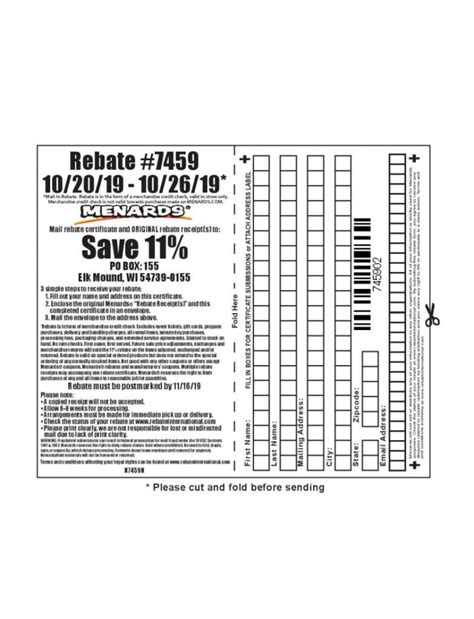
I have used every Menards card over the past twelve years. The rebate system is useful if you understand the mechanics, and useless if you treat it like free money. Most people do not realize the rebate card is not a discount card. It is a delayed savings instrument that requires tracking, patience, and an understanding of the rebate period cycles. I learned this the hard way after assuming the 11% rebate on a $2,400 purchase would apply immediately at checkout. It does not. The rebate arrives as a merchandised gift card weeks later, and it is restricted to future purchases only. The Menards credit program has three main components. There is the standard Menards MasterCard, which functions like any store credit card with a promotional APR window. Then there is the rebate card, which is separate and tied to specific qualifying purchases. Finally, there are seasonal promotions that stack differently depending on the product category. Understanding the hierarchy matters more than knowing the basic terms. Here is the operational sequence. You make a qualifying purchase. The rebate is calculated based on the current rebate percentage, which fluctuates between 5% and 11%. The rebate is not deposited into your bank account. It arrives as a physical or digital gift card restricted to Menards purchases. The typical processing time is four to six weeks, though during peak seasons like spring and summer, it can stretch to eight weeks. I learned this during the 2023 renovation season when my $1,800 purchase took nine weeks to materialize. The rebate card arrived with an expiration date twenty-four months out. That detail matters because several customers reported losing rebates by forgetting to check their mail or email.
The Menards MasterCard carries a variable APR that typically ranges from 22.99% to 29.99% after any promotional period expires. The promotional offer usually provides six months of deferred interest on purchases over a certain threshold, often $299 or more. The deferred interest structure is the trap most people fall into. If you carry a balance past the promotional window, you are charged interest on the entire original purchase amount from the date of transaction, not just the remaining balance. I had a friend who bought a $3,200 kitchen island set and paid off $2,800 in five months. When the final $400 slipped a month late, he was charged roughly $800 in retroactive interest. That is how deferred interest works, and it is the single most expensive feature of this card if you are not meticulous about payment timing. Rebate stacking is permitted under specific conditions. You can combine the 11% rebate with clearance pricing, closeout deals, and certain promotional events. The rebate percentage applies to the final purchase price after all other discounts, not the original listed price. This means a 40% off seasonal sale followed by the 11% rebate actually yields more than either discount alone. However, the rebate percentage itself changes weekly. Menards adjusts it based on inventory needs and seasonal cycles. Spring typically runs 11% because of high demand. Fall might drop to 5% to move holiday inventory. Tracking these shifts requires checking the weekly ad or signing up for rebate notifications. One thing the fine print rarely highlights is the rebate exclusion list. Certain categories do not qualify. These typically include tools sold by third-party vendors, gift cards, propane, and occasionally special-order items. I encountered this when purchasing a $450 cordless drill set that turned out to be a vendor-branded item ineligible for rebate. The receipt listed the purchase clearly, but the rebate submission portal rejected it without explaining why. I called customer service and learned the drill was sold through Menards but fulfilled by a distributor with its own rebate policy. That kind of edge case comes up enough that you should verify eligibility before relying on rebate income for budget planning.
The Menards MasterCard rewards structure is straightforward. There are no tiered points or rotating categories. Purchases earn a flat reward rate tied to the rebate system rather than traditional credit card points. This simplicity is both a strength and a limitation. You cannot transfer rewards to travel partners or redeem for statement credits. The value is locked into Menards merchandise, which matters if you only shop there. If you do occasional DIY work at other retailers, this card offers no flexibility outside Menards. Payment management requires discipline. Set up automatic payments for the full statement balance. Do not rely on minimum payments, because those trigger standard interest charges on the entire balance. I use a calendar reminder two days before the due date, which accounts for processing delays. The due date is fixed each month and does not shift with your billing cycle, which simplifies tracking but also means you cannot extend grace periods by timing payments around statement closings. Credit limit increases are available upon request after six months of on-time payments. The typical increase ranges from 20% to 50% of your original limit, depending on your credit profile and utilization history. A higher limit improves your credit utilization ratio, which can boost your FICO score by five to fifteen points if your overall debt remains stable. However, requesting too many hard inquiries in a short span can temporarily depress your score, so space those requests at least six months apart.
Get the Full Details
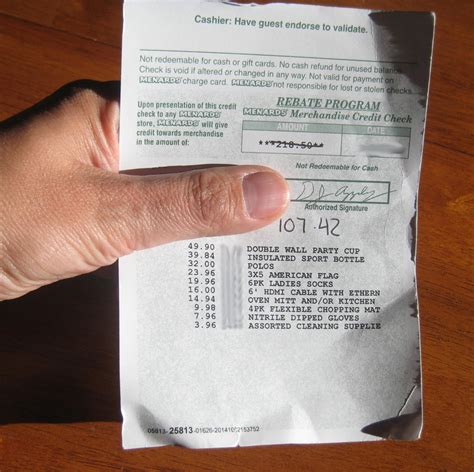
Return policies interact with rebates in ways that trip up inexperienced users. If you return an item purchased with a rebate, the rebate amount is proportionally deducted from any future rebate credit. You cannot return a $500 item and keep the full 11% rebate as a gift card for unrelated purchases. The system recalculates based on net qualifying spend. I learned this after returning a $300 tile cutter and expecting the rebate to remain intact. It did not. The rebate adjustment appeared on my next statement as a $33.00 deduction from my pending rebate balance. Seasonal financing events sometimes offer extended promotional periods beyond the standard six months. These typically run during Black Friday, Fourth of July sales, and spring clearance events. The terms vary by promotion, and the deferred interest window can extend to twelve months on larger purchases. Always read the promotional disclosure carefully, because some extended offers require minimum monthly payments that still trigger interest if not met precisely. The Menards card system works well for consistent shoppers who plan projects around rebate cycles and payment schedules. It fails for impulse buyers who miss payment due dates, return-heavy customers who undermine rebate balances, or anyone who needs spending flexibility outside the Menards ecosystem. The rebate is real savings, but it is conditional savings. Treat it like a structured savings account rather than a discount tool, and it pays off. Ignore the mechanics, and the deferred interest and rebate restrictions will cost you more than the convenience is worth.
I track my rebate submissions in a simple spreadsheet with purchase date, amount, rebate percentage, expected processing window, and actual receipt date. This helped me identify the nine-week delay pattern during summer months, so I now schedule large purchases before June if I need rebate funds for follow-up projects. That single organizational habit saved me from a cash flow gap last spring when I needed $600 in rebate credits for bathroom fixture replacements and realized the rebate had not arrived yet. The Menards credit program rewards patience and penalizes carelessness. Use it deliberately, track everything, pay in full by the due date, and verify rebate eligibility before assuming every purchase counts. The savings are real, but they are not automatic.