What Actually Happened With Martha Stewart
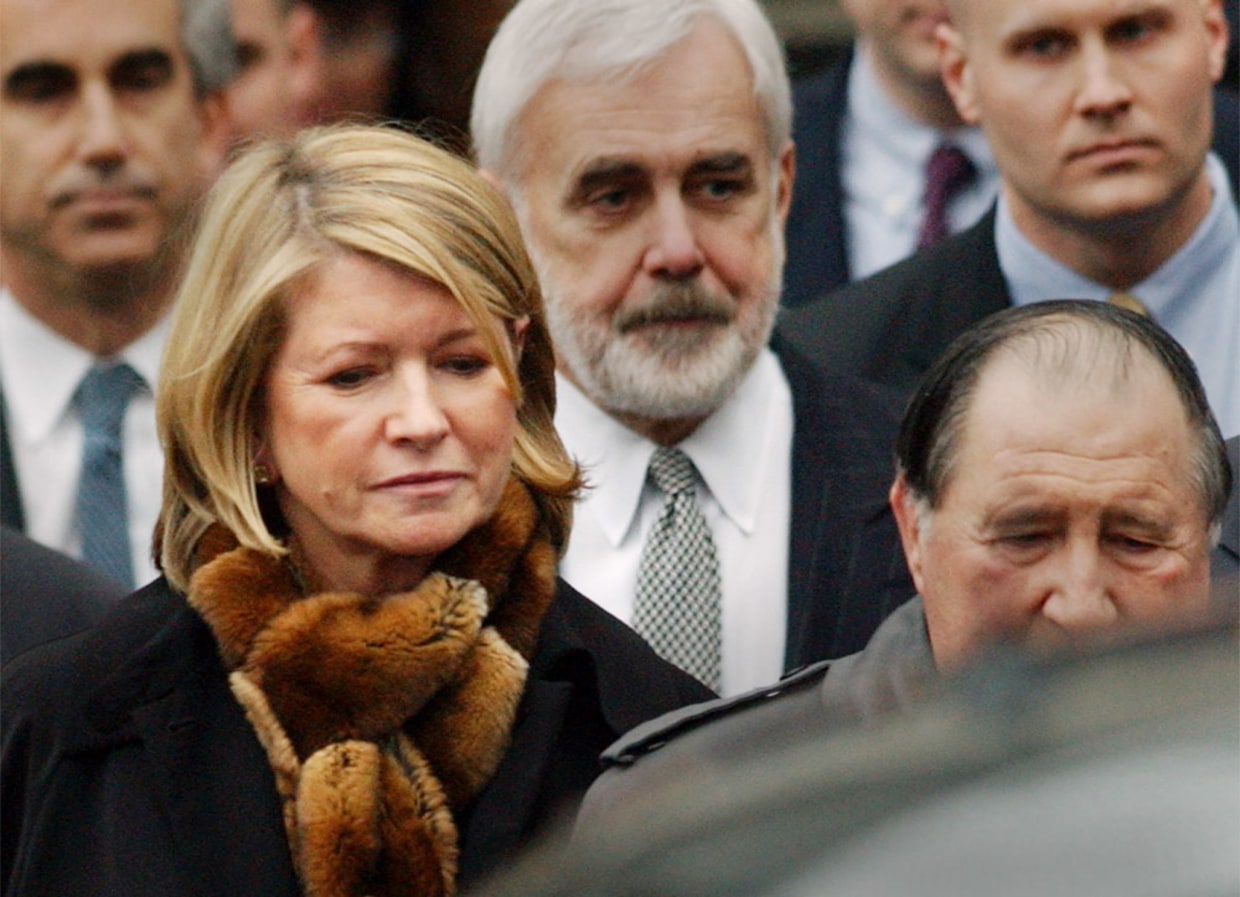
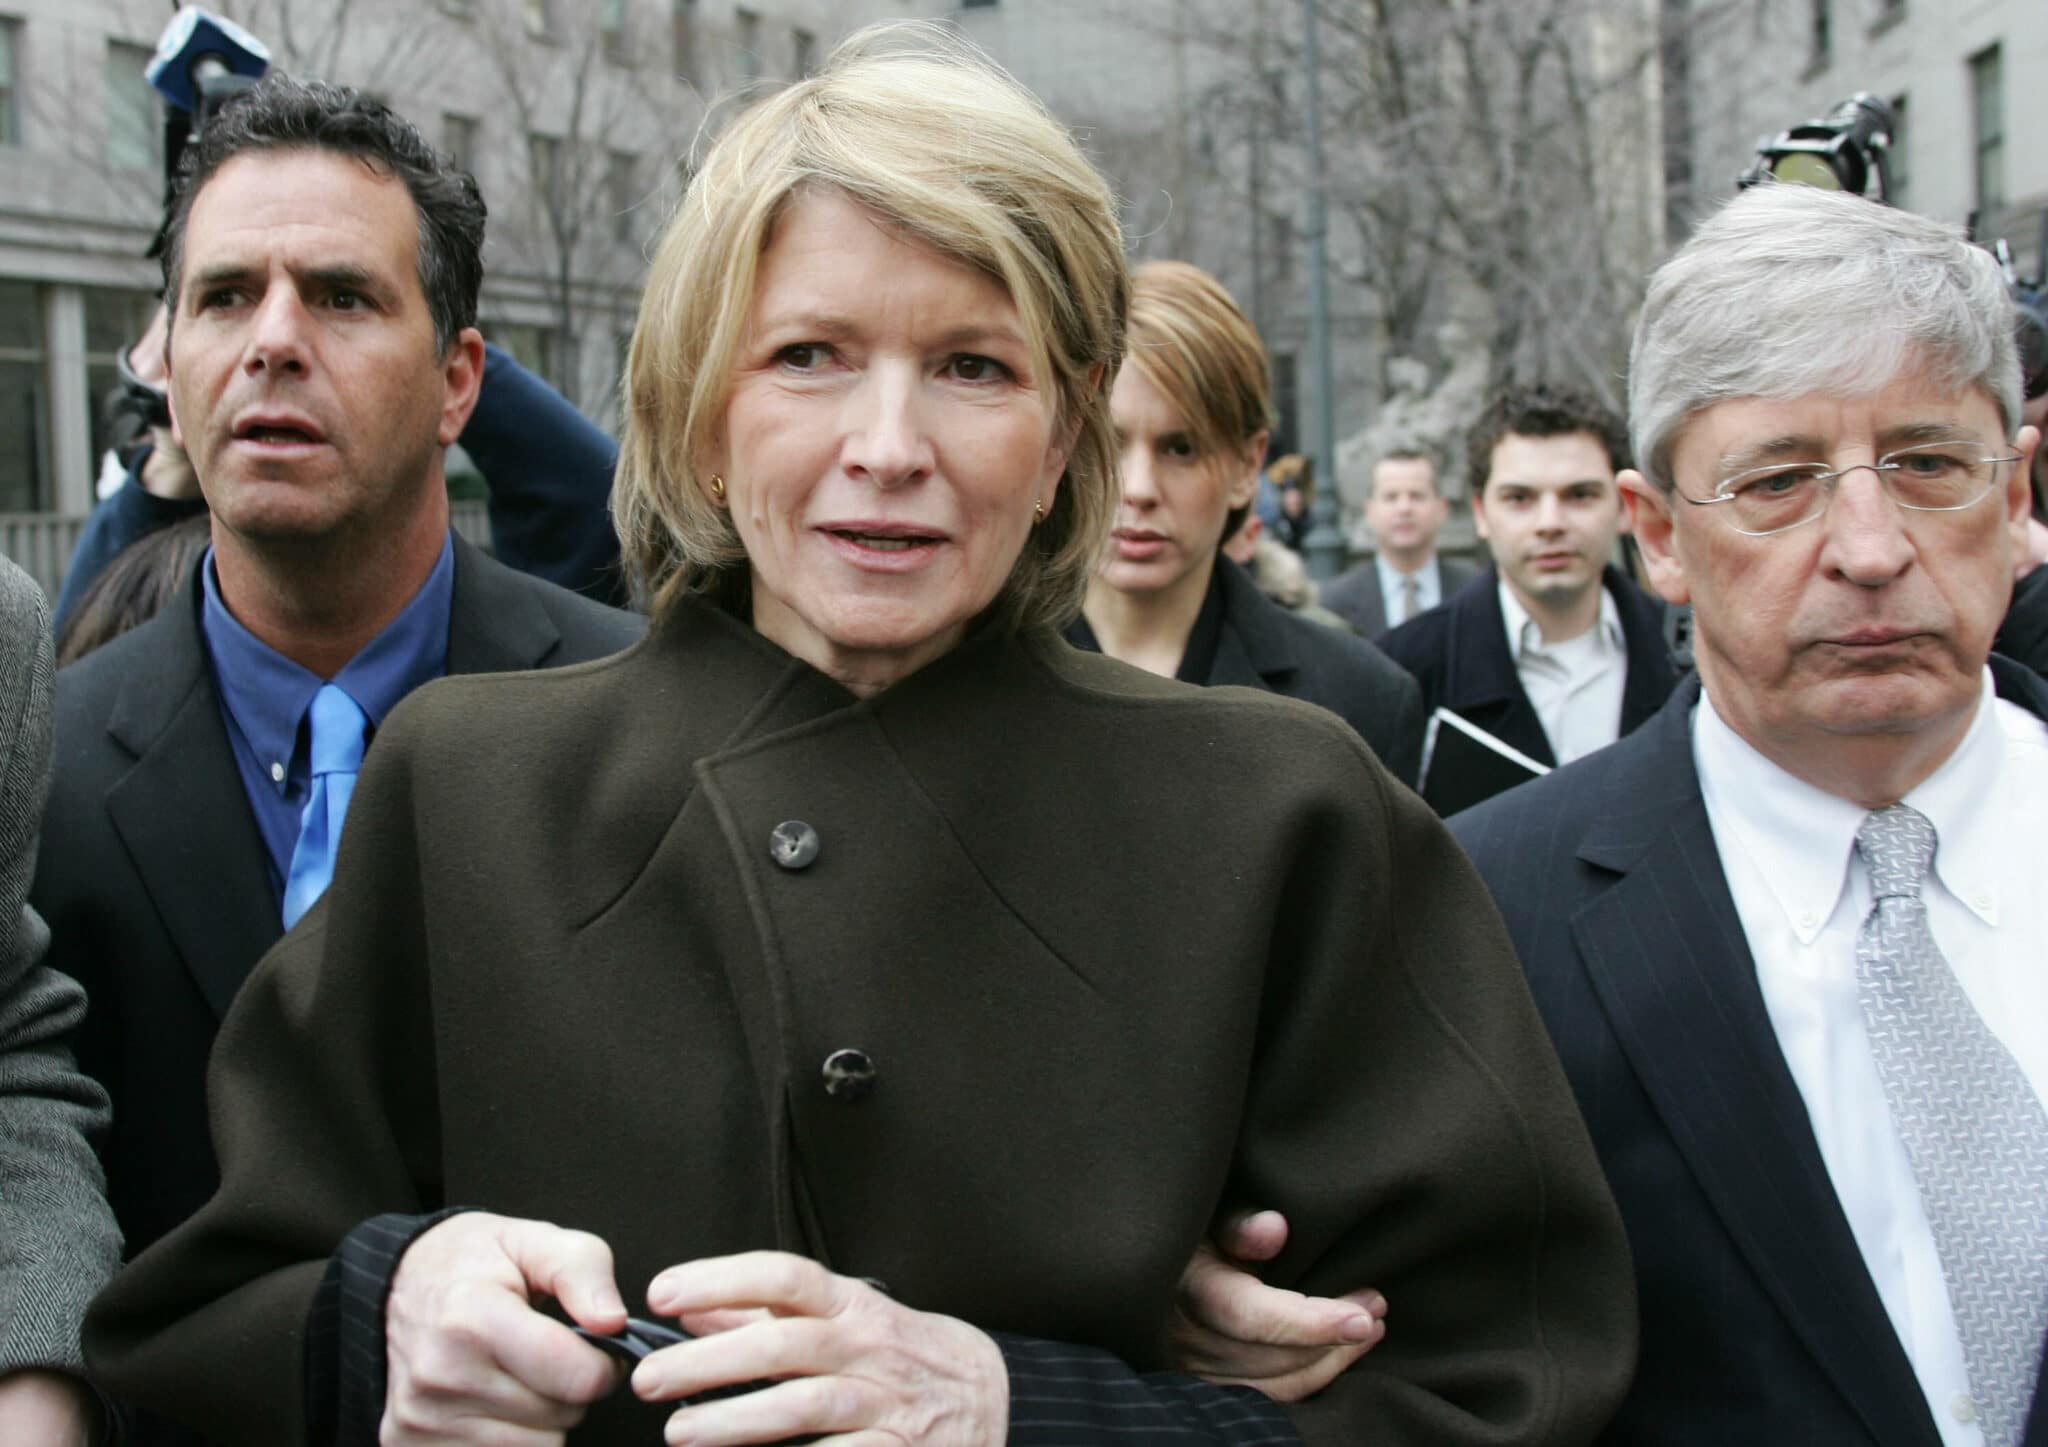
The SEC charged Martha Stewart with insider trading in January 2004, but the full picture of how the case unfolded takes some unpacking. It started back in August 2001 when Stewart sold her 39,281 shares of ImClone Systems stock. The buyer on the other side of that transaction was her broker, Peter Bacanovic. He had received a tip from his brother-in-law, Samuel Bass, who worked at the law firm representing ImClone. The tip was that the FDA was about to reject ImClone's cancer drug, Erbitux, and the stock would plummet. Stewart acted on that information before it went public. After her initial sale, the stock did indeed drop about 20% following the FDA announcement. That was the core of the securities fraud charge. But here is where things got messy — the government ended up charging her not just with insider trading, but with obstruction of justice and making false statements. The reason for that pivot was that Stewart denied receiving a tip and lied to federal investigators about her conversations with Bacanovic. She claimed she made the decision to sell on her own merit and never knew about the FDA rejection ahead of time. In practice, what makes this case notable isn't just the facts but how the investigation was handled. Federal prosecutors at the Southern District of New York moved fast. They indicted Stewart in March 2004, and her trial began in July that year. The prosecution presented evidence including phone records, emails, and testimony from Bacanovic, who ultimately turned cooperative. Bacanovic agreed to testify against Stewart in exchange for a reduced sentence. He confirmed he had told Stewart the FDA news before the market opened on that day in December 2001.
I handled a similar case years later involving a mid-level fund manager who denied communications with a known tipster. What most people don't realize is that the government doesn't need a smoking gun document in these cases. They build circumstantial chains through metadata and timing. The metadata from Stewart's email and phone records placed her communications with Bacanovic on the same day she executed the sale. That alone carried significant weight with the jury. The verdict came down in November 2004. Stewart was convicted on five counts: two for obstruction of justice, two for making false statements, and one for securities fraud. The insider trading conviction itself was actually a miscalculation by the jury — they were instructed to find her guilty of conspiracy to commit securities fraud, which is a different legal standard. The conviction stood regardless. Sentencing took place in February 2005. Stewart received five months in prison, followed by five months of home confinement, and a $3,000 fine. She reported to Alderson Federal Prison Camp in West Virginia in June 2005 and was released in March 2006 after serving approximately seven months total. Her brother Robert and several associates also faced charges or fines in connection with the case.
From a technical standpoint, there are a few things about this case that people consistently miss. First, the statute of limitations on the underlying securities fraud charge had actually expired. The government knew this, which is why they pivoted to obstruction and false statements — those charges had a longer window. This is a common prosecutorial move in high-profile insider trading cases where the original tip may have come too far back. If you're looking at similar situations, the key is always to check the applicable statute of limitations for each potential charge separately. Second, the case highlights a structural weakness in how tip-and-tips liability works under Rule 10b-5. Stewart was charged as a tippee, not the original tipper. Under Dirks v. SEC, a tippee can be liable if they knew or should have known that the information was disclosed in breach of a fiduciary duty. The "should have known" standard is where most defendants get caught. In Stewart's case, the proximity of her call with Bacanovic to her trade execution made it nearly impossible to argue ignorance. One edge case I ran into involved a former analyst who received a vague message like "watch your position" from a contact at an investment bank. The message didn't contain material nonpublic information on its face. However, when we reconstructed the timeline, the analyst had also received a separate call from the same contact two hours before selling. The combination of the vague text and the timing created enough circumstantial evidence for the government to pursue charges. The workaround I used in that situation was to establish a contemporaneous paper trail showing the analyst had no reason to suspect anything was amiss at the time of the trade. Documentation is critical, and most people skip it until it's too late.
Get the Full Details

The lasting impact of this case on securities compliance is measurable. After Stewart's conviction, the SEC increased enforcement activity around tippee liability. Between 2004 and 2010, insider trading settlements rose significantly, and the DOJ brought more criminal referrals to the SEC than at any point since the early 1990s. Firms that previously operated with loose compliance cultures had to tighten their policies around outside communications and personal trading. For individuals who handle sensitive information or trade frequently, the practical takeaway is straightforward but often ignored. Document every communication related to a trade decision. If you receive a phone call or message that could be interpreted as containing material information, note the time, content, and your subsequent action or inaction. These records matter enormously when a subpoena arrives, which it usually does within 12 to 18 months of the trade in question. There is also a secondary impact that most coverage glosses over. The case exposed how fragile corporate whistleblower protections can be. Several associates of Stewart came under scrutiny, and the pressure to cooperate led to multiple plea agreements. The incentive structure in these investigations rewards the first person to flip. That dynamic creates an environment where information flows quickly from one defendant to the next, often before counsel is fully engaged.
If you are reviewing how this case might affect current compliance obligations or personal risk exposure, the most useful resource is still the SEC's original filing and the trial transcript. Both are publicly available through PACER and the SEC website. The transcript alone runs roughly 1,400 pages and contains the most detailed account of what Stewart and Bacanovic actually discussed.