What You Actually Have When Everything Falls Apart
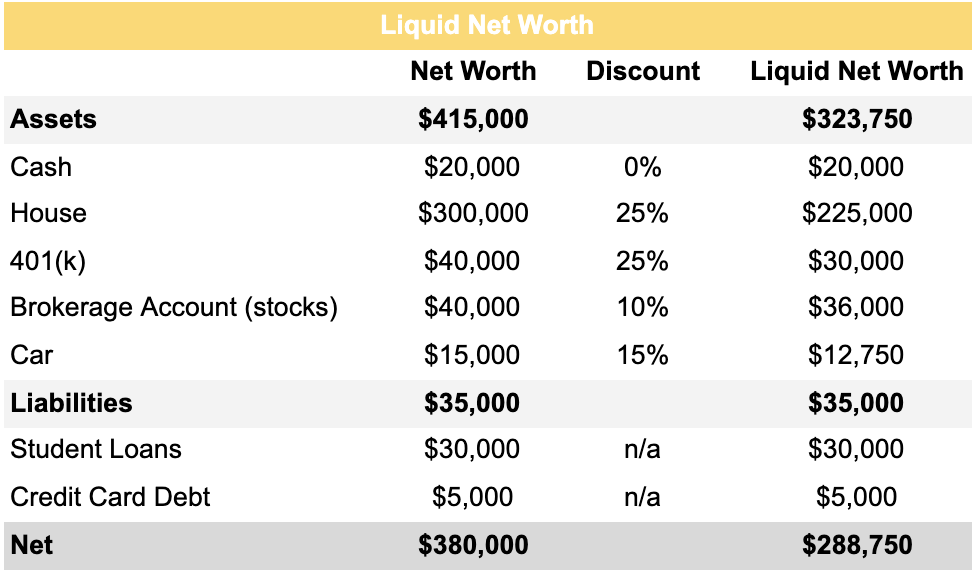
Most people calculate their net worth by adding up their house, retirement accounts, vehicles, and whatever they own, then subtracting debt. The number looks impressive. It is mostly imaginary money. The version that matters when you lose your job, get an unexpected medical bill, or your business revenue drops overnight is something entirely different. Liquid net worth is the number that determines whether you panic or you breathe. Liquid net worth is the total value of assets you can convert to spendable cash within 30 days without taking a significant loss or triggering tax penalties. That includes checking and savings accounts, money market funds, short-term Treasuries, publicly traded stocks and ETFs you own outright, and the cash surrender value of whole life insurance if you have it. It excludes your home equity, retirement account balances, collectibles, private business ownership stakes, and anything with a sale timeline longer than a month.
The Liquid Net Worth Everyone Ignores That Could Change Your Life
I learned this the hard way in 2020. My business income dropped to zero for eight weeks. My total net worth on paper was roughly 1.4 million dollars because of my home and a small commercial property. My liquid net worth at that moment was about 18,000 dollars across two bank accounts and a brokerage account tied up in a position I was too hesitant to sell at a temporary dip. Paying rent and payroll became an actual problem, not a theoretical one. The gap between those two numbers is why liquid net worth deserves its own tracking system instead of living as a footnote in your annual financial checkup. Here is how you actually calculate it without wasting an afternoon on it. Step one is listing every account you have. Bank accounts, brokerages, certificates of deposit maturing within a year, money market funds, and any short-term government securities. Write down the current balance for each one. Step two is identifying which of those assets would actually be available to you right now. If you have a taxable brokerage account with mutual funds or stocks, it counts. If it is in a 401k or traditional IRA, it does not count toward liquid net worth unless you are over 59 and a half and willing to eat the penalties and taxes, which most people are not in an emergency scenario. Step three is applying a haircut to assets that are not trivial to sell at fair value. Stocks and ETFs in a taxable account get a five percent haircut to account for volatility and bid-ask spreads. Private notes or promissory notes you are owed generally do not count unless the other party has already wired the money. Collectibles listed as assets in your total net worth calculation get removed entirely.
There is a specific edge case that trips people up constantly and almost nobody warns you about it. Health savings accounts. An HSA is technically a triple tax advantage vehicle, but the liquid net worth treatment depends on how you are using it. If you have receipts and intend to use the funds for qualified medical expenses later, some people argue it should not count as liquid because pulling it out for nonmedical reasons before age 65 triggers a penalty plus taxes. I include HSAs in my liquid net worth calculation regardless of the technical nuance because in a real emergency a hundred and twenty dollars in an HSA is real money you can use, and the penalty is a math problem you solve later. The exact workaround I use is tagging HSA balances separately in my spreadsheet so I can see two numbers: full liquid net worth including the HSA, and core liquid net worth excluding it. That distinction matters when you are presenting the number to a lender or making a spending decision under stress. Another thing beginners miss is the assumption that a high yield savings account always equals liquid assets. It does, but the moment you move money into a laddered CD structure with maturities beyond a year, those balances leave your liquid net worth entirely. I see people build elaborate CD ladders for yield optimization and then forget the money is locked away when they need it. The fix is simple. Keep a separate bucket in your tracking spreadsheet labeled liquid emergency reserve that excludes any CD with a maturity date more than twelve months out. Rebalance this bucket quarterly. If your total liquid net worth is below three months of essential expenses, stop investing in longer-term instruments until it reaches that threshold. Yield is irrelevant when liquidity is zero. The number you are aiming for is not arbitrary. Three to six months of essential living expenses stored in liquid form is the standard target. Essential expenses means rent or mortgage, utilities, groceries, insurance premiums, minimum debt payments, and transportation. It does not include dining out, subscriptions, vacations, or discretionary spending. If your essential monthly burn is four thousand dollars, your liquid net worth target sits between twelve thousand and twenty-four thousand dollars. Anything below twelve thousand means you are one unexpected event away from borrowing at high interest. Anything above twenty-four thousand sitting in a checking account is inefficient and you should consider parking the excess in short-term Treasuries or a money market fund that still qualifies as liquid.
Get the Full Details

This approach has real limitations and it fails completely in certain scenarios. Liquid net worth does not protect you from inflation erosion if your liquid assets are mostly cash in a low yield account. It also does not help if your liquid assets are concentrated in a single volatile stock that drops forty percent the week you need the money. Diversification within the liquid bucket matters as much as the size of the bucket. A liquid net worth of fifty thousand dollars in a single tech stock is not the same as fifty thousand dollars spread across a broad market ETF and a money market fund. I learned this when a position I thought was liquid turned out to be illiquid in practice because selling it would have triggered a taxable gain I could not afford at that moment and the price had already gapped down. The workaround was maintaining a rule that no single holding exceeds twenty-five percent of the liquid bucket. It keeps you from having that conversation with yourself during a crisis. Retirement accounts create the biggest distortion in liquid net worth calculations. A forty-seven year old with two million dollars in retirement accounts and fifteen thousand dollars in a checking account has a total net worth of two million and fifteen thousand but a liquid net worth of fifteen thousand. The retirement accounts are not liquid in any meaningful sense for someone under fifty. The common mistake is treating Roth conversion potential or home equity lines of credit as liquid substitutes. They are not. An HECM or HELOC requires qualification, closing costs, and approval time that can take thirty to sixty days. That is not liquidity. That is delayed access with fees. Track them separately if you want to include them in a broader solvency picture, but do not let them inflate your liquid net worth number. The practical tool for tracking this is a spreadsheet or a simple app that pulls balances automatically from your financial institutions and runs the classification logic for you. Manual entry introduces errors because people forget to update one account and then wonder why the number looks wrong. If you are doing this manually, refresh your balances every Sunday evening and set a calendar reminder for the first Monday of each quarter to review the classification rules and adjust for any accounts that have changed status. The entire process takes about twenty minutes once you have the system set up.
There is also a behavioral component that nobody talks about. Knowing your liquid net worth accurately changes how you make decisions. People with a well tracked liquid reserve tend to make different choices during income disruptions because the anxiety of not knowing is removed. You stop making desperate decisions when you actually know you have a cushion that will cover six months of essential expenses. That psychological benefit is measurable in the sense that it prevents the kind of impulsive debt that derails finances for years. But it is not a substitute for actually building the cushion. Awareness without capital is just a spreadsheet. One more thing that people get wrong is the timing of when they start tracking this. Most individuals do not calculate their liquid net worth until after a crisis hits. That is too late. Start now even if the number is small. A liquid net worth of two thousand dollars tracked consistently is more useful than a liquid net worth of ten thousand dollars you discover by accident during an emergency. The habit of monitoring it monthly builds the discipline to add to it before you need it, which is the only thing that actually moves the number over time.