So you want to understand liquidity
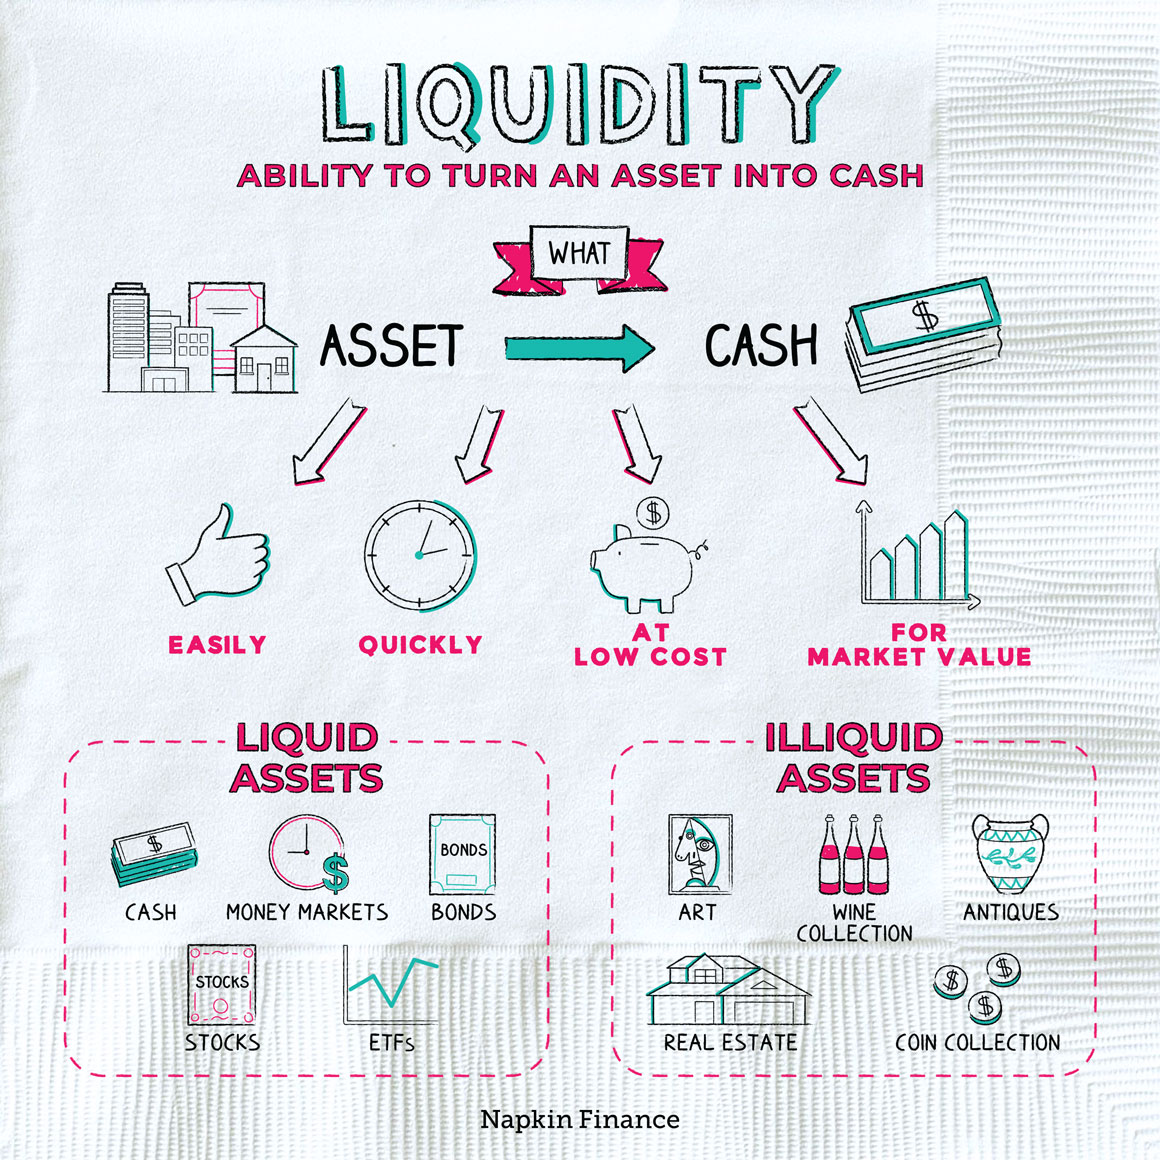
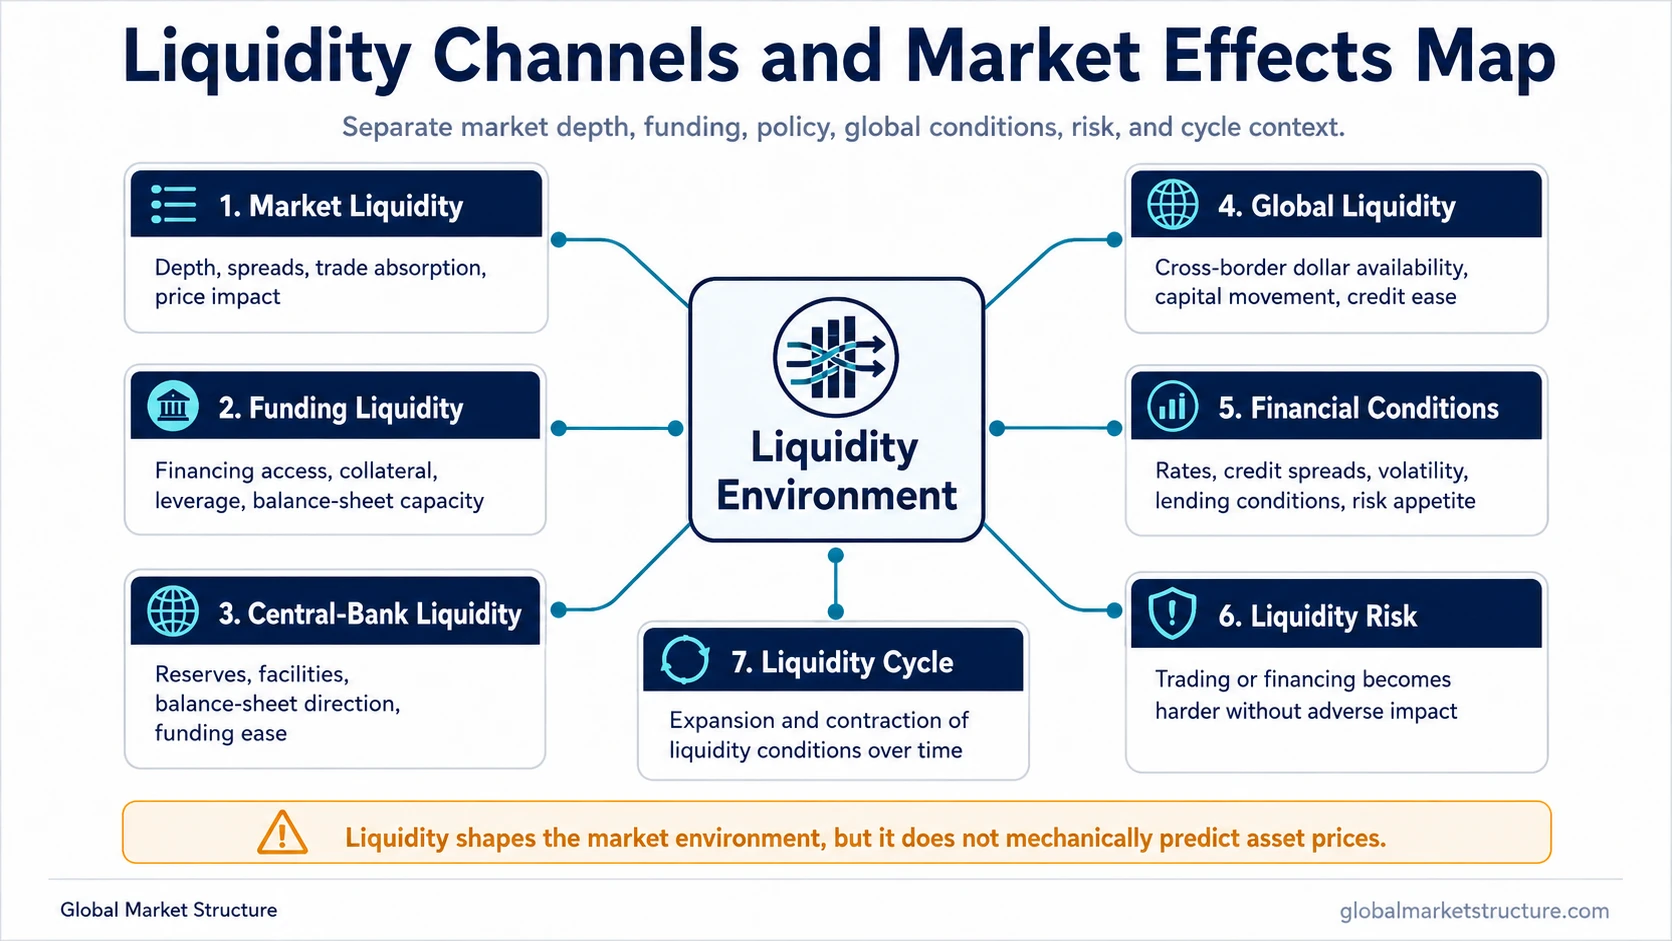
Liquidity is one of those terms that sounds straightforward until you actually need to explain it under pressure. I spent about eight years working market microstructure and watching institutions get burned by thin books, so I have some opinions about this. Not trying to be profound. Just factual. At its core, liquidity means you can buy or sell something without moving the price much. That is it. If I need to dump 50 million shares of a stock and the market absorbs it in a few minutes with less than ten basis points of slippage, that stock is liquid. If the same order takes three days to fill and moves the price five percent, nobody with a pulse would call that liquid regardless of what the textbook says. The problem is that liquidity is not a single number. It has at least three dimensions, and most people only look at one of them. The first is breadth, which is just how big a trade you can do near the current price. The second is depth, which is about the volume sitting at each price level in the order book. The third is resiliency, which measures how quickly prices snap back after a big trade hits. You can have a market that looks deep today and completely evaporates tomorrow. That happened to me with a mid-cap industrial I was tracking back in 2018. The bid-ask spread was a solid twelve cents on a sixty-dollar stock, looked perfectly fine on any screener. Then earnings came out, and suddenly the market maker pulled the entire book. I watched two million shares trade at whatever price the last desperate seller could get. No resiliency whatsoever.
The Liquid Foundation Of Economics Understanding Liquidity Definition And Its Impact On Markets
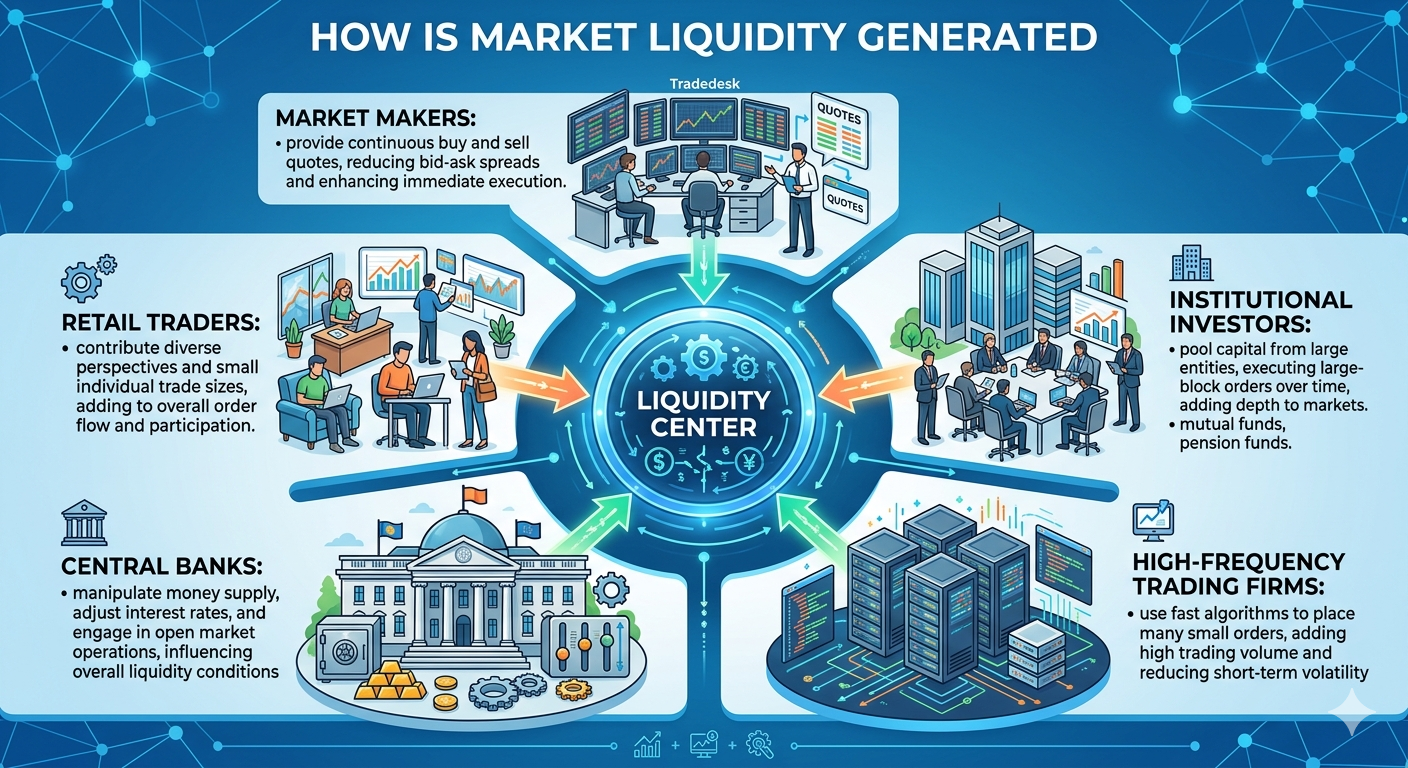
When economists talk about liquidity in a macro sense, they are usually referring to how easily assets convert into cash without loss of value. This is different from the microstructure view but they interact constantly. A country with illiquid government bond markets tends to have higher borrowing costs across the board. It shows up in the yield curve, and it shows up in corporate spreads too. Here is what most people miss when they first study this. Liquidity is procyclical. It gets worse exactly when you need it most. During normal times, market makers post tight spreads because the risk is manageable. When stress hits, their capital constraints kick in, and they widen spreads or step away entirely. This is not malice. It is math. The VaR models on their desks force them to reduce position sizes, and the last thing they want is to be stuck on the wrong side of a moving market with no exit. I saw this play out in March 2020 with Treasuries. The most liquid asset class on earth suddenly had a bid-ask spread of forty basis points instead of the normal two. The Fed had to step in and buy primary dealer inventory directly just to restore basic functioning.
How to measure it yourself
Don't bother with fancy models if you are just starting out. The Amihud illiquidity ratio is about as good as it gets for a quick snapshot. You take the absolute return of an asset on a given day and divide it by the dollar volume traded that day. Multiply by a thousand to make the numbers readable. Higher values mean less liquidity. It is simple enough that you can compute it in Excel in about three minutes per ticker. For intraday work, look at the roll model or use realized spreads from trade data. These require more granular data but they separate the information component from the inventory component of the spread, which matters if you are actually trading and not just reading about it. A lot of people confuse narrow spreads with deep liquidity. They are related but not the same thing. A stock can have a one-cent spread and zero volume behind it. One big order walks right through the book. I once worked with a fund that chased what looked like excellent liquidity metrics on a battery materials producer. Five cent spreads, three million average daily volume, looked like a no-brainer. They built a forty-million-dollar position over two weeks without any visible impact. Then they tried to exit during a sector rotation and the entire ask side of the book was gone. They sold at a nine percent discount to the previous close and took a hit that wiped out a quarter of the year's alpha. The liquidity was always there in the averages. It just was not persistent.
Get the Full Details

Why this matters beyond trading
Liquidity conditions affect monetary policy transmission. When financial conditions tighten through illiquidity, the Fed's balance sheet operations become more impactful but also more complicated. The traditional view assumed central banks could print money and rates would adjust smoothly. Illiquid markets break that assumption because the transmission goes through dealers, and dealers have balance sheet limits. I have seen multiple instances where rate cuts did not reach the bottom of the yield curve because the bond market was simply not absorbing the supply. The secondary effects showed up in credit spreads rather than benchmark yields, which confused a lot of analysts who only looked at the top of the curve. Corporate treasury teams feel this in their cash management. A company that sits on a large position of commercial paper or corporate bonds assumes it can roll that debt at reasonable rates. When liquidity dries up, rollover risk becomes real, and even fundamentally sound firms can face funding crises. This was visible in the 2019 repo market stress, where well-capitalized banks could not easily fund themselves overnight despite having ample collateral. The Federal Reserve ended up injecting hundreds of billions in a matter of days.
Common mistakes I see repeatedly
The first is confusing volume with liquidity. High trading volume does not guarantee you can exit a large position. It might just mean a lot of noise traders are flipping shares back and forth while institutional flow is essentially zero. Look at the composition of the volume. If most of it is retail or high-frequency churn, the real liquidity for a large order might be thinner than the headline number suggests. The second mistake is assuming cross-asset liquidity correlations are stable. In calm periods, equities, bonds, and commodities often move together in terms of liquidity conditions. During stress, they diverge unpredictably. Sometimes equities stay relatively liquid while Treasury markets seize up. Sometimes it is the other way around. I track a simple metric called the normalized order book imbalance across my main positions, and I pay more attention to when that diverges between asset classes than to any single spread number. The third is ignoring time-of-day and calendar effects. Liquidity in US equities is concentrated in the first and last hour of trading. Try to execute a sizeable block at 11:30 AM and you will pay a premium compared to the VWAP. Options markets show similar patterns with expiration days creating temporary distortions. I learned this the hard way early in my career when I scheduled a large options hedge for a Tuesday afternoon and got filled at what felt like a terrible price. Moved the execution to Monday and the cost dropped by about fifteen percent on the same strategy.
What to watch instead of what everyone else watches
Forget the basic spread numbers for a moment. Watch the cost of short placement. When it becomes expensive or impossible to borrow shares for a stock you thought was liquid, that is an early signal of underlying fragility. I keep a running list of hard-to-borrow names in my sector coverage, and when names jump onto that list, I assume liquidity is worse than the quotes suggest. Same idea with futures basis. Contango turning into backwardation in a commodity or index future often precedes a liquidity squeeze, especially in energy markets where storage constraints interact with trading activity. Another underused signal is the dispersion of trade sizes. If most trades are tiny while the volume looks healthy, actual liquidity for meaningful orders is likely thin. I use a simple histogram of trade size distribution on a daily basis for my covered universe. When the median trade size drops below one percent of the average, I flag it. It has been a reliable leading indicator for me over the years. There is no perfect measure and no substitute for knowing your own order book. If you are a small trader, market depth matters less than your ability to time entries. If you are institutional, you need to model your own market impact before you size the position. I still see funds that calculate position size based on average daily volume without accounting for the fact that only a fraction of that volume occurs at prices acceptable to them. The math is simple but the discipline is rare. Divide your target position by the realistic fills per hour at acceptable prices, and you get a timeline. Most people skip that step and wonder later why they moved the market against themselves.

Liquidity will always come back after stress, but it rarely returns to the same structure. The participants change, the order flow patterns shift, and what looked like deep liquidity before may have been sustained by a few key makers who are now gone. Reassessing your assumptions after each disruption has saved me from repeating the same mistakes across multiple cycles.