How The Philippine Clearing House Actually Moves Money Around
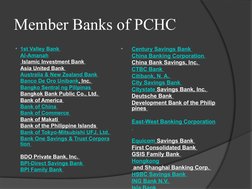
Most people in banking assume cheques just appear in the right account by magic. They don't. Every single transaction that crosses between two different banks in the Philippines goes through a clearing mechanism, and the Philippine Clearing House is what makes that happen. I have spent years watching this system handle everything from small PESONet transfers to massive RTGS payments, and there are parts of it that nobody outside operations really understands. The Philippine Clearing House operates under Bangko Sentral ng Pilipinas oversight, and it serves as the central node where all interbank transactions get reconciled. When you send money from BDO to BPI, those two institutions don't just swap cash directly. Their positions get netted out through the clearing house at the end of the business day. What remains is a settlement position that each bank owes or is owed. This matters because the BSP requires every bank to maintain a settlement account with them, and the clearing house is what determines how much flows where during end-of-day processing. I remember working through a situation where a regional cooperative bank kept getting stuck in overdraft on their settlement account simply because they were sending more through real-time channels than they had on hand. The clearing house itself was working fine. The issue was timing, not infrastructure.
How Settlement Actually Works Day To Day
The clearing happens in cycles. Early morning submissions go through one batch, afternoon submissions another. PESONet transactions settle on a near-real-time basis during the operating window, which runs roughly from early morning until mid-afternoon. Those are the ones where money appears in the recipient account within minutes. But here is what most people miss: appearing in the account and actually settling are two different things. The beneficiary bank sees the funds, but the true settlement between the two institutions happens at end of day. RTGS handles the large value transactions separately. Those move individually as they come in, not in batches. The threshold for RTGS is high enough that it mainly sees corporate payments, government disbursements, and interbank lending. If a transaction is below the RTGS threshold, it queues into the next available PESONet cycle or gets pushed to the next business day if the cut off passes.
Edge Cases That Break The System
I dealt with a recurring problem where a particular rural bank kept having transactions rejected because their BAC (Bank Administrative Code) was mapped incorrectly in the clearing house routing table. Their sort codes looked right, but the actual clearing system had them tagged under a dormant category instead of active. This meant every transfer coming into that bank would show as pending for hours, sometimes rolling over to the next day. The workaround was tedious. We had to submit a formal correction request through our relationship manager at BSP, attach the updated registry of branches, and then wait for the clearing house to push the configuration update. It took three business days. During that time, we had customers calling us constantly because their money was sitting in limbo. Another thing nobody warns you about is the weekend and holiday carryover. If you submit something right before a long weekend through PESONet and it misses the cut off, it does not sit in some holding queue over Saturday and Sunday. It rolls forward to the next banking day, and the settlement timeline extends accordingly. I learned this the hard way when a payroll disbursement I was managing got delayed because the finance team submitted it on Friday afternoon without checking the BSP schedule. The money did not hit employee accounts until Tuesday.
Get the Full Details

What Nobody Tells You About Fees And Timing
The clearing house does not charge banks directly for processing individual transactions. The cost structure works through membership fees, settlement account requirements, and the implicit cost of capital that banks carry while their funds are in transit. For the average consumer or business, what you actually pay depends on your own bank's pricing, not on the clearing house. Some banks absorb the cost. Others pass it along as a transfer fee. The amount varies wildly between institutions even for identical transaction types. If you are a business doing high volumes of interbank transfers, you can negotiate better rates by demonstrating consistent throughput. The clearing process itself is predictable enough that banks are willing to offer reduced fees for volume commitments. This is not advertised. You have to ask your relationship manager specifically about merchant or corporate transfer pricing tied to clearing house transactions.
When The Clearing House Falls Short
The system works reliably, but it has real bottlenecks. The cut off times are strict. Miss the window and your transaction waits. The settlement accounts can create liquidity traps for smaller banks that do not manage their intraday positions carefully. There have been instances where cooperative banks and rural banks faced overdrafts simply because they underestimated the timing gap between when they sent money out and when settlement actually cleared. If you need truly instant cross bank transfers that settle immediately rather than appearing pending, the current clearing infrastructure does not fully support that for all transaction types. Some newer digital payment rails are closing this gap, but they still route through the same underlying clearing mechanisms at the end of the day. The appearance of instant movement is real for the recipient, but the institutional settlement is not instant. The practical takeaway is that understanding when your money actually settles versus when it just appears available makes a difference for cash flow management. If you are running a business and relying on incoming transfers from other banks, factor in the end of day settlement reality rather than assuming the money is truly yours the moment it shows up in your dashboard. That distinction matters when you are trying to meet payroll or pay suppliers on the same day.