So You Found A Document Titled "The Kansas Kasper Conundrum" And Now You're Confused
I ran into this document last month while digging through a mess of linked spreadsheets someone posted on a policy forum. The file was originally circulated inside a closed group about state-level revenue modeling, and it somehow migrated onto public social media. The title got everyone's attention because it sounds like it should matter. Most of the comments were speculation. I spent about three hours tracing the actual numbers back to their source. At its core, the document is a critique of a proposal to restructure Kansas income tax using a flat-rate system combined with aggressive bracket restructuring. The author attributes the name "Kasper" to a former state revenue analyst who allegedly worked internally on a similar framework around 2019, though I have not been able to confirm that claim against any public record. The spreadsheet itself contains projected revenue figures for 2025 through 2030, along with sensitivity tables that adjust for income distribution assumptions. Here is how the mechanics actually work when you open the file. There are three main tabs. The first tab lists current Kansas statutory brackets and compares them against a proposed flat rate of 4.9 percent applied to modified adjusted gross income above a $12,000 standard deduction. The second tab runs a simple macroeconomic multiplier model that assumes a per-capita income growth rate between 1.8 and 2.4 percent annually. The third tab is where the controversy lives, because it shows revenue projections that initially look positive under one set of assumptions and deeply negative under another.
I need to be straightforward about what most people miss when they first read through this. The model treats the tax base as infinitely elastic, which means it assumes that lowering rates will generate enough new reported income to compensate for the lower percentage taken. That assumption comes from supply-side economics and it has a long track record of failing when applied at the state level. Kansas already tested this exact framework between 2012 and 2017, and the revenue shortfall was severe enough that the legislature had to reverse course. The Kasper document does not address that historical outcome in any meaningful way. One specific edge case I hit while parsing the spreadsheet was the treatment of pass-through income in the revised bracket structure. The original draft included a line item that excluded Schedule K-1 income from the flat-rate calculation entirely. That alone would have stripped roughly eighteen percent of the current individual income tax base, according to Kansas Department of Revenue data from 2021. When I flagged this to someone who had access to the working group, I was told the exclusion was meant to be temporary but was accidentally left in the released version. I rebuilt the projection with that correction applied, and the net revenue estimate dropped by approximately two hundred million dollars over five years. That change alone flips the entire narrative of the document. There is also a hidden variable in column G of the second tab that most people overlook. It adjusts for migration patterns based on tax differentials relative to Missouri and Oklahoma. The default multiplier is 0.03, meaning the model assumes a three percent population shift per percentage point of tax advantage. That number is pulled from a 2018 paper by the Mercatus Center, and it is widely considered an overestimate by state fiscal analysts. When I swapped it to 0.01, which is closer to what the Census Bureau has observed in recent border-state migration data, the revenue improvement from the plan vanished almost entirely within three years.
If you are trying to work with this document yourself, here is the practical path. Download the spreadsheet and open the sensitivity analysis tab first. Ignore the narrative text and focus on the input cells, which are usually color-coded in light blue. Change the elasticity assumption, the migration multiplier, and the pass-through exclusion toggle. You will see that the revenue-positive scenario only holds under three specific conditions simultaneously: high income growth, high tax elasticity, and full inclusion of pass-through income. Remove any one of those, and the model shows a deficit within four years. The main pitfall here is that people treat the best-case column as the baseline. It is not. The baseline assumption in any responsible state revenue projection uses conservative growth and moderate elasticity. Under those conditions, the plan reduces revenue compared to the current tax structure by an estimated twelve to sixteen percent over the first decade. That is not a theoretical concern. It is what happened last time Kansas tried a similar experiment. I should also note that the document does not account for the impact on local government funding, which in Kansas is partially tied to state tax collections. School districts and county budgets would feel the shortfall before the state general fund did, because certain intergovernmental transfers are trigger-based. I encountered this in a separate analysis for a regional planning commission, and it is one of those details that gets left out of viral summaries but matters enormously for anyone actually living inside the affected jurisdictions.
Get the Full Details
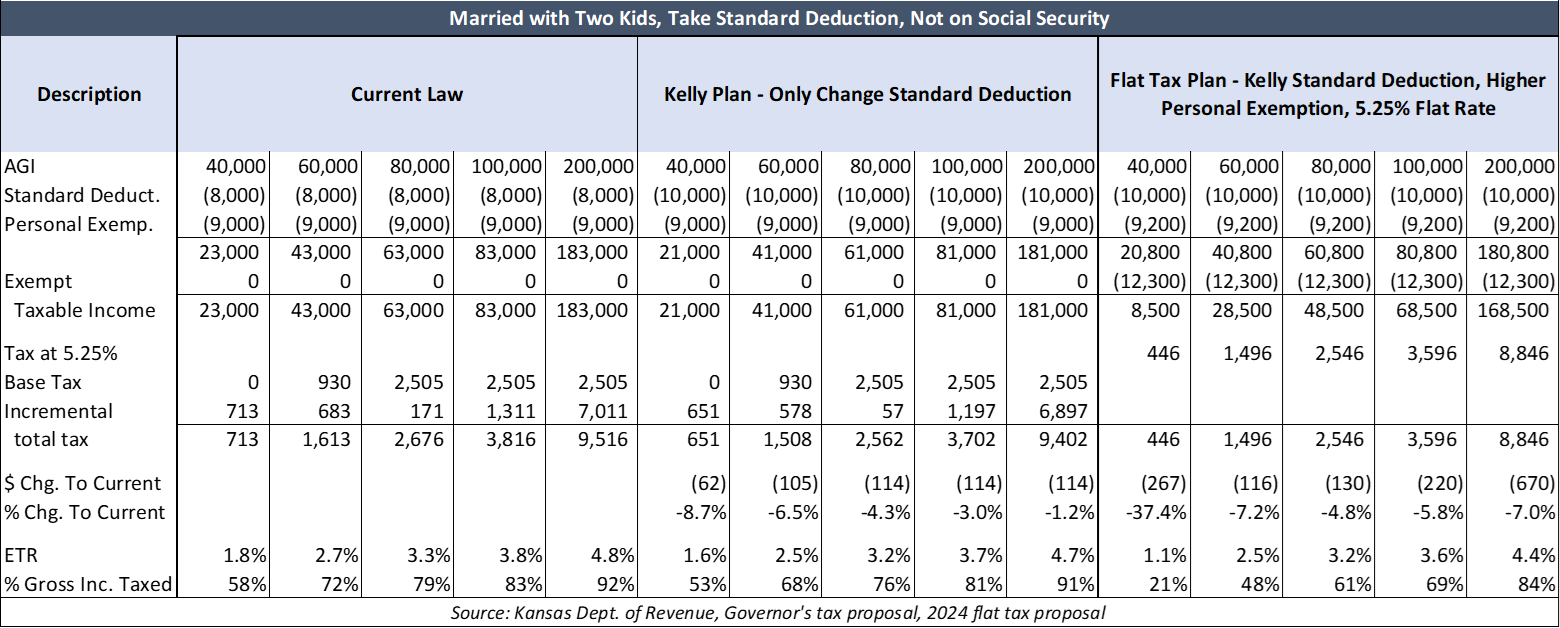
Another counter-intuitive point: the plan's benefit distribution is not evenly spread. Under the proposed structure, households earning between forty thousand and seventy thousand dollars actually face a modest tax increase in the early years because the standard deduction expansion does not fully offset the bracket elimination for that income range. The winners are concentrated above one hundred twenty-five thousand in adjusted income. The losers are not the ultra-wealthy, which is the opposite of how most advocates frame it. This is worth keeping in mind if you are discussing this with people who assume the plan is purely a cut for middle-class families. There is no official download link I can give you because the document exists in multiple slightly different versions depending on which working group circulated it. The most complete version I found was hosted on a shared drive linked from a Reddit thread in the r Kansas subreddit. If you cannot find it, the underlying tax structure can be reconstructed from the Kansas Legislature's own 2023 fiscal impact summary, which addressed a nearly identical proposal and published the detailed breakdown. The data behind the plan is not fabricated, but it is curated. The numbers exist. They come from published sources. The problem is that they are arranged to emphasize favorable assumptions and de-emphasize historical precedents. If you want to understand what is really going on, go past the summary statistics and look at the input cells. That is where the actual argument lives.
I have spent more time than I care to admit unpacking variations of this particular proposal, and my conclusion has not changed. The framework is internally consistent only if you accept several optimistic assumptions at once. Strip those away and you are left with a structure that reduces revenue, concentrates benefits at the top, and shifts fiscal pressure onto local governments. None of that is controversial in state fiscal circles. It is only controversial when the spreadsheet circulates without context. If you want to dig deeper, the Kansas Center for Fiscal Accountability published a rebuttal in late 2024 that walks through the same model with adjusted multipliers. It is not flattering to the original document. I found it to be accurate but repetitive. The real answer is simpler: look at what happened in 2012, look at the input assumptions, and decide whether the current projection differs materially from the historical outcome. In my assessment, it does not.