Understanding Yield Traps in High-Paying Funds
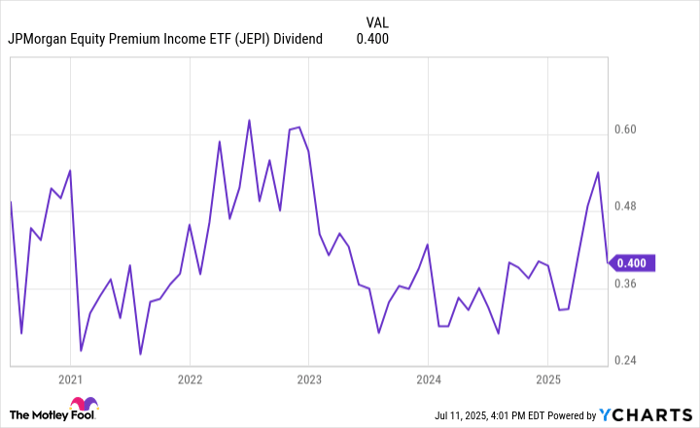
You see a fund posting a twelve percent dividend yield and your instinct is to reach for the buy button. I get it. I've watched the same thing happen on the floor more times than I care to count. The problem is that yield alone tells you almost nothing about whether the payout is sustainable or whether the fund is quietly falling apart. The Jepi Dividend Yield Mirage Why High Payouts Can Signal Distress Instead Of Value is something most retail investors walk straight into because they're looking at the headline number and nothing else. What you need to understand is what's actually generating that distribution, where the cash is coming from, and whether the fund is returning your own capital disguised as income.
The Math Behind the Mirage
Dividend yield is calculated by taking the annualized distribution and dividing it by the current share price. That is straightforward. What nobody tells you is that distributions can come from multiple sources: actual dividends from holdings, interest income, realized capital gains, return of capital, and sometimes even fund-level borrowing to maintain payouts during drawdowns. When a fund's underlying assets are depreciating but the manager keeps paying the same distribution, the yield mathematically has to go up because the share price is dropping. You end up staring at a higher percentage yield while the actual dollar value you own is shrinking. That is the core mechanism of the mirage. I worked through a situation a few years back with a high-yield closed-end fund that was reporting a fourteen percent distribution yield. It looked incredible on paper. When I pulled the 10-K filings and traced the distribution source breakdown, roughly sixty percent of the payout was coming from return of capital. The fund was literally handing investors back their own money and calling it income. By the time that became clear, the market had already repriced the share forty percent below its asset base, but the yield headline stayed elevated because the price continued falling.
What to Check Before You Buy
Start with the distribution source breakdown. Any legitimate fund filing will show you how much of each distribution is ordinary income, capital gains, and return of capital. If return of capital exceeds twenty-five percent of total distributions over a rolling twelve-month period, you are dealing with a serious sustainability problem. That should be your first red flag before anything else. Look at the payout ratio relative to net investment income, not just the yield. A fund generating six percent in actual earnings from its portfolio but distributing ten percent is running a payout ratio above one hundred sixty percent. That gap has to come from somewhere, usually existing capital or debt. Over time it cannot hold. The discount or premium to net asset value matters more than most people realize. A fund trading at a steep discount might look attractive, but if that discount is widening while distributions remain elevated, the market is pricing in distribution cuts that have not happened yet. I have seen this play out repeatedly. The fund holds the yield for six to eight months after the cut becomes inevitable, and investors who bought based on yield alone take a double hit from both the distribution reduction and the discount collapse.
Get the Full Details

Real Indicators That Actually Predict Cuts
Track the fund's leverage ratio and borrowing costs. When a fund relies heavily on margin debt to finance distributions, rising interest rates compress the spread between what the fund earns on its assets and what it pays on borrowing. Once that spread turns negative or approaches zero, the distribution becomes mathematically unsustainable unless the manager decides to cut it. This happened clearly in late twenty twenty two across several high-yield funds when short-term rates moved faster than long-duration asset yields could adjust. Monitor the composition of the portfolio over time. If a fund meant for income generation starts selling its higher-quality dividend payers to raise cash, that is a distribution stress signal. I keep a simple spreadsheet tracking quarterly turnover rates and sector rotation patterns across any fund I hold. When turnover spikes above sixty percent while the distribution remains flat, something is giving. Usually the portfolio quality, occasionally the distribution itself. Check the frequency of distribution adjustments. Funds that have maintained identical per-share distributions through multiple market cycles without ever adjusting for earned income changes are typically managing expectations rather than managing sustainability. A real cut announcement will damage investor sentiment and trigger redemptions or price pressure, so managers delay. The longer they delay, the larger the eventual cut tends to be.
A Practical Workflow I Use
I pull the latest prospectus supplement and the most recent annual report. I calculate the trailing twelve-month yield based on actual distributions paid, not the annualized run rate the fund advertises. Then I pull the distribution source tables and compute the return-of-capital percentage. If it is above twenty-five percent, I move the fund to a watchlist rather than a buy list immediately. Next I review the balance sheet for leverage. I want to see total assets minus total borrowings to get a sense of net asset coverage. I then check the investment grade versus high yield split in the portfolio. Funds leaning heavily into below investment grade debt are more vulnerable to economic contractions, and their distributions tend to be less stable than comparable funds holding investment grade paper with similar yields. This whole process usually takes me about twenty minutes per fund. The initial screening where I filter out funds with excessive return of capital and payout ratios above one hundred ten percent takes roughly five minutes if I have my spreadsheet templates ready. Most funds get eliminated before I ever dig deeper.
When High Yield Is Actually Legitimate
Not every high distribution is a trap. Some funds earn their yields honestly. Treasury and municipal bond funds with elevated yields during rising rate environments are often generating real income, not returning capital. Certain infrastructure and real estate funds with contracted revenue streams can sustain distributions that look high relative to equities but are backed by predictable cash flows. The key difference is always whether the distribution exceeds earned income consistently over multiple years. If a fund shows a payout ratio consistently below eighty-five percent over five years and maintains that discipline through at least one major market correction, the yield is far more likely to be structurally sound. That track record is easier to verify than any single year of elevated distributions. There is no shortcut that replaces reading the actual fund documentation. Yield screening tools will show you the headline number and nothing more. The numbers that matter are buried in the footnotes and schedule of investments. The funds that survive distribution cuts are the ones where the income is real, the leverage is modest, and the manager has shown willingness to adjust payouts when circumstances change rather than pretending nothing is happening.