Why Your Bank Statement Looks Like Gibberish
Most people don't think about payment descriptors until they see something unfamiliar on their monthly statement and panic. "JCPENNEYCOMPAYBILL" isn't a scam. It's just a badly formatted merchant descriptor. I spent about three years in payments operations and I still find myself explaining this to family members at Thanksgiving. Payment processing is not a single thing. When you tap your card or click buy, your transaction bounces through a series of actors before money actually moves. The descriptor you see is the artifact left behind by whichever processor, gateway, or aggregator ultimately settled the charge. Understanding that chain is the difference between spotting actual fraud and spending twenty minutes on hold with customer service.
The Jcpenneycompaybill Enigma Dissecting The Digital Payment Ecosystem And Its Implications For Modern Commerce
The term itself is not a branded product or a real program. It is what happens when you mash a merchant name, a descriptor format, and the phrase "company bill" together without regard for spacing or character limits. Bank statement lines often cap out at 22 to 25 characters. Everything beyond that gets truncated, squished, or converted into a cryptic string. That is the core enigma. The digital payment ecosystem does not present information in a way designed for human readability. It presents information in a way designed for machine routing. I have seen merchants with perfectly professional websites end up with descriptors like "WC*SQUARE*1234MAINST" because the payment gateway injects location data, processor codes, and internal routing flags into the descriptor field. That is normal. It is also deeply annoying for anyone reconciling personal accounts or running expense reports.
How a Transaction Actually Gets Described
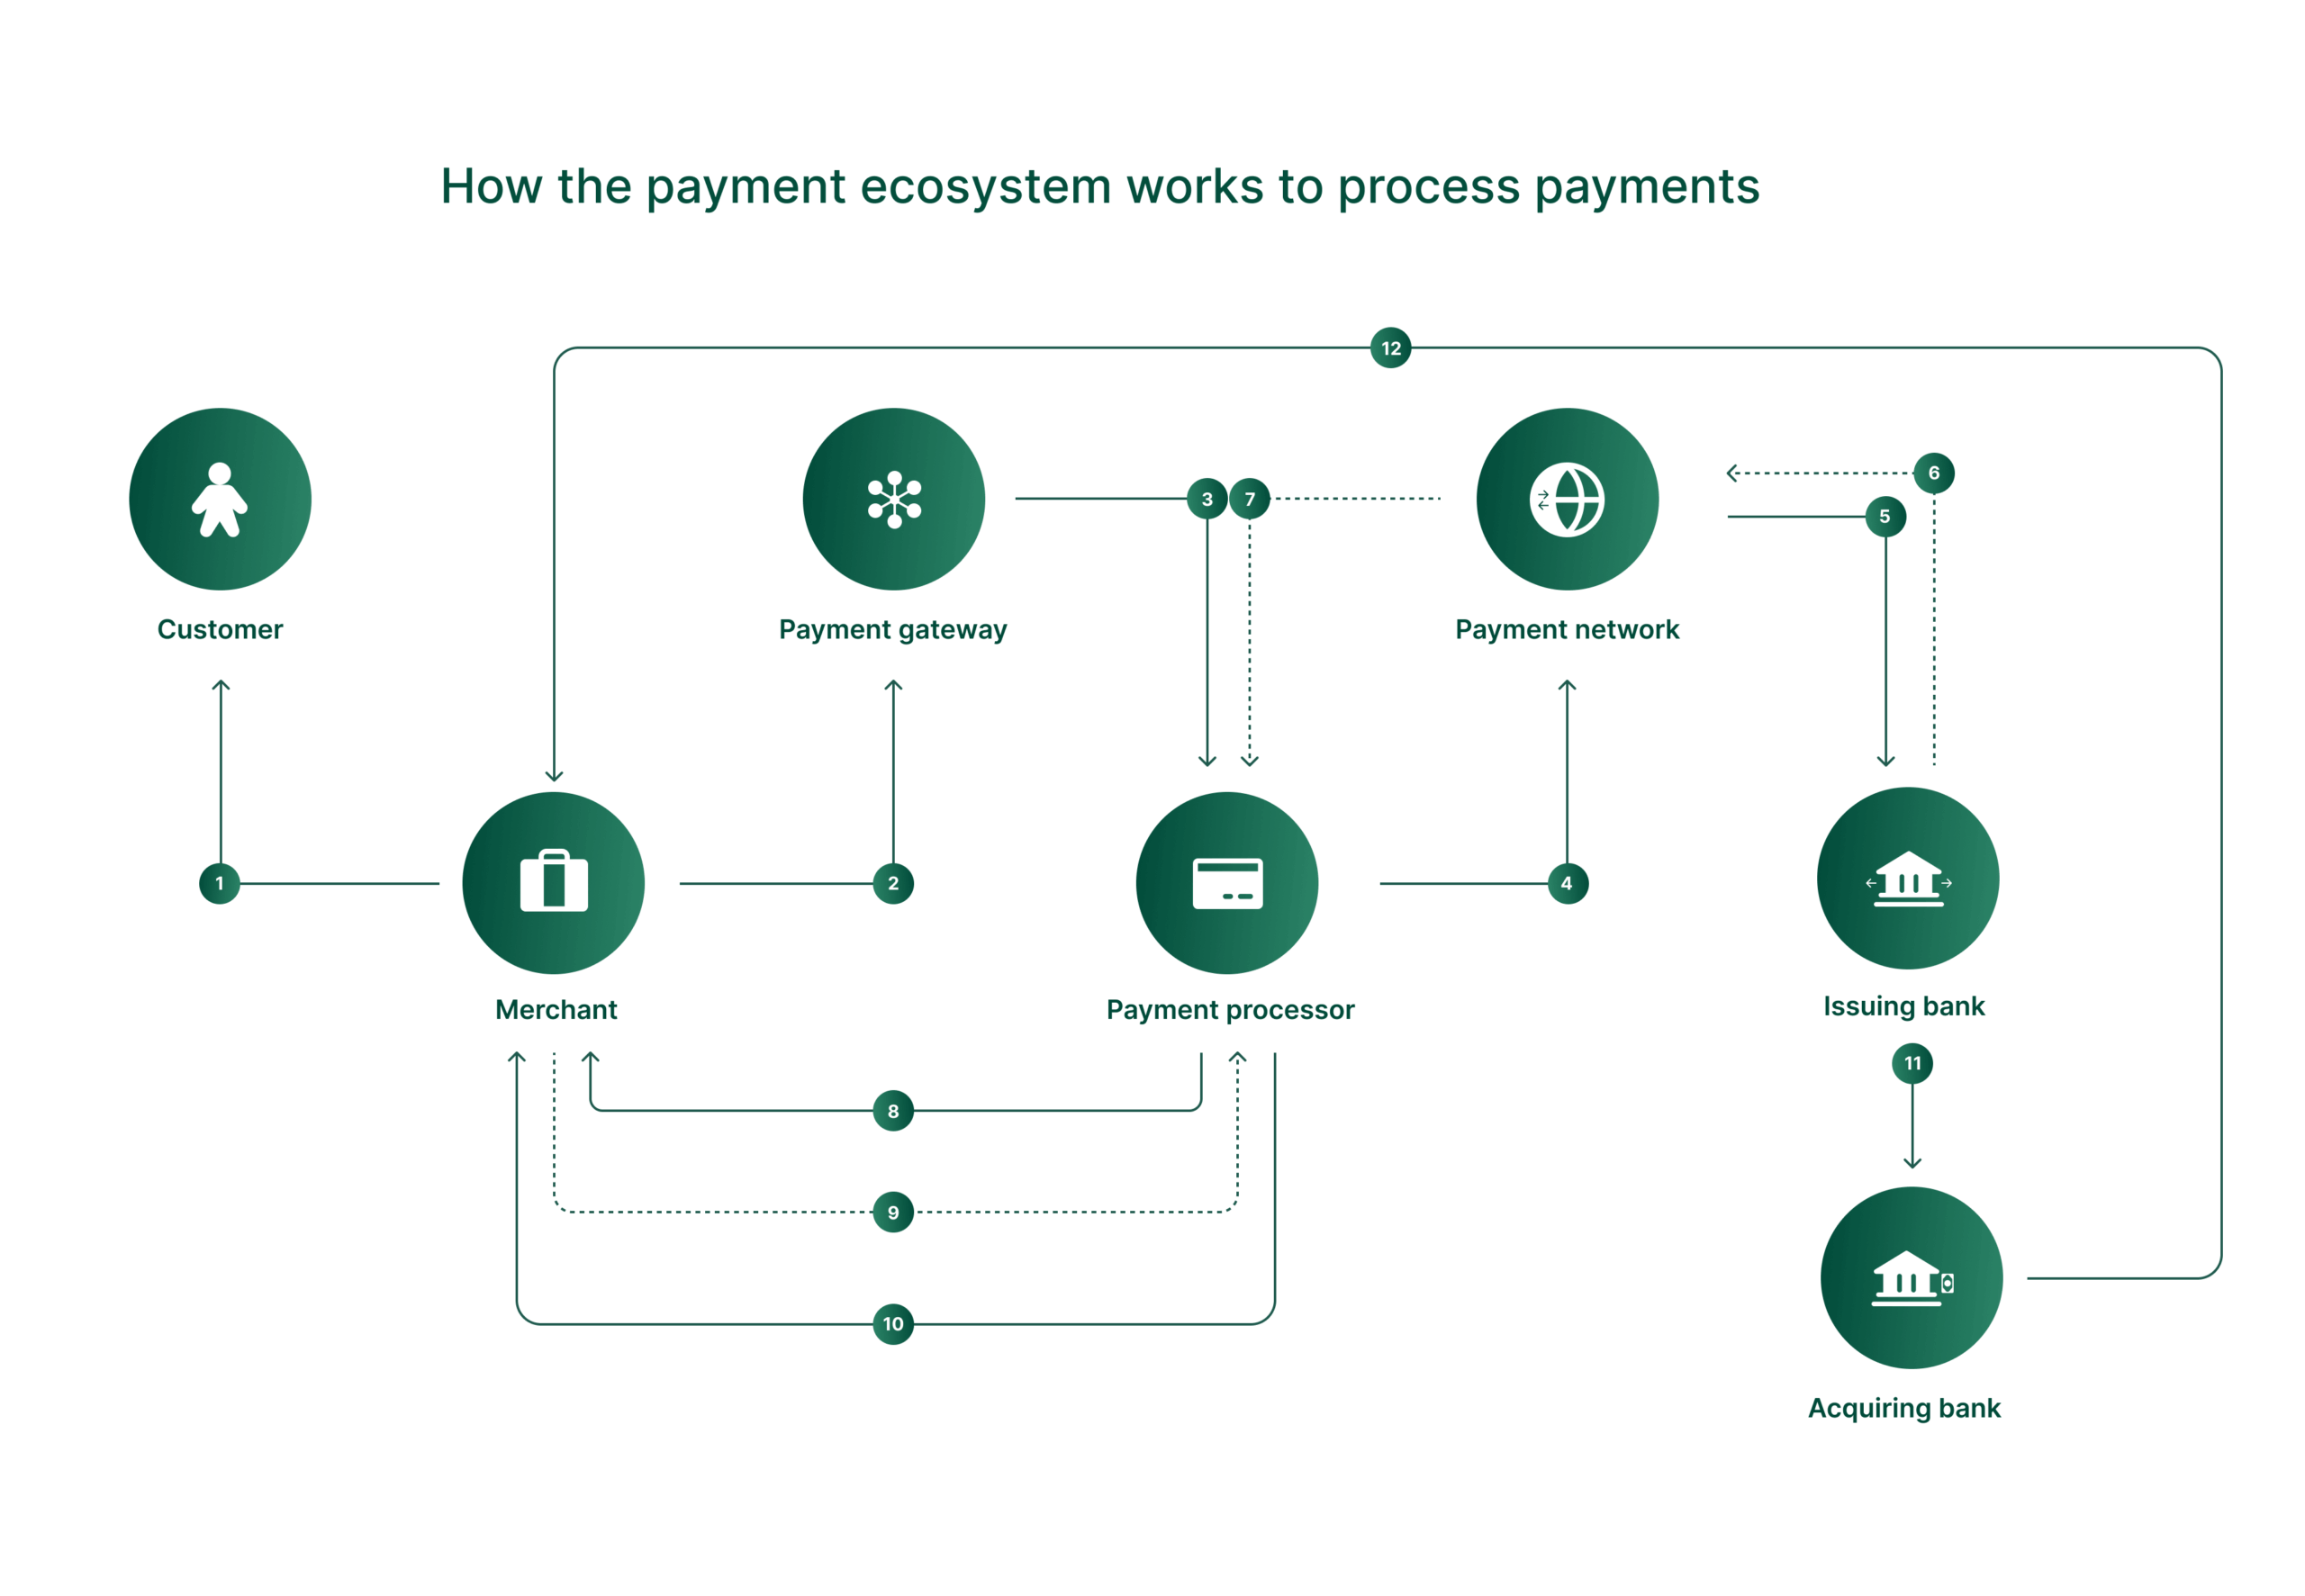
Let me walk through what happens after you complete a purchase, because the answer to why your statement reads like a secret code lives in the mechanics. Step one is authorization. Your card network routes the request to the issuing bank. The issuer approves or declines based on available funds, fraud rules, and merchant category codes. At this point no descriptor exists yet. There is only an authorization code and a hold on your funds. Step two is settlement. The merchant batches approved transactions and sends them to their acquiring bank or payment processor. This is where the descriptor gets assigned. The acquirer uses whatever descriptor the merchant configured during onboarding, combined with dynamic descriptor rules set by the processor. If the merchant chose a short, generic name like "JCPenney", your statement might show "JCPENNEY STORE 142". If the merchant uses a third-party payment aggregator, the aggregator's legal entity name often takes priority. That is usually where the long string starts.
Get the Full Details
I learned this the hard way when my own credit card started showing a charge labeled something like "PAYMENT AGGREGATOR LLC TX#8472910". I was genuinely worried about unauthorized activity. It turned out I had bought shoes through a merchant that processed payments via a mid-sized aggregator. The aggregator's legal name was the descriptor. I called the card issuer, confirmed the transaction matched my receipt, and moved on. A simple reconciliation check would have saved me a phone call.
What the Descriptor Field Actually Contains
Descriptors are governed by network rules from Visa, Mastercard, American Express, and Discover. Those rules specify character limits, allowed characters, and whether dynamic updates are permitted. Most processors use a structure that looks like this: MERCHANT NAME | LOCATION OR ID | ROUTING INFORMATION | TRANSACTION REFERENCE Only the first segment is meant for human consumption. The rest exists for dispute resolution, batch matching, and fraud detection. When you see a wall of capital letters and numbers, you are looking at the machine layer of the payment system. It is not broken. It is functioning exactly as designed.
Here is a detail most people miss: the same merchant can produce completely different descriptors depending on how you pay. A JCPenney purchase made in-store with a physical card will show a store-specific descriptor. The same purchase made through the JCPenney app using an Apple Pay token will likely show the token handler or a different aggregator name. A purchase made with a JCPenney gift card will show yet another pattern. The merchant is the same. The descriptor chain is not.

Common Pitfalls That Get People Into Trouble
I see the same mistakes repeatedly, and they almost always lead to unnecessary disputes or missed fraudulent charges. The first mistake is assuming every unusual descriptor is fraud. The second is assuming every familiar descriptor is safe. Both are wrong. The correct approach is verification, not assumption. If you see a charge you do not recognize, cross-reference the date and amount with your receipts before calling the issuer. Check your email for order confirmations. Search for the merchant name, not the descriptor. A lot of aggregators use legal entity names that have nothing to do with the brand you actually bought from. I once spent an hour investigating a charge labeled "CLOUDPayments Inc" before realizing I had subscribed to a streaming service that uses that processor. The charge was legitimate. The descriptor was just honest about who actually moved the money.
Another pitfall is confusing a pending transaction with a posted one. Pending descriptors are often less specific. A $49.99 charge might appear first as "ON HOLD" or as the merchant's generic placeholder, then resolve to the full descriptor once settlement completes. Do not dispute something until it posts. Most issuers will tell you the same thing.
What This Means for Modern Commerce
The way descriptors work reveals something important about how the payment ecosystem has evolved. Merchants do not fully control what you see on your statement. Their processors do. Big retailers with dedicated acquiring relationships often negotiate cleaner descriptors. Smaller merchants and marketplaces frequently surrender descriptor control to whichever processor offers the fastest onboarding or lowest integration cost. That is a tradeoff, not a conspiracy. For consumers, the implication is that statement literacy is now a practical skill. You should be able to look at a charge and determine whether it is legitimate without immediately assuming the worst. For merchants, the implication is that descriptor quality affects customer trust and dispute rates. Poorly configured descriptors generate more support tickets and more friendly fraud claims. Issuers pay attention to that. Some will downgrade a merchant's processing tier if descriptor complaints exceed thresholds. I worked with a mid-tier retailer who was losing about two percent of their authorization rate because their descriptor format triggered risk flags at several major issuers. The fix was not technical. It was administrative. They updated their descriptor naming convention to include their recognizable brand name first, added a customer service phone number within the allowed character range, and registered a Dynamic Merchant Descriptor with the networks. Their dispute rate dropped noticeably within sixty days. It was a small change that exposed how much of the payment experience is invisible infrastructure.

How to Reconcile Confusing Charges
Keep it simple. When a descriptor does not match your expectation, follow this sequence. First, check your transaction history across all accounts. Often the charge appears under a different label in your payment app, digital wallet, or subscription manager. Second, search for the merchant by brand name, not by the exact string on your statement. Third, if you still cannot identify it, call the issuer and ask for the Merchant Category Code and the full terminal or reference ID. Those details reveal more than the descriptor ever will. MCC codes tell you the business type. Terminal IDs can sometimes be cross-referenced with your own records if you shop at chains with numbered locations. Do not file a dispute unless you have reason to believe the charge is unauthorized or incorrect. Disputes hurt you more than they hurt merchants in many cases. Issuers may temporarily credit you, but the investigation process is real, and merchants can fight back with transaction evidence. If the charge is legitimate but confusingly labeled, a simple note in your banking app or a comment like "JCPenney order confirmed via email" is enough to prevent future confusion.
Where the System Falls Short
Descriptor standards have not kept pace with how commerce actually works now. Subscription services, buy-now-pay-later arrangements, marketplaces, and digital goods blur the line between who the merchant is and who processes the payment. The result is that a single purchase can generate multiple entries on your statement, each with a different descriptor, because each stage of the transaction routes through a different party. Some newer payment methods partially address this. Tokenization replaces card details with device-specific tokens, which changes the descriptor pattern entirely. Open banking and account-to-account payments create their own descriptor formats. None of these improvements have made statements easier to read. They have just changed the shape of the confusion. If you want cleaner statements, the most effective action is to use direct payment methods where possible. Buying directly from a merchant with their own acquired payment stack usually produces more consistent descriptors than buying through a third-party marketplace. It is not a perfect solution. Marketplaces exist for convenience, and convenience has a cost.
The bottom line is that payment descriptors are a routing artifact, not a marketing choice. They reflect the structure of the backend, not the front-facing brand. Once you understand that, most of the anxiety around unfamiliar statement lines disappears. The ecosystem is opaque by design. That does not mean it is hostile. It just means you need to learn the language it speaks.