What the card actually gives you before you apply
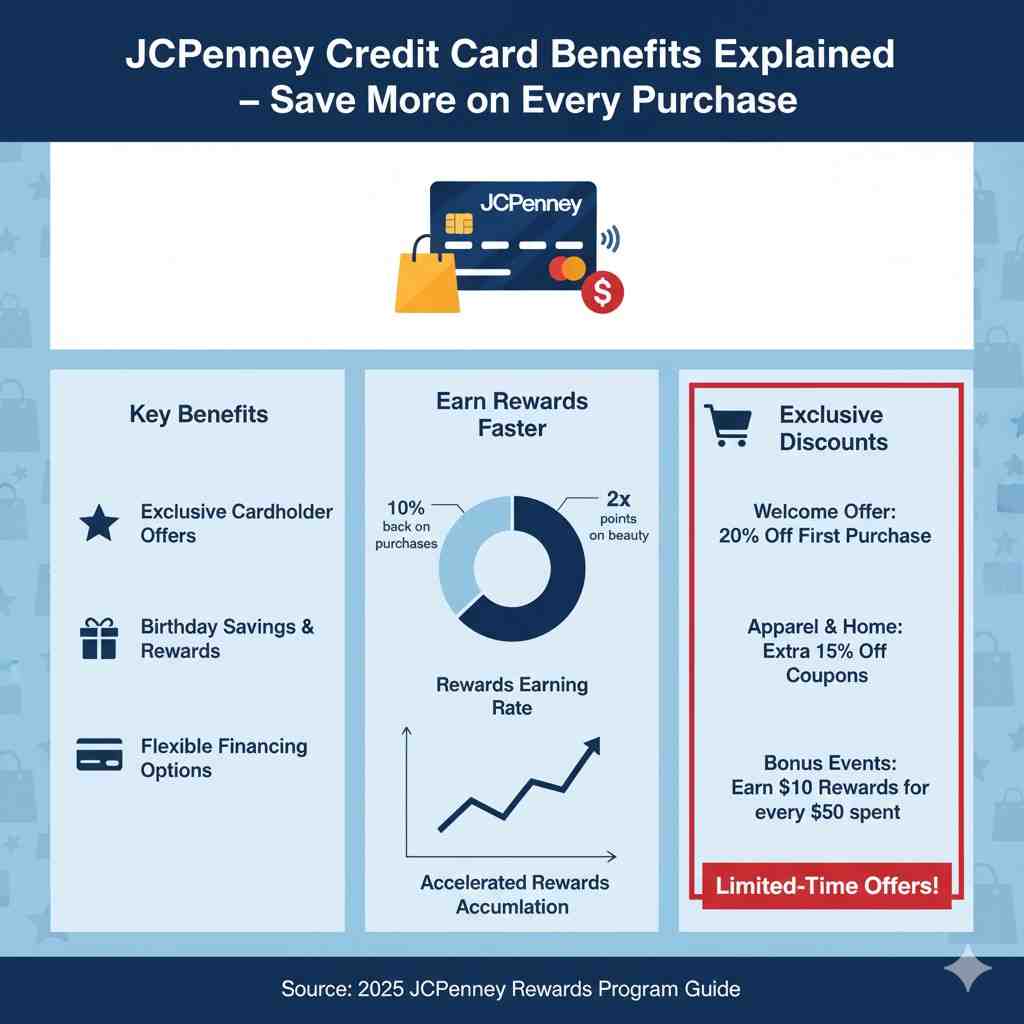
The JCPenney store card offers two main products: the red card and the MasterCard. The red card only works at JCPenney and its affiliates. The MasterCard works everywhere Visa is accepted. Both cards earn 5 percent rewards on every purchase when you're an approved cardholder, which is notably higher than most general-purpose cards. You also get an immediate 30 percent discount on your first full-price purchase of $100 or more, plus periodic promotional financing offers that can run 60 months for qualifying purchases. That headline sounds like something a PR team would push, but the mechanics are straightforward enough that you can see the math without the spin. The card becomes strategic when you understand how JCPenney structures its pricing. The store runs frequent sales, but the discounts usually stack on top of the reward rate rather than replacing it. If you buy a $200 item on a 40 percent off promotion and pay with the store card, you get the discounted price plus 5 percent back in rewards. That changes the effective cost significantly compared to using a debit card or a generic rewards card. I've seen people treat the card as if the rewards alone make it worth opening. They aren't wrong, but they're missing the part that actually matters. The real leverage comes from timing your purchases around JCPenney's sale calendar. The store does doorbusters, holiday promotions, and category-specific events regularly. A 40 percent off clothing event combined with 5 percent card rewards and coupon stacking during checkout is where the math gets interesting. The rewards compound on the already-discounted price, not the sticker price, which most beginners miss.
Here is a practical example I ran through last fall. A jacket listed at $150 went on a 30 percent off promotion. I applied a 20 percent off coupon at checkout that stacked with the sale price, bringing the total to $105. Paying with the store card added another 5 percent back, so the net cost after rewards dropped to roughly $99.75. On the same jacket, a generic 2 percent cashback card would have only brought the cost to $136 after rewards. The gap is not trivial over a few hundred dollars in a shopping trip.
How to apply and what happens immediately after approval
You can apply online or in-store. Online approval is usually instant if you qualify, and the virtual card number is available within minutes through the JCPenney app. In-store approval takes longer because the representative has to run a manual authorization, and some branches do not have the system set up for immediate card issuance. If you apply in-store and get approved, ask them to activate the card before you leave so you can use it on your current transaction. Otherwise you might walk out with an approved application but no way to use the benefits until the physical card arrives in 7 to 10 business days. The minimum credit score most people need is around 640 for the store card and closer to 670 for the MasterCard. The actual pull depends on your credit profile. JCPenney uses a soft inquiry to show your estimated terms, then a hard inquiry upon formal application. The hard inquiry can drop your score by a few points temporarily. If you are mid-process on a mortgage or car loan, do not apply during that window. I learned that the hard way when a hard pull for the store card slightly lowered my score right before a mortgage application, and the lender noticed the extra inquiry on the credit report. It cost me an extra 0.125 percent on my rate. Minor, but unnecessary if you plan ahead.
Get the Full Details
Reading the rewards structure without the marketing noise
The 5 percent rewards are not flat across every transaction type. JCPenney classifies certain purchases differently. Gift card purchases, balance transfers, cash advances, and returned merchandise do not earn rewards. This is standard but easy to overlook if you assume the percentage applies universally. You also need to understand the rewards expiration policy. Unused rewards typically expire 12 months after they are posted, so leaving a small balance of rewards unspent for too long means you lose money. I once had about $18 in rewards sit untouched for 14 months because I forgot about the card. When I checked again, it was gone. Set a reminder or spend it every six months. Another nuance is how the 30 percent first-purchase discount interacts with the rewards. The discount applies to the purchase amount, and the 5 percent rewards calculate on the final charged amount after all coupons and promotions are applied. Some people try to game this by buying a cheap item to trigger the first-purchase discount and then switching to the card for bigger purchases, but the program rules tie the 30 percent discount to your first transaction specifically. You cannot split it across multiple orders. Once you use it, it is gone.
Promotional financing that is worth considering
JCPenney occasionally offers deferred interest or zero-interest financing on purchases above a certain threshold, sometimes up to 60 months. This is where the card becomes a legitimate financial tool if used correctly. If you put a $1,000 appliance purchase on the card with 60 months at zero percent and pay it off in full before the period ends, you save whatever interest you would have paid on a regular credit card. The catch is the deferred interest clause. If you miss a single payment or carry a balance beyond the promotional window, the store can retroactively charge interest on the entire original purchase amount at the card's standard APR, which is typically high. I ran into this exact trap a few years ago. I took a 36-month financing offer on a bed frame that cost $800. I paid on time for 30 months, then had a brief cash shortage and missed one payment by three days. When I got the statement, the deferred interest kicked in at 29.99 percent retroactively on the full $800. I ended up paying an additional $360 in interest. That mistake taught me to set up autopay for the minimum payment at the very least before accepting any promotional financing. Autopay prevents accidental late payments and protects you from retroactive interest penalties.
Edge cases and what usually goes wrong
One problem I encountered frequently involves returns. If you return an item that was purchased with the store card, the rewards are reversed and deducted from your account. This sounds obvious, but people often forget that the rewards were never "theirs" until the return window closes. If you buy an item on sale, earn the rewards, then return it after the reward posting date, you will see the rewards disappear and the statement adjust accordingly. There is no way around this. The system recalculates based on the final completed transaction. Another edge case involves coupon stacking at checkout. JCPenney allows one manufacturer coupon per item and one store coupon per transaction, but the system sometimes rejects the combination if the total discount exceeds 70 percent of the original price. I have had this happen twice when trying to combine a 50 percent off clearance tag with a 20 percent off store coupon. The POS system blocked the coupon application entirely. The workaround was to split the purchase into two transactions, one per item category, which let both coupons apply separately. It is annoying but effective.

When the card is not the right choice
There are scenarios where the JCPenney card makes financial sense to avoid. If you have a history of carrying balances month to month, the high APR makes the card expensive regardless of the 5 percent rewards. The rewards will never offset the interest charges. In that case, a standard cashback card with a lower APR and broader acceptance is better. The same applies if you rarely shop at JCPenney. The card's value is concentrated in its ecosystem. Outside of JCPenney, the MasterCard version earns the same 5 percent, which is decent, but the red card is useless anywhere else. Some people also open the card solely for the first-purchase discount and close it immediately after. This is not recommended. A closed account stays on your credit report for up to 10 years, and closing it can lower your available credit ratio, which affects your score. If you open the card, keep it open even if you use it infrequently. The annual fee is zero, so there is no cost to maintaining it. Just set a calendar reminder to check your rewards balance every few months and use them before they expire.
A practical workflow for maximum value
Here is how I approach this now. First, I check the JCPenney sale calendar before making any large purchase. I note the current promotion, the applicable coupons, and the expected rewards calculation. Second, I add the items to my cart and apply the best stacking combination, watching for the 70 percent discount cap issue I mentioned. Third, I pay with the store card to lock in the 5 percent rewards. Fourth, I schedule autopay for the minimum payment to avoid any late fees or deferred interest triggers. Fifth, I track the rewards balance monthly and redeem it on the next shopping trip or for gift cards if I am not planning a visit soon. This routine takes about 10 minutes per purchase cycle. It is not glamorous, but it consistently saves 10 to 15 percent compared to shopping without the card. That might not sound like much, but on a $500 grocery or household purchase during a promotion, it adds up to $50 to $75 in realized savings. Over a year of regular shopping, that is the kind of return most generic rewards cards cannot match without requiring rotating category selections or signing up for multiple programs.
The reality about the JCPenney ecosystem
The card is a tool, not a solution. It works well inside the JCPenney ecosystem, which is narrow and seasonal. The ecosystem itself has shrunk in recent years as the retailer has consolidated stores and reduced inventory breadth. That means the card's value depends partly on whether JCPenney remains a viable shopping destination for your needs. If you live near a store and shop there regularly, the card is worth the application. If you rely on online-only shopping and compare prices across multiple retailers, the same card is less compelling because the discounts may not beat what other stores offer without a card. The core lesson is simple enough that most people skip it. Read the terms around promotional financing carefully. Never accept a deferred interest offer without autopay set up. Understand that rewards reverse on returns. Check the reward expiration dates. Use the card only when the math works in your favor, and walk away from the application if carrying a balance is likely. These are not complicated rules. They are just the ones most shoppers ignore until they become expensive mistakes.