How to actually track iron ore pricing without losing your mind
I spend most of my week pulling data from Singapore Exchange, Shanghai Futures Exchange, and various steel index providers. The iron ore market runs on a mix of benchmark contracts, spot calculations, and a lot of behind-the-scenes negotiation that never makes the public record. If you're trying to make sense of price movements, you're going to run into some messy territory pretty quickly. Iron ore price indices generally fall into two camps. The benchmark-driven type, which is what the major steel mills and trading houses use for their annual contracts. That's the 62% Fe CFR China price that comes out of sources like S&P Global Platts, Argus, and Fastmarkets. Then you have the derivatives-side pricing from futures exchanges, which can drift pretty far from the physical market depending on basis conditions. The indices themselves are calculated using daily bids and offers from panelists. The methodology varies by provider, but most use a trim-mean approach where the highest and lowest quotes get discarded before averaging. The problem is that not every panelist actually trades the volumes that move the market. Some of the bigger steel producers and trading houses don't participate in the index panels at all, which means the published numbers can lag behind what's actually happening in the market.
I ran into this exact issue back in early 2024 when the 62% Fe price was spiking on the futures exchange but the spot index publications were reporting values that felt disconnected from what port operators in northern China were actually seeing. The workaround was straightforward but not obvious. I started pulling live tender data from the major port terminals and cross-referencing it with customs import statistics. When the index diverged from the physical tender spread by more than three dollars, I knew something was off and adjusted my positioning accordingly. The tender data angle is useful because it shows what buyers and sellers are actually committing to, not what they're quoting. Index methodology only captures the panelist submissions. Real transaction prices in the spot market often sit somewhere between the high bid and the low ask, and the spread itself tells you about liquidity conditions. Wide spreads during volatile periods are a reliable signal that the published index number is going to be less useful for decision-making. For people who need daily updates without constant manual checking, there are a few data providers worth looking at. S&P Global Commodity Insights publishes daily assessment reports. Fastmarkets gives you their MRPL index with the same daily cadence. For free data that's still decent quality, the Chinese futures exchange website posts settlement prices and volume in real time, and you can get a rough sense of physical demand through the quarterly iron ore index reports from SteelMetals and other industry trackers.
Here's something most beginners miss about reading these indices. The 62% Fe number you see in headlines is only one point on the pricing curve. The actual steelmaking cost depends heavily on the grade mix you're working with. Low-grade ores like 58% Fe pellets trade at a different premium or discount to the benchmark, and those grade differentials shift based on blast furnace feed requirements. During the 2023 quality tightening period, the 58% to 62% differential widened to nearly eight dollars per tonne because mills were forced to buy higher-grade material to maintain throughput. Anyone watching only the benchmark number would have had no idea that was happening. The second thing people routinely overlook is that China's port inventory levels create a mechanical floor and ceiling on prices that has nothing to do with supply and demand fundamentals. When inventories at the four major ports drop below 90 million tonnes, mills tend to restock aggressively, which pushes prices up regardless of what the broader market is doing. Above 140 million tonnes, the restocking impulse fades and prices soften even if production stays steady. I track this inventory metric alongside the index publications because it gives you a timing signal that the pricing numbers alone don't provide. Another practical issue is that index methodologies have been getting more scrutiny over the years. After the 2010s benchmark disputes between Chinese steel mills and the big miners, several new indices emerged specifically to give Asian buyers more pricing influence. Fastmarkets BME, for example, shifted toward more transaction-based assessments rather than purely opinion-based quotes. The trade-off is that transaction-based indices require more verified trade data to publish, which means they can be slower to reflect sudden market moves during illiquid periods. You're generally better off using opinion-based indices for direction and transaction-based ones for confirmation.
Get the Full Details

If you want to build your own tracking system without paying for expensive terminals, start with a spreadsheet that pulls three data points daily: the S&P Global 62% Fe CFR China assessment, the DCE iron ore futures settlement price, and the Chinese port inventory figure from Xinhua or the National Bureau of Statistics. Update it once a week for about twenty minutes and you'll start seeing patterns that don't show up in any single publication. The basis between futures and spot, the inventory trend line, and the grade differential movement will tell you more than any individual price number. Downloadable resources are limited because the best data lives behind paywalls. S&P Global's preliminary research notes sometimes appear on their public website. The Shanghai Futures Exchange publishes historical settlement data that you can scrape directly. Some university databases and commodity research firms also make older index datasets available for academic or internal use. Beyond that, you're mostly building your own dataset from public sources, which is where the weekly twenty-minute maintenance routine pays off over time. The biggest limitation you'll run into is that indices measure past pricing behavior. They're not forecasting tools. During the demand shock periods when steelmill production shut down unexpectedly, the indices kept publishing numbers based on panelist opinions that had already become irrelevant within hours. I've seen traders lose money waiting for an index to "catch up" to reality instead of reacting to the physical market signals that were already visible. The lesson is that indices are useful for benchmarking and contract settlement, not for timing entries or exits. If you need forward-looking signals, you have to layer in order flow data, mill operating rate reports, and shipping vessel arrival forecasts separately.
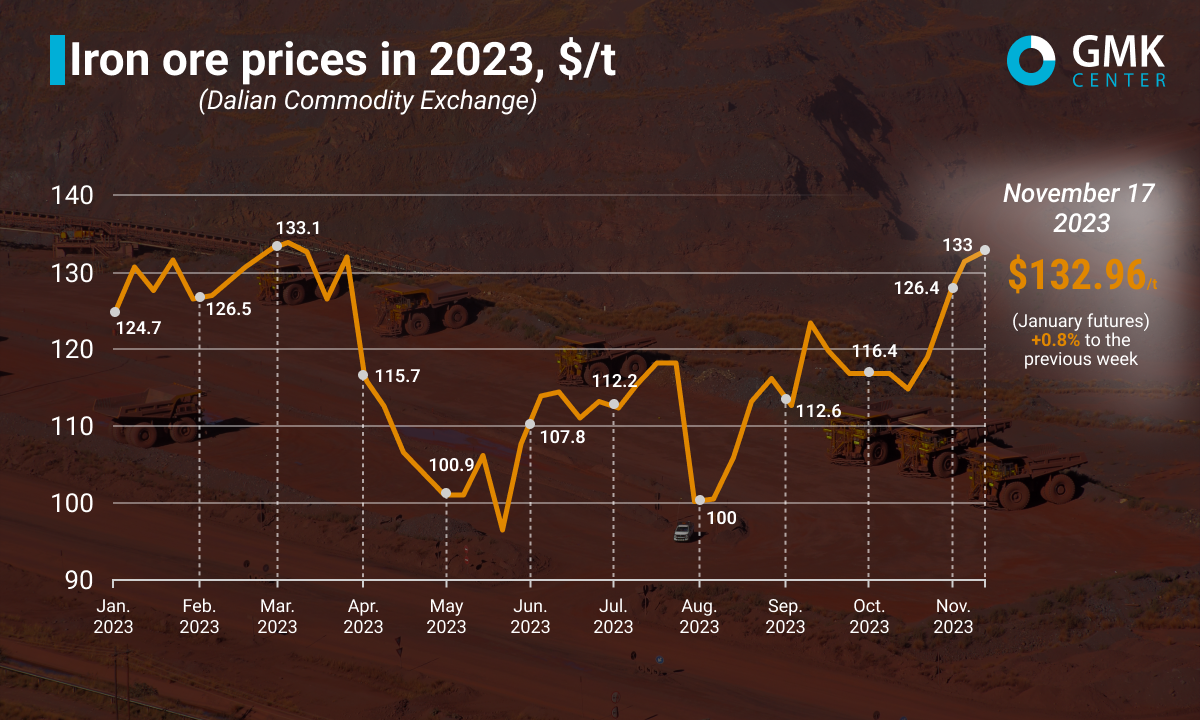
Also worth noting is that the index publications can be manipulated in thin market conditions. I witnessed a situation where a single large buyer placed a small physical order at an inflated price right before the daily cut-off window. The panelist that submitted that transaction as their assessment price pulled the entire index up by two dollars. The correction came the next day, but anyone trading on the published number lost money. This isn't theoretical. It happened during a low-volume summer period in 2023. The takeaway is pretty simple. Use the indices for what they're designed for, which is establishing reference prices for contracts and settlements. Don't treat them as real-time trading signals. Cross-reference them with physical market data. Track the grade differentials and inventory levels. Build your own tracking system with free sources and check it weekly. And remember that the most accurate picture of iron ore pricing comes from combining multiple data streams, not from trusting any single published number.