Understanding The Invisible Weight
Financial burden isn't something you can see or hold. It sits in the gaps between what you owe and what you have coming in. Most people feel it without knowing exactly what it is. They just know the money disappears and something replaces it every month. Here is how I actually define it: your financial burden equals your total monthly debt obligations divided by your take-home pay, expressed as a percentage, plus the mental load of any recurring expenses you cannot currently eliminate. That mental load piece matters because it is usually what pushes people from stressed into overwhelmed territory. A 40% debt-to-income ratio feels heavy. A 40% ratio combined with a $400 monthly car payment that is eating into your ability to save for an emergency fund? That compounds quickly in a way most calculators don't capture. I ran into a specific problem a few years ago that most personal finance guides skip over entirely. A client had a solid debt-to-income ratio of about 32%, which looked fine on paper. But they also had a $2,100 monthly medical bill tied to a chronic condition that was expected to continue indefinitely. Standard debt ratios classified that as a medical expense, not a debt obligation. When I manually folded it into their burden calculation, the real number jumped to nearly 58%. That single adjustment completely changed the strategy we built around their finances. Without it, any repayment plan would have been built on false assumptions.
The workaround I used was straightforward. I created a separate column in their tracking spreadsheet labeled "non-discretionary recurring obligations" that captured things like insurance premiums, mandatory medical copays, and required union dues. These items are unavoidable but don't show up on a standard credit report. Adding them to the calculation brought the picture into focus. Most online debt calculators will completely miss this category unless you manually include it. Once the true burden number was visible, we could prioritize paying down high-interest consumer debt while setting up a dedicated medical savings account to reduce the monthly hit elsewhere. Defining the burden precisely matters more than having a nice round budget. If you guess at your obligations, you will either overpay on one front and underpay on another or miss something entirely and get surprised later. Start by listing every automatic withdrawal, every loan payment, every premium, and every recurring subscription. Then categorize them. Mandatory expenses go in one group. Discretionary ones go in another. The split between those two groups tells you something important about your flexibility. Once you know what the invisible weight actually is, you can start breaking it apart. Here is the counter-intuitive part that most people miss: paying down the smallest balance first, which is the avalanche method recommended by some advisors, does not always produce the fastest debt elimination. The snowball method, where you target the lowest balance regardless of interest rate, often works better psychologically. The quick wins build momentum. People stick with it longer. You will save marginally more with pure math on paper, but you will likely abandon the plan if it takes six months to see your first closed account. Six months of no visible progress is exhausting. A payoff in three weeks changes everything about your approach going forward.
I learned this the hard way myself. Early in my career, I followed a strict avalanche strategy and stopped a client from using the snowball method. They fell off the wagon after four months with no accounts closed. The avalanche math was correct. The result was failure. Switching to snowball paid off two small cards within the first five weeks. Their confidence shifted, and they stuck with the plan through the harder, higher-interest balances later on. We ended up paying off the debt faster than the spreadsheet predicted, purely because they never quit. Another nuance beginners usually overlook: the interest rate on your debt is not the only thing that matters. The minimum payment structure does. If you have a loan with a low rate but a payment that barely covers interest, you are trapped in long-term payments for no good reason. Conversely, a higher-rate loan with a manageable minimum payment gives you breathing room. Prioritize loans that compress your cash flow, not just the ones charging the most interest per year. This is especially relevant for auto loans and personal loans with terms stretched to seven or eight years. Those extended terms keep payments artificially low while the interest builds quietly in the background. There are scenarios where neither method works cleanly. If someone has variable-rate debt, like credit cards that fluctuate with the prime rate, the math becomes unpredictable. High inflation environments also change the calculus. In those cases, I recommend freezing the debt structure entirely before doing anything else. Refinancing high-variable balances into fixed rates stabilizes the numbers. You might lose money on prepayment penalties, but the certainty of knowing exactly what you owe each month removes the anxiety component that makes economic stress feel so heavy. Certainty beats optimization when you are already stressed.
Get the Full Details
To actually track your burden, I use a simple sheet. Column one lists every obligation. Column two shows the balance. Column three tracks the monthly payment. Column four calculates the interest rate. Column five notes whether the obligation is mandatory or discretionary. Column six is where you calculate the total percentage of your take-home pay consumed by mandatory items. That final column is your real number. It is more accurate than any online calculator that ignores things like mandatory car insurance increases or union fees. When your mandatory percentage exceeds 50%, you are in the danger zone. Most financial advisors stop there, but I would flag the point where it exceeds 60% as critical. At that level, any unexpected expense becomes a crisis. A blown tire, a medical copay, a home repair that pops up because you are not saving enough for maintenance. The system breaks under its own weight. At 60%, the priority is not accelerating debt repayment. It is reducing the mandatory floor by negotiating bills, switching providers, or finding income supplements that specifically target the gap between your current expenses and your income ceiling. If you have no room to cut and no room to earn, the only path left is restructuring. Refinance high-interest consumer debt, consolidate loans where rates justify the fees, and negotiate directly with creditors before sending the debt to collections. Creditors would rather recover part of what you owe than none of it. A call explaining your situation often unlocks payment plans that never appear on generic advice websites. I once had a creditor agree to lower the interest rate by two full percentage points and extend the term by eighteen months without a single hard inquiry, just from a phone call. That reduced the monthly burden by $140, which was enough to stop the spiral.
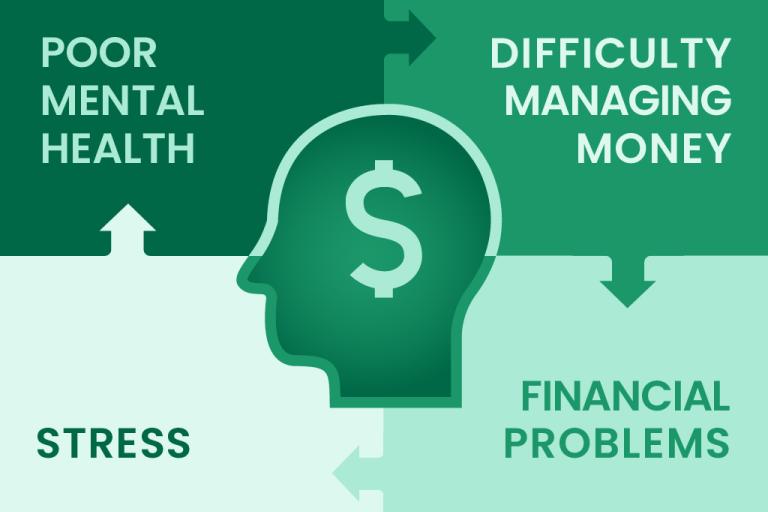
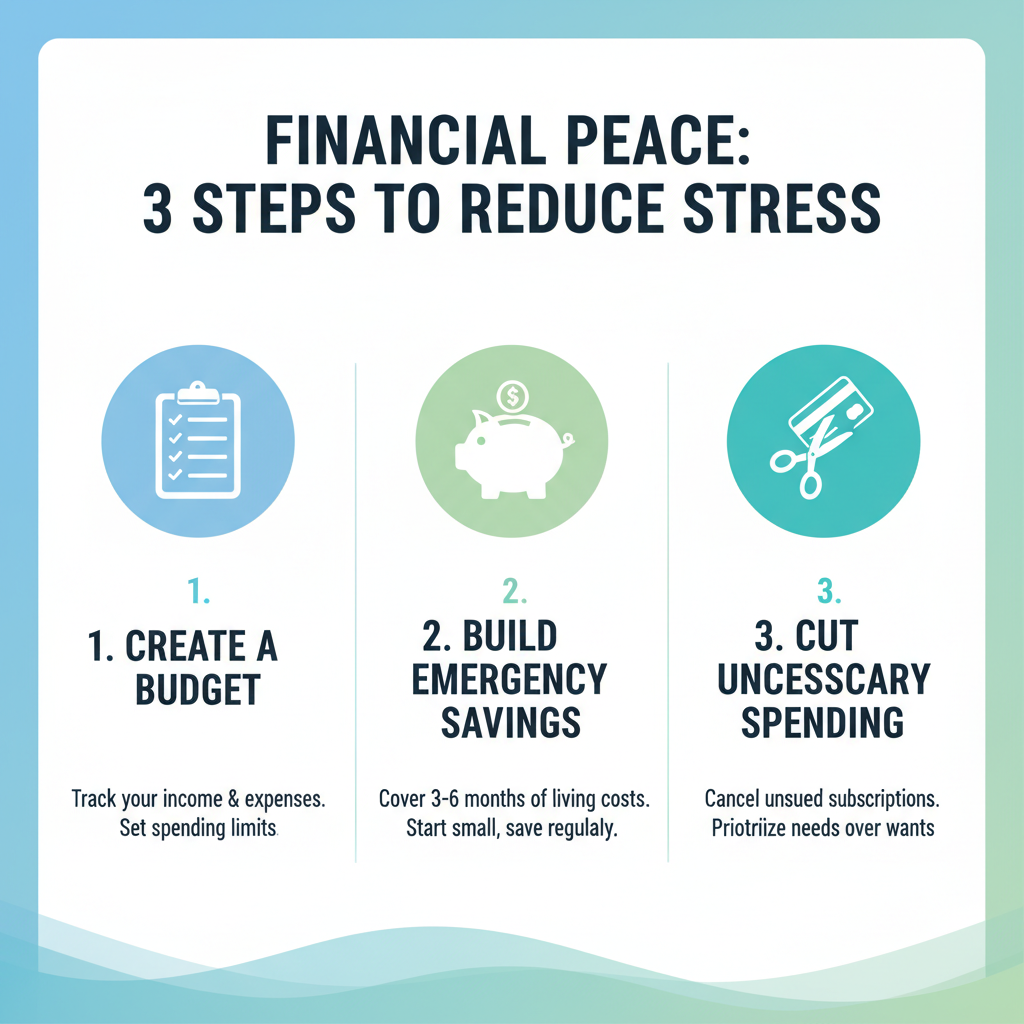
The economic stress piece is the hardest part to address because it lives in your head. Knowing your exact numbers reduces some of that anxiety. But it does not eliminate it. There is a gap between understanding the math and feeling less stressed about money. For most people, that gap is filled by taking one concrete action within forty-eight hours of completing the calculation. Opening a separate savings account for emergencies, calling a creditor, canceling a discretionary subscription, setting up automatic transfers. Action breaks the paralysis. Staring at the numbers without doing anything lets the weight grow heavier by the day. Set up a weekly review. Fifteen minutes, maybe twenty at most, to check your balances, track progress, and adjust for any changes in income or expenses. This keeps the invisible weight visible and contained instead of letting it accumulate silently until it becomes unmanageable. Missing a month of reviews usually means missing two more. The habit itself matters as much as the numbers inside it. Downloadable tools exist, but most of them are bloated with features you will never use. I stripped mine down to the essentials: a main sheet for tracking obligations, a secondary sheet for monthly snapshots of progress, and a third sheet for planning different payoff scenarios. The third sheet is where you test strategies. You can run through snowball versus avalanche variations, see how refinancing changes your timeline, or model what happens if you pick up a side gig for extra income. This takes about ten minutes to set up and saves hours of confusion later when you are trying to decide between competing approaches.
The goal here is not perfection. It is visibility. Most people carry financial weight because they do not know exactly how much they are carrying. Once you can see the full load, you can redistribute it, shed what you do not need, or accept what you must carry and build the strength to bear it. That is what defining the burden actually gets you. A clear picture.