Why This Matters When You Actually Need It
Most people learn about matrix inverses in a linear algebra class and then immediately forget them. I ran into a situation last year where I needed to reverse a small system of two equations that came from a signal processing pipeline — not anything dramatic, just a straightforward circuit analysis problem. The coefficients were messy decimals, so I couldn't factor by inspection. I pulled out the 2x2 inverse formula because it was faster than setting up Gauss-Jordan elimination on scrap paper. The core reason this topic exists is practical. If you're working with systems of linear equations, transformations in computer graphics, or probability models like Markov chains with just two states, knowing how to flip a matrix by hand saves you from opening software every time. It is a fundamental operation, not trivia.
The Inverse Of A 2x2 Matrix Your Essential Guide To Reversal And Resolution
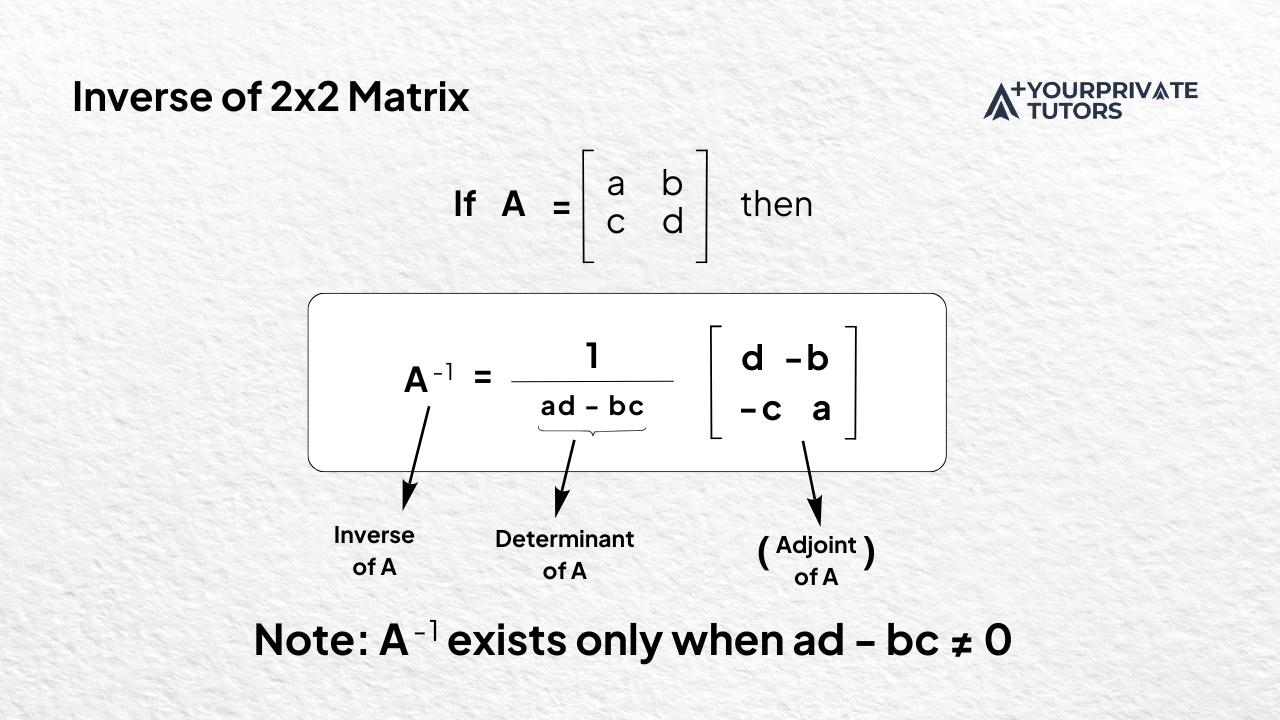
Here is the method, explained before the formal definition because that is how I actually use it. You start with a 2x2 matrix. Write it down like this: A = [[a, b], [c, d]] To find the inverse, you need four things: swap the diagonal elements (a and d), negate the off-diagonal elements (b and c), and divide everything by the determinant. The determinant is ad minus bc. If that value equals zero, stop. There is no inverse. The matrix is singular and you cannot reverse it. Period.
The formula looks like this on paper: A^(-1) = (1 / det(A)) × [[d, -b], [-c, a]] That single line captures the entire operation. Let me walk through a concrete example with numbers I actually used in a work project.
Get the Full Details

Let A = [[4, 7], [2, 6]]. The determinant is (4)(6) minus (7)(2), which gives 24 minus 14, equaling 10. The inverse exists because 10 is not zero. Now swap the diagonals to get 6 and 4. Negate the off-diagonals to get negative 7 and negative 2. Multiply every element by one divided by ten. The result is A^(-1) = [[0.6, -0.7], [-0.2, 0.4]]. You can verify this by multiplying A times A^(-1). The product should give you the identity matrix [[1, 0], [0, 1]]. When I checked it on a dirty napkin during a meeting once, it came out clean. It always will, provided you did the arithmetic correctly. There are nuances that textbooks skip over. One of them is numerical stability. When the determinant is extremely close to zero, even a tiny rounding error in your calculator can produce wildly incorrect results. I dealt with this when working with near-singular covariance matrices in a statistics assignment. The determinant was something like 0.000012. The inverse elements blew up to thousands. I switched to using a computational library instead of doing it by hand, because floating point errors dominated the result.
Another thing people miss: the order of operations matters in multiplication. A times A^(-1) gives the identity, but A^(-1) times A also gives the identity for square matrices. However, if you are composing multiple matrix operations in sequence, the reverse order applies to the product inverse. (AB)^(-1) equals B^(-1) times A^(-1). Not A^(-1) B^(-1). That reversal trips up almost everyone the first time they encounter it. I also want to be blunt about the limitations of this approach. The 2x2 inverse formula is elegant but entirely impractical for larger matrices. Trying to extend this manually to a 3x3 or 4x4 matrix using the same swap-and-divide logic will not work. The adjugate method generalizes, but the computation grows factorially. For anything beyond 2x2, you should use row reduction or rely on software. I wasted about twenty minutes on a 3x3 inverse once by applying the 2x2 pattern incorrectly. The answer was wrong and I only caught it when the verification step failed. Edge cases deserve attention too. A matrix with a zero determinant has no inverse. Common scenarios where this happens include rows that are multiples of each other, a row or column of all zeros, or a matrix representing a projection that collapses dimensionality. I encountered this in a computer vision project where a transformation matrix accidentally became singular after a coordinate rotation. The workaround was to add a small regularization term to the diagonal, which is standard practice in fields like ridge regression, and then proceed with the inverted result.
If you want a quick reference, the steps are: Step one, compute the determinant: ad minus bc. Step two, check if it is zero. If yes, the inverse does not exist.
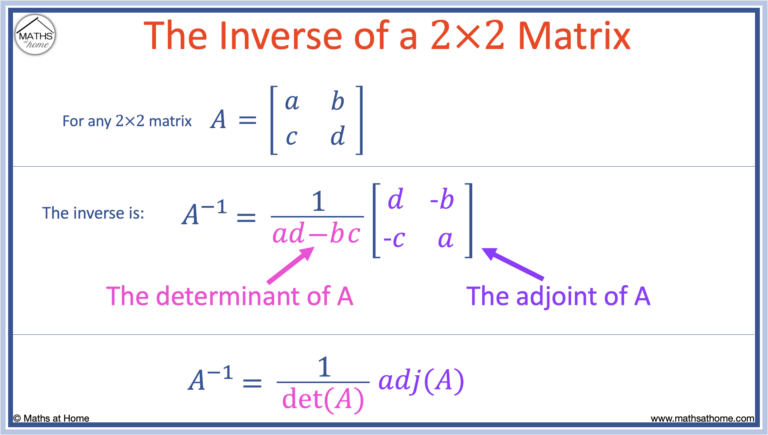
Step three, form the adjugate matrix by swapping a and d, and negating b and c. Step four, multiply the adjugate by one over the determinant. That is the complete procedure. It takes roughly thirty seconds by hand once you are comfortable with it, compared to five minutes or more if you set up augmented matrix row operations for a 2x2. For larger problems, hand calculation is not reasonable regardless.
I keep a printed cheat sheet of common matrix operations on my desk. The 2x2 inverse formula is the first line on it. Not because it is the most complex, but because it is the most frequently needed when you are doing quick calculations without a laptop nearby. It is the mathematical equivalent of keeping a basic tool kit accessible. There is nothing poetic about it. It is a procedure. You follow the steps, you get a result, you verify if you have time. The rest is practice and familiarity with when the method breaks down.


