How the 1920s installment system actually worked, and why it still matters
Most people treat the story of 1920s consumer credit like it's a moral fable: rich companies tricked regular folks into buying things they couldn't afford, debt spiraled, crash happened. The reality is uglier and more interesting than that. Installment selling wasn't a sudden invention or a trick. It was a deliberate redesign of how goods moved from factory to household, and the financial architecture that came with it. Before the 1920s, you bought most durable goods with cash. A refrigerator cost about $150 to $200 in 1920, which was roughly three to four months' wages for a working-family earner. You saved up, or you didn't. There was no middle ground. Then Frigidaire and Chevrolet led the charge on monthly payment plans, and suddenly the entire concept of a large purchase shifted. You weren't saving. You were entering a contract. The mechanics were straightforward but structurally significant. A buyer put down a small deposit, often 25 percent, and paid the rest in equal monthly installments over six to eighteen months. The interest was baked into the payment amount rather than shown as a separate finance charge, which made the true cost harder to calculate without doing the math yourself. That design choice wasn't accidental. It was the feature that made the system stick.
By 1929, roughly 60 percent of cars and 80 percent of radios were sold on installment plans. Household appliances followed the same pattern. The Federal Reserve reported that consumer credit outstanding grew from about $1.7 billion in 1920 to over $7 billion by 1929. That is not a small number. It changed the velocity of money through the economy because purchases that once required years of saving now required a pay stub and a signature. I spent several years digging through estate sale contracts, old retail ledgers, and municipal court records from Ohio and Michigan where installment defaults ended up in front of judges. The thing nobody tells you about this era is how much of it was procedural, not dramatic. People rarely fell into debt because they were reckless. They fell into it because the payment schedule was rigid and life was not. A layoff in November did not care that your Frigidaire payment was due on the first. The contracts had no grace period built in, no adjustment mechanism, nothing that acknowledged your income could fluctuate. When someone missed payments, the company would repossess the item and still pursue the remaining balance. That is the part that gets glossed over. You lost the goods and kept owing money. I found a case from 1927 where a family in Cleveland had their piano repossessed after three missed payments, and the creditor still sued for the remaining $47 owed on a $120 contract. The court enforced it. That was the standard operating procedure.
The deeper insight most people miss is that the cultural shift happened before the Crash of 1929. The revolution was not caused by the Depression. The Depression exposed the fragility of a system that had expanded credit faster than people's ability to maintain payments through any kind of economic shock. Consumer debt was already normalized by 1928. It was a habit, not a crisis, until wages started dropping and the habit became unsustainable. Another detail that gets lost: the role of department stores versus manufacturers. Chevrolet and Frigidaire pushed their own credit programs directly. But Sears, Roebuck & Co. operated something closer to a general installment platform. If you ordered a washing machine from Sears in 1925, you were entering the same kind of payment agreement whether you needed one or were just keeping up with neighbors who had gotten one. The catalog made it feel ordinary. That ordinariness is what made the system durable. Here is the practical takeaway if you are trying to understand modern consumer credit through this lens. The same structural logic that ran the 1920s installment market is visible in almost every BNPL product and rent-to-own contract today. Small down payment, fixed monthly installments, interest hidden inside the payment amount, repossession or fee escalation on default, no income flexibility. The presentation changes. The architecture does not.
Get the Full Details
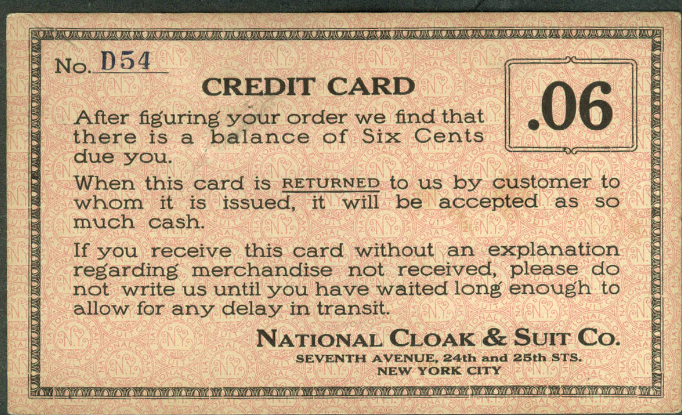
There is also a documentation problem that catches people off guard. Original 1920s installment contracts are fragile, often printed on cheap pulp paper that crumbles if you fold them wrong. If you are researching a specific contract or trying to verify what someone signed, handle them flat, use a book cradle if you have one, and photograph before you transcribe. I learned that the hard way with a 1924 auto installment agreement from a collection in Toledo. I went to unfold it to read the fine print and the spine separated. It was still legible, barely, but I lost about twenty minutes and some confidence in my handling skills. The bigger problem with studying this period is the secondary literature. Most economics textbooks reduce the 1920s installment boom to a cautionary footnote. They get the direction right but miss the mechanism. The real story is in primary sources: contract templates, company annual reports from the time, court dockets, and consumer pamphlets that were distributed by credit advocates who were actually trying to warn people about what was coming. Those warning pamphlets are worth reading. They are not alarmist. They are technical. If you want a concrete example of how to read one of these contracts, look at the difference between the headline payment and the total cost. A $100 radio on a twelve-month plan at what the company called a "service charge" of 5 percent might show a monthly payment of $8.81. That looks reasonable until you multiply it and realize you paid $105.72 for a $100 item, and the 5 percent was not simple interest but compounded through the payment structure. The real annualized rate was closer to 9 percent depending on how the balance accelerated. Companies rarely highlighted that calculation.
One useful workaround when you are trying to reconstruct the actual cost of a 1920s installment plan from a scanned contract is to use a reverse amortization spreadsheet. Enter the monthly payment, the number of months, and the total of all payments. Work backward to find the implicit rate. It takes about ten minutes and it will tell you whether the deal was actually favorable or just well-packaged. I use this method when I encounter contracts from estate sales and it has saved me from accepting surface-level numbers too quickly. There is a limitation I should state plainly. The installment system of the 1920s was not uniformly exploitative. For many families, it was the only way to access goods that improved their lives. A refrigerator changed food storage, hygiene, and daily labor. An automobile changed commute options and economic mobility. The system provided access that did not exist otherwise. The problem was not access. The problem was that access came with rigid obligations and no safety net, and the expansion outpaced the ability of most workers to sustain payments during normal economic cycles, let alone a severe downturn. That distinction matters because it prevents you from seeing the 1920s installment boom as either pure greed or pure progress. It was both. It was a legitimate innovation in retail financing that also created structural vulnerability. The culture of consumer debt that emerged was not an accident. It was the expected outcome of making credit widely available while keeping the repayment terms inflexible and the true costs opaque.
If you are researching this topic, start with the Federal Reserve bulletins from 1920 to 1930. They contain the actual credit outstanding data, broken down by category. Then move to the company records of Frigidaire, Chevrolet, and Sears. After that, check municipal court dockets for repossession and deficiency judgment cases. Those three sources together will give you a far more accurate picture than any modern summary. The contracts themselves are held in several archives. The Herbert Hoover Presidential Library has a significant collection. The Illinois State Archives holds municipal court records from Chicago area cases. The Michigan History Center has retail and credit materials. If you cannot visit in person, many of these collections have finding aids online. The contracts are not digitized in full, but the indices are searchable and can point you to the relevant box and folder numbers. One thing I wish more people understood about this history is that the backlash against installment selling was immediate and organized. Consumer leagues formed in the 1920s specifically to monitor credit terms and publish comparisons. They produced pamphlets that listed the real annual percentage rates for common installment plans. Those publications exist. They are not hard to find. Reading them alongside the contracts gives you the contemporary perspective rather than the retrospective one.
The modern equivalent of this research is simpler in some ways and harder in others. Modern credit terms are digitized, but they are also deliberately obscured. The 1920s contracts were plain about the payment amount and duration. They were less plain about the effective interest rate, but the math was visible if you did it. Today the math is often buried in terms of service pages and variable rate disclosures that change based on your credit score at checkout. The structure is the same. The opacity has just improved. I still keep a folder of 1920s installment contract images on my desktop. Not because I expect to use them every day, but because they are a reference point. When I see a new product launching with "pay in four interest-free payments" or "own it today, pay over twelve months," I look at the old contracts and remind myself that this is not new. It is just rebranded. The underlying mechanism has not changed since Frigidaire decided that a monthly payment was easier to sell than a cash price. If you want to go deeper, the best single volume on this topic is David M. Potter's People of Abundance, though it is more cultural history than technical analysis. For the financial mechanics, look at work by scholars like Paul Kennedy and Roger Horowitz, who has written extensively on the evolution of American credit. His book Pay Here, Pay Now, Pay Later covers the period with more attention to the actual contracts than most general histories do.
The short version is that the 1920s installment system created consumer debt culture because it made credit ordinary, routine, and invisible in its true cost. It did not require deception to work. It only required that people be willing to trade future income for present goods, and that the terms be presented in a way that made the trade feel reasonable. That is what happened. It happened everywhere at once. It still happens, just under different names.