Understanding The Home Depot Credit Card Options
I spent about three years dealing with contractor billing at a supply company before anyone ever asked me about The Home Depot card situation. Most people have no idea there are actually three different cards on offer. The Special Financing Card, the Consumer Card, and the Commercial Card. They operate completely different from each other. The Special Financing Card is the one most people mean when they talk about "the Home Depot card." It gives you promotional financing, usually 24 to 60 months with no interest if you pay it off in that window. That part works fine on paper. The problem is what happens after that promotional period expires. You get hit with retroactive interest at an APR that currently runs around 29.99%. I have seen people get charged over four thousand dollars in back interest on a $3,000 purchase because they missed the payoff deadline by three days.
The Home Depot Card Payment A Comprehensive Guide To Shopping Smarter
Getting approved for any of these cards happens through their website or inside a store. The application takes about two minutes. You typically get an instant decision. The credit check is a soft pull initially, but they do a hard pull once you activate the card. If your credit score sits between 640 and 670, you might still get approved, but your promo terms won't be as good. The best deals go to people with 720 and above. Here is how the payment process actually works. Log into your account on homedepot.com, go to the credit card section, and select make a payment. You can pay by bank account, debit card, or another credit card. Bank account payments show up immediately. Debit card payments take one to two business days. Credit card payments take two to three days. If you are trying to hit a promo payoff deadline, timing matters enormously. I learned this the hard way a few years ago. A customer needed to pay off a commercial equipment purchase before the promotional period ended. He submitted the payment on his phone the evening before the deadline. The payment didn't post until the next business day because he had linked a debit card. He was charged retroactive interest on about $1,200. The workaround for people in that situation is to pay by bank account or use the mobile app's instant pay feature if available. Even then, set the payment to go through at least 48 hours before the actual deadline. That buffers against processing delays.
How The Commercial Card Differs
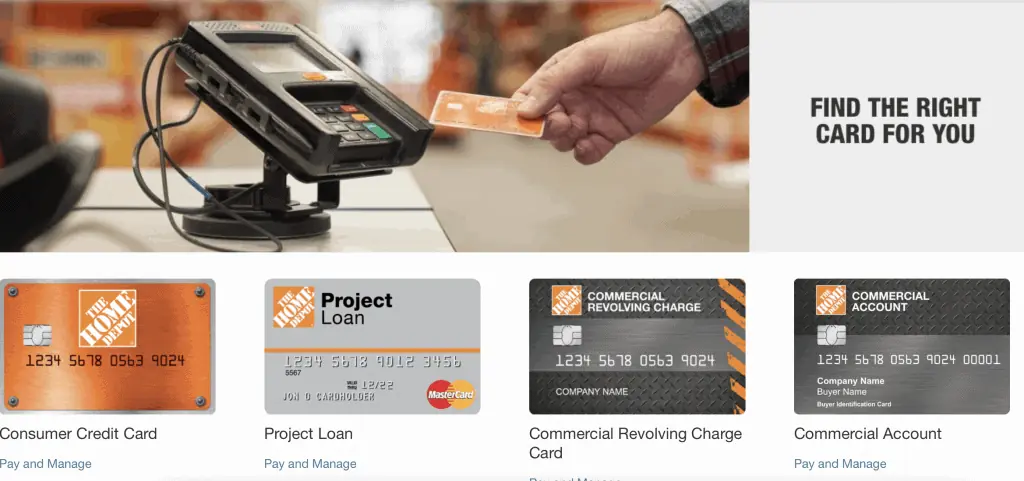
The Commercial Card is built for businesses and contractors. It runs on Net 30 terms originally, which means you get 30 days to pay your balance in full. After that, standard net terms apply. Some accounts qualify for extended payment terms like Net 60 or even Net 90 depending on your business history and creditworthiness. The commercial card does not offer personal promotional financing. It is strictly a business tool. Payment for the commercial account happens through a separate portal. You log into the commercial account system, not the consumer one. The accepted payment methods are slightly different. Bank account transfers are preferred. Wire transfers work too but cost around $15 per transaction. Checks are accepted but take five to seven business days to process. ACH returns run about $25 if your bank account has insufficient funds. The real advantage of the commercial card is the purchase power. Personal cards cap out somewhere between $1,500 and $3,000 for most people. Commercial cards can go up to $50,000 or more depending on your business revenue and credit profile. If you run a contracting business buying materials regularly, the commercial card makes more sense than trying to max out personal cards across three different accounts.
Get the Full Details

Common Mistakes People Make
One major mistake is confusing the two different card systems. The consumer portal and the commercial portal are completely separate. If you applied through a store as a homeowner but also have a business registered under your name, you might accidentally try to pay a commercial balance through the consumer site. It will not work. You have to log into the correct portal for the card type. I see this happen maybe once a week in my old support days. Another mistake is assuming that making a partial payment resets the promotional clock. It does not. The entire balance must be paid in full by the deadline date to avoid retroactive interest. Paying half the balance before the promo ends does nothing to protect you from the interest charge on the remaining half. This is counter-intuitive because it is how most installment loans work, but promotional retail financing is structured differently. The full amount must be cleared by the cutoff date. There is also the issue of returns after you have paid off a promotional balance. If you return an item from a financed purchase, the refund goes back to your card balance first. If your balance is already zero, the store issues you a check or store credit. You cannot get cash back unless you paid with cash or check originally. This catches people off guard. I had someone get frustrated because she returned a $400 appliance after paying off her promo in full and expected the money back on her card. Instead she got a check that took two weeks to arrive.
Things The Card Does Not Do Well
The biggest weakness of The Home Depot card system is customer service accessibility. Calling them gets you on hold for 30 to 45 minutes during business hours. The automated system is frustrating because it sometimes loops you back to the main menu instead of letting you navigate to payment options. The web portal is more reliable for routine payments. But if you have a problem like a payment not posting correctly or a discrepancy on your statement, you will eventually need to call. Prepare for a long wait. Another limitation is that the card does not work everywhere. It is only accepted at Home Depot stores, Home Depot installments, and homedepot.com. You cannot use it at Lowe's, Menards, or any other home improvement retailer. Some people open the card thinking it gives them flexibility across different suppliers. It does not. It is Home Depot exclusive. The retroactive interest structure is also a vulnerability. Unlike most credit cards where you only pay interest on what you carry forward, promotional financing charges interest on the original purchase amount from the date of purchase if you miss the deadline. That is significantly more punitive than standard credit card interest. A $2,000 purchase at 29.99% APR for six months comes to roughly $300 in interest if you miss the promo. Most people do not read the fine print carefully enough to understand this mechanic before they apply.
Practical Payment Tips That Actually Matter
Set up automatic payments for at least the minimum amount due. This prevents late fees and protects your credit score. Late payments get reported to the credit bureaus after 30 days. One late payment can drop your score by 50 to 100 points. For a contractor whose business depends on personal credit, that is real damage. If you are using a promotional offer, set a reminder on your calendar for five days before the promo end date. Not the day of. Five days gives you buffer time for processing delays or technical issues. Check your balance in the app at least once a week during the promo period so you know exactly how much you need to pay by the deadline. Pay early when possible. The sooner you pay, the less chance something goes wrong before the deadline. I always recommend paying two to three business days ahead of any critical deadline. It costs you nothing and saves you from potentially thousands in retroactive interest charges.
Keep records of every payment. Save confirmation numbers, take screenshots of payment confirmations, and note the date and time. If a payment does not post correctly, having documentation speeds up resolution dramatically. Without proof of payment, you are stuck waiting for someone to look into it. With a confirmation number, they can find the transaction in minutes.
When to Use the Card vs When to Walk Away
The Home Depot card makes sense if you are a homeowner planning a single large project and you can realistically pay it off within the promotional window. Kitchen remodels, roof replacements, and HVAC installations are the typical use cases. Just make sure you have a solid plan to pay it off. Do not assume you will figure it out later. For contractors, the commercial card is worth considering if you buy materials frequently enough to justify the separate account management. The higher credit limits and bulk pricing discounts can offset the extra administrative work. But if you only buy materials occasionally, stick with your existing business credit card and skip the Home Depot commercial account. The hassle is not worth it for infrequent purchases. If you already carry high-interest debt on other cards, adding a Home Depot promotional card is not a smart move. Even with 0% intro financing, you are still taking on new debt. Pay down existing balances first. Then consider the Home Depot card if you have a specific project in mind and a realistic payoff timeline.
The application itself is straightforward. Go to homedepot.com, click on credit cards, and fill out the form. You will need your Social Security number, annual income, and housing information. The approval decision is usually immediate. If approved, you get a temporary card number you can use right away while waiting for the physical card to arrive in the mail. Activation is done through the website or mobile app. Once activated, your payment options open up immediately.