The High Stakes Of Los Angeles County Property Tax Understanding The Complexities And Consequences
Samantha
2025-06-20
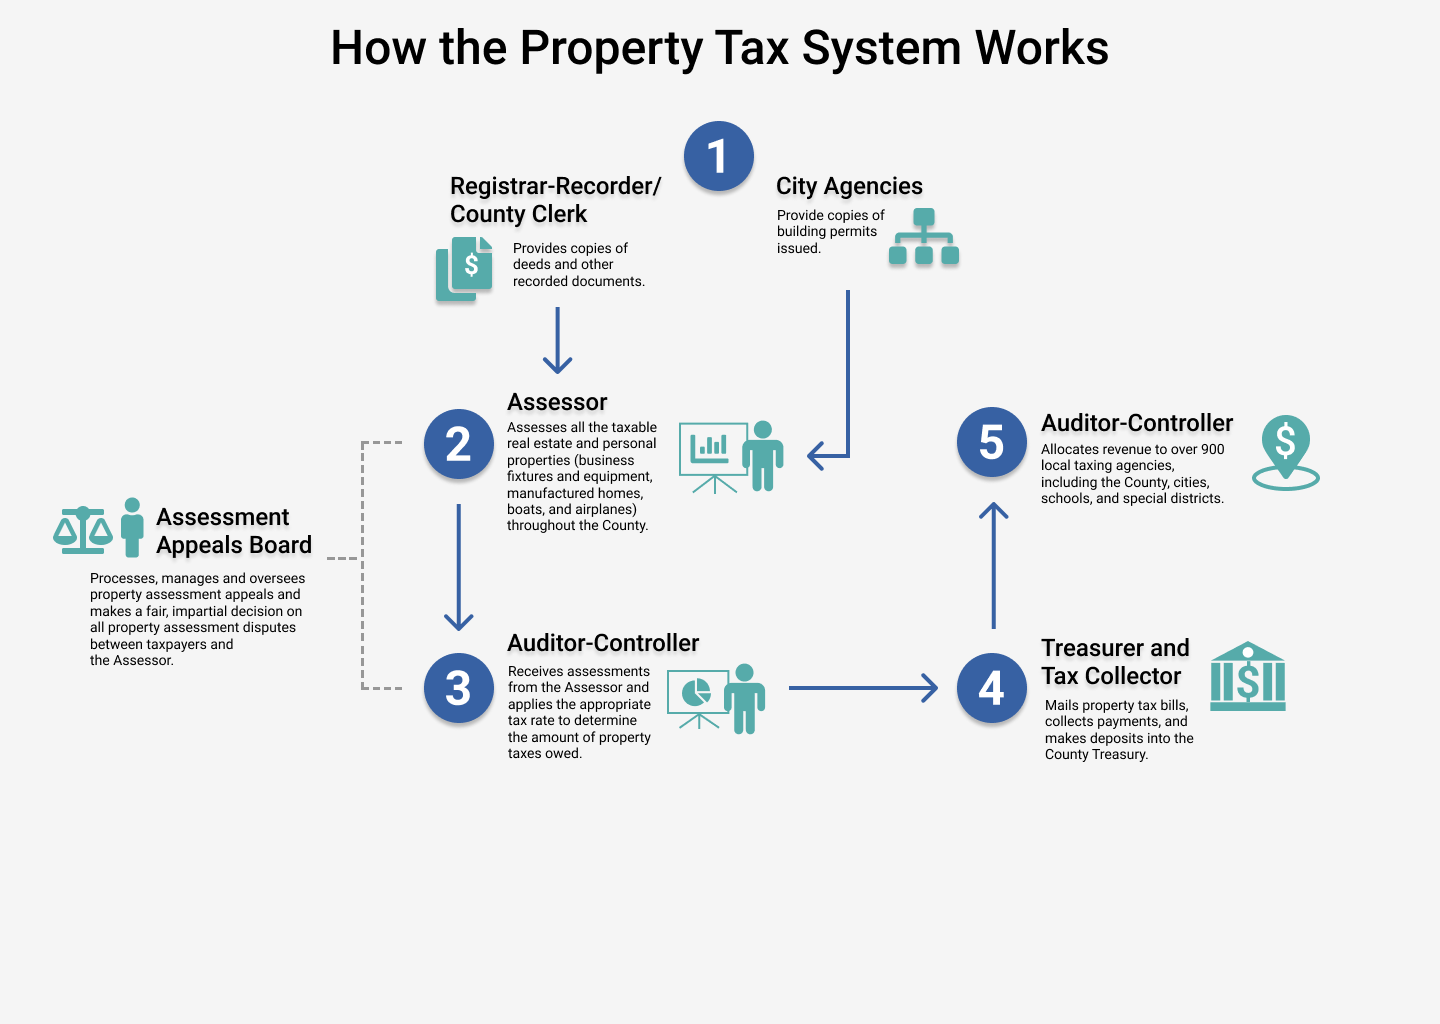
How Los Angeles County Actually Calculates What You Owe
LA County property taxes are not as straightforward as applying a single rate to your home value. The system is built on a patchwork of voter initiatives, county administrative rules, and state-mandated procedures that interact in ways most homeowners don't understand until they get a bill they can't explain. I have worked through enough of these cases to know where the system usually trips people up.
The Mechanics Behind The High Stakes Of Los Angeles County Property Tax Understanding The Complexities And Consequences
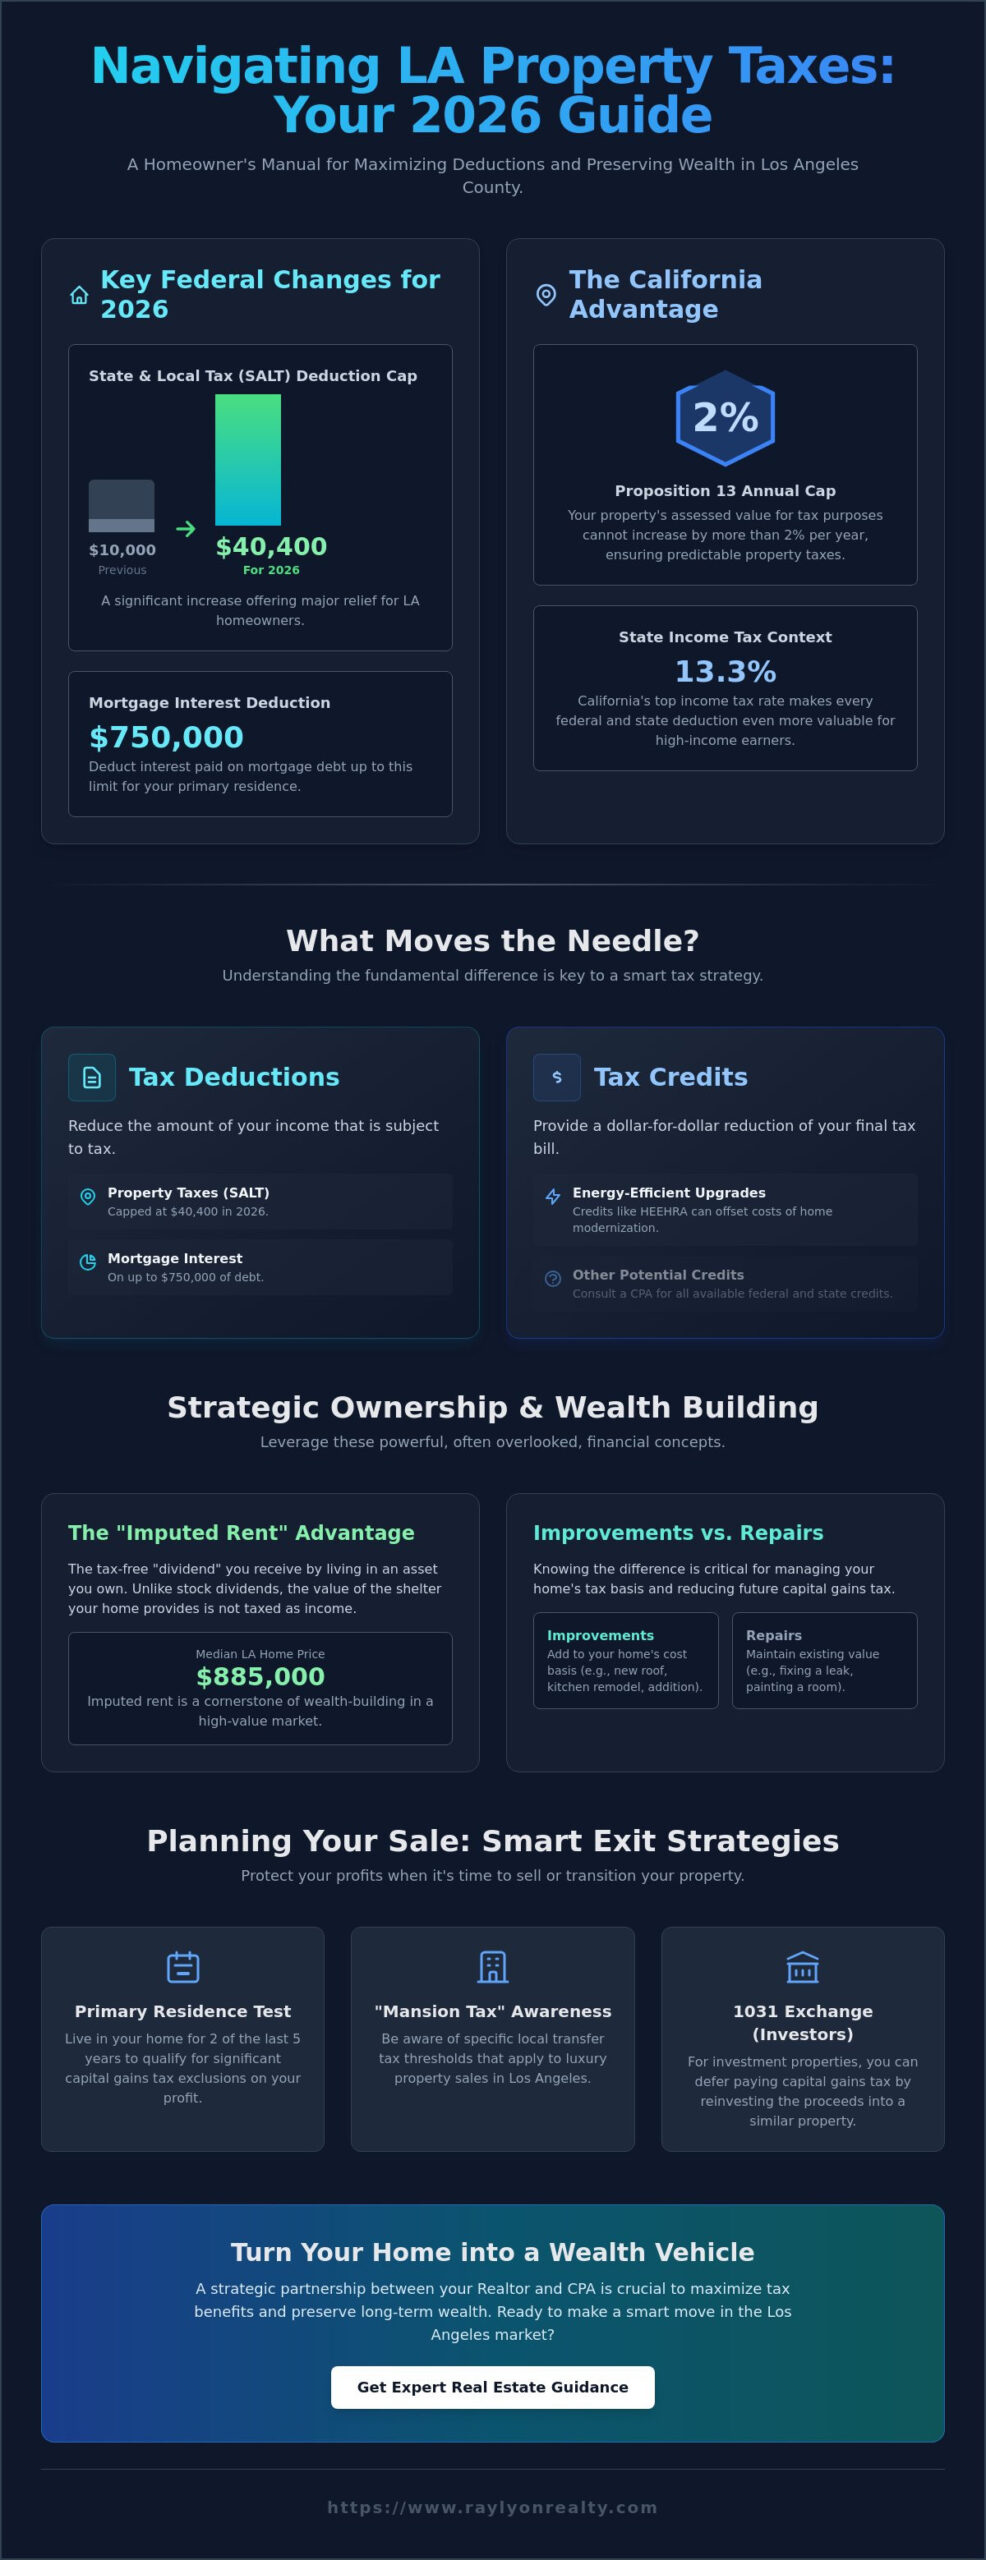
The foundation is Proposition 13, passed in 1978. It caps annual increases in assessed value at 2 percent and limits the general property tax rate to roughly 1 percent of assessed value, though the actual number varies because of additional bonds and district levies. Your base year value is locked in at the time of purchase or the previous reassessment event. That number only grows by up to 2 percent per year until something triggers a reassessment.
Change in ownership triggers reassessment. That seems simple, but the definition of change in ownership is broader than most people realize. A transfer to a revocable living trust does not trigger it. A transfer to an LLC where you already hold 100 percent of the membership interest generally does not trigger it either. But if you transfer half interest to your child while retaining the other half, that partial transfer absolutely triggers reassessment on the conveyed portion. I had a client last year who transferred a 25 percent interest to each of three children to avoid probate. He expected his property tax to stay the same. Instead, 75 percent of the property got revalued to current market value. His annual tax bill roughly doubled. He spent four months trying to unwind it, and the only real option was to buy those interests back, which triggered another reassessment at an even higher value because the market had moved in the meantime.
The supplemental tax bill is the piece that catches everyone off guard. When a reassessment happens, LA County sends you two bills instead of one. The regular secured bill continues based on your old assessed value, and a supplemental bill covers the difference between what you paid and what you should have paid under the new value. If you bought a house for $800,000 in January and the market value is now $1,100,000, your supplemental bill will cover the gap prorated from the date of transfer through the end of the fiscal year. Those supplemental bills can come months after closing, and they are not always sent to the right address. I once handled a case where a supplemental bill went to the seller's forwarding address and sat unread for eleven months. The lien had already compounded with penalties and interest by the time the buyer found it.
Navigation Within The High Stakes Of Los Angeles County Property Tax Understanding The Complexities And Consequences
The Assessor's Parcel Check tool on the LA County website will show you the current assessed value, the base year value, and the assessed value history for any parcel. It is free and takes about forty-five seconds to pull up. You type in the APN or the address. The data is usually updated within a few days of any recorded transaction, but there is a lag. I have seen cases where a transfer was recorded in March and the online records still showed the old value through April. Always verify with the most recent preliminary notice if you are in a transaction.
The Board of Supervisors sets the mill rates annually. The combined rate for most residential properties in LA County falls between 1.1 and 1.4 percent depending on the specific district. School bonds, flood control districts, and Mello-Roos community facility districts all add on top of the base rate. A single property can have twelve or more line items on its bill. If you are evaluating a property in an unincorporated area versus one inside city limits, the district breakdown will be completely different even if the homes are thirty miles apart.
Proposition 19, which took effect in April 2021, changed how family members can inherit a parent's property tax basis. Under the old Prop 60/90 rules, a child could transfer the parent's base year value to one replacement residence regardless of value. Prop 19 restricted this. Now, a parent-to-child transfer of the tax basis only works if the child uses the property as their primary residence, and the new market value can exceed the parent's assessed value by up to $1 million without triggering a supplemental tax. Anything above that $1 million cushion gets reassessed. This matters significantly in LA County where median home prices routinely exceed $1.5 million. A parent who bought a house for $400,000 and left it to their child in a neighborhood now worth $1.8 million will see a substantial tax increase on the portion above the $1 million threshold. I watched a client try to use the old rules as a planning basis and nearly lose the exemption because she had not accounted for the $1 million ceiling. The workaround was structuring the transfer through a trust that qualified under the parent-child exclusion provisions before Prop 19 changed the landscape, but that required moving quickly before the deadline.
Where The System Fails and What You Can Actually Do About It
The biggest blind spot in LA County property taxation is the interaction between assessed value and actual tax liability. The 2 percent cap protects assessed value growth, but it does not protect your tax bill. If mill rates rise across districts, your bill goes up even though your assessed value increased by less than 2 percent. Conversely, if a bond measure fails and a district's rate drops, your bill can decrease while your assessed value continues climbing. People confuse the two. They see a lower assessment increase and assume their taxes are under control. They are not.
Another frequent failure point is the claim of exemption process. The homeowner's exemption reduces assessed value by $7,000. It is automatic for most owner-occupied residences, but not always. If the property was inherited or transferred through a trust, the exemption does not always carry over. I had a situation where a mother died and the property passed to her son through a trust. The assessor's office did not apply the homeowner's exemption because the son had not filed a changed circumstances statement and the property was not yet flagged as owner-occupied in their system. He was paying property tax on a $650,000 overstatement for two years. Filing a changed circumstances statement and a claim for refund corrected it, but the refund process took eight months and required submitting sworn proof of occupancy, a copy of the death certificate, and a notarized statement from the trustee.
The appeal process is another area where people waste time. The annual appeal window for LA County is typically November 15 through February 15 for the next fiscal year. If you miss it, you are locked into that assessed value for the entire year. The value assessment appeals board handles most residential cases, but the process is not designed to be fast. Filing an appeal through the Assessor's online portal takes about ten minutes. Getting a hearing date usually takes six to eight weeks. Presenting your case takes another four to six weeks after that. A typical appeal timeline from filing to decision runs about four months. If you disagree with the decision, you can petition the superior court, but that adds another six to nine months and costs a filing fee of several hundred dollars. For most homeowners, the practical ceiling is the board of equalization hearing. Beyond that point, the cost and time investment rarely justifies the potential reduction.
I also want to be honest about what the system cannot fix. If a property has an unpermitted addition that was never declared, the assessor's records will not reflect the additional square footage, but the tax roll may still be based on incomplete data. When you eventually sell, the reassessment will catch up with whatever the market says the property is worth, including the unpermitted space. There is no legitimate way to shelter that value permanently. The same applies to properties in flood zones or with environmental liens. Those do not reduce your property tax, and they certainly do not make the assessment process easier.
Practical Steps If You Are Dealing With This Right Now
Pull your current tax bill and look at each line item. Note the mill rate for each district and the total tax rate. Compare it to the previous year's bill. If the total rate changed by more than 0.1 percent without a new bond measure, investigate why. It is usually a district rate adjustment or a Mello-Roos assessment that is phasing out or being added.
Check the assessed value history on the Assessor's website. If you see a jump that does not correspond to a recorded transaction, a partial reassessment, or a new construction permit, there may be an error. File a corrected value inquiry before the appeal window closes.
If you inherited or received a property transfer recently, confirm whether the homeowner's exemption applied. If it did not, file a claim for refund with supporting documentation. The refund window is generally three years from the date of payment, so do not wait.
For properties with multiple parcels or split interests, review the apportionment carefully. The Assessor divides base year value proportionally based on land value ratios, not simply by square footage or parcel count. I had a case where a 40-acre ranch was split into four 10-acre parcels, and because the parcels had wildly different soil qualities and frontage, the assessed value split did not equalize evenly. One parcel ended up with 40 percent of the total assessed value despite being only 25 percent of the land area. That discrepancy cost the owner an extra $3,000 annually in property taxes. Correcting it required a formal reapportionment request with an independent appraisal supporting the different land values.
The system will not warn you about these issues. It will send you a bill and expect payment. The complexities are baked into the structure, and the consequences are real. Knowing which levers actually move the needle is the only thing that separates people who get surprised by their tax bill from people who understand what they are looking at.
Gallery The High Stakes Of Los Angeles County Property Tax Understanding The Complexities And Consequences
Property Tax Calculator Los Angeles County: The 2026 Homeowner’s Guide ...
Overview Los Angeles County - Property Tax Portal
Understanding Property Taxes in Los Angeles County: A 2026 Strategic ...
How to Appeal Property Tax Assessment in Los Angeles County
The SHOCKING Truth About Los Angeles County Property Taxes in 2024 ...