The Gray Economy Of Stolen Rewards
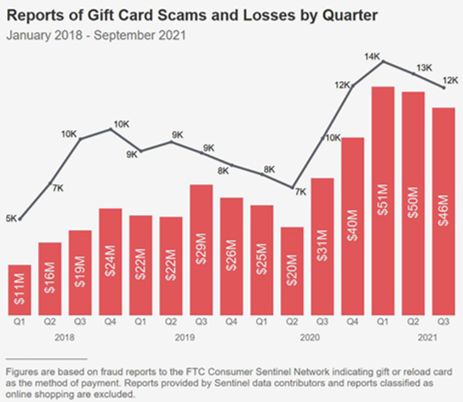
I spent three years watching gift card resellers on Reddit, Discord, and eBay before I understood the actual mechanics. Most people think it's just people selling unused cards at a discount. That's not what happens. The market runs on compromised codes, chargeback fraud, and rewards program exploitation. The margins are thin and the risk is high. I've seen people make real money and I've seen others get banned from every platform and report to their bank. It's a real trade. The basic supply chain works like this. Someone steals or fraudulently obtains a gift card code. They sell it on a marketplace for 60 to 80 percent of face value. The buyer redeems it and flips the balance onto something liquid, usually Bitcoin, PayPal, or a second gift card with wider acceptance. The reseller pockets the spread. The card issuer takes the loss. Everyone moves fast and hopes nobody traces the original transaction back.
The Hidden World Of Used Gift Card Codes Beneath The Surface Of Online Marketplaces
Here's how I actually learned to navigate this space. I started by watching eBay listings for Amazon and Walmart cards under face value. If a $100 card was listed for $75, I'd note the seller's history, completion rate, and how long they'd been active. Fresh accounts with perfect ratings are usually either bots or freshly stolen credentials. Established sellers with 2,000 plus transactions and a mix of neutral feedback are the real operators. They're not trying to be invisible because they've been doing this long enough to know basic reputation matters. I bought my first batch from a seller on Discord called GiftcardExchange who had been operating since 2019. The process was straightforward but not clean. He'd send a code, I'd verify the balance within five minutes, and confirm receipt. If the code worked, he'd release the next one. If it didn't, he'd refund or replace it. Most codes worked. About one in eight failed, and those were the flagged ones. The ones that failed usually came with an explanation from the seller, something like "issuer pulled it" or "chargeback caught up." Those were the warning signs that the code was already burned. The platforms shift constantly. Reddit communities like r/Giftcardexchange and r/tradingcards pop up and get banned regularly. Discord servers rotate names and invite links weekly. eBay cracks down periodically and reinstates sellers through shell accounts. Telegram channels are where the higher volume trades happen now, but they're almost entirely unmoderated. You're dealing with people who have no accountability whatsoever.
Buyers who survive longer than a few weeks develop a few habits. Always check the balance before confirming. Never pay outside the platform's payment system. Avoid any code that's been listed more than once on different forums. Watch for sellers who pressure you to confirm receipt before you've actually tested the code. And never buy a code that's already been redeemed partially, because those usually trigger fraud alerts on the issuer's end.
Get the Full Details
Where The Codes Actually Come From
Understanding the source helps you evaluate risk. The main categories are chargeback fraud, account takeover, employee theft, rewards exploitation, and cashback scraping. Each has different failure rates and different warning signs. Chargeback fraud is the most common source. A buyer purchases a gift card with a stolen credit card, then disputes the charge with their bank. The bank reverses the payment, the original transaction falls, and the gift card becomes free money. The code circulates at discount until the issuer catches it. These codes typically last anywhere from a few hours to a few days before being flagged. If a code fails immediately upon redemption, that's usually a chargeback pull. The issuer reversed the underlying transaction and voided the card balance. Account takeover is growing. Hackers breach retail loyalty accounts, drain the gift card balances, and sell the codes in bulk. These tend to last longer than chargeback codes because there's no disputed transaction triggering the flag. The telltale sign is a code from a major retailer like Target or Walmart that's been loaded with a large amount and sold at a steep discount. Legitimate resellers don't need to move that volume fast. Stolen accounts do.
Employee theft happens at grocery stores and big box retailers. Workers scan gift cards at point of sale, hit a promo or clearance button that applies a discount or bonus, and pocket the difference. These codes sometimes come with unusual promotional labels or bonus balances that don't match normal retail pricing. I learned to watch for codes that showed bonus rewards that seemed too good to be true, because they usually were from internal systems. Rewards exploitation is more sophisticated. People find loopholes in bank and credit card reward programs. Buy a gift card with a rewards credit card, get points back, and sell the card at a slight discount. The points more than cover the spread. This is legal but frowned upon, and card issuers actively close these loopholes. When they do, a flood of these codes hits the market at the same time, and that's a signal the loophole just got patched. I tracked this pattern on several credit card reward forums and could predict when a bank was going to close a program based on the sudden appearance of hundreds of similar codes. Cashback scraping is the newest category. Bots register for cashback websites, purchase gift cards through the portal, collect the cashback percentage, and sell the codes. The cashback rate usually ranges from two to twelve percent depending on the retailer and portal. The reseller sells the code at maybe five percent off face value, keeps the cashback, and profits on the gap. These codes have very low failure rates because they're legitimate purchases. The problem is they move slowly and the margins are thin. You need volume to make this work.
What Happens When You Try To Redeem
The moment of truth is always the same, and it's where most beginners lose money. You receive a code, go to the retailer's redemption page, enter it, and either the balance appears or an error message does. The error messages tell you more than you think. "Invalid code" means the code was never generated correctly, or someone tried it on the wrong platform. "Code already redeemed" means it was sold to multiple buyers, which happens when a fraudster lists the same code across five different forums simultaneously. "Card expired" is rare but occurs with older promotional cards that have short validity windows. "Balance unavailable due to fraud review" is the worst outcome, and it means the issuer has already flagged the card and frozen the funds pending investigation. I encountered a specific edge case that cost me $340 and taught me something important. A seller on a Discord server offered me a batch of five Target gift cards totaling $500 in face value for $350. The price was reasonable, the seller had a decent track record from mutual contacts, and I verified three of the five codes before buying the rest. Two failed with "already redeemed" errors. When I confronted the seller, he offered a partial refund and claimed those two must have been entered twice on my end. I didn't buy it, so I checked the Target gift card balance page directly using the card numbers rather than relying on the seller's word. Both cards had been fully redeemed about twelve minutes before the seller contacted me. Someone else had bought and used those exact codes hours earlier, and the seller was running a double-spend scheme by listing the same codes on multiple platforms at once.
The workaround I use now is simple but time consuming. I always verify the code on the official retailer website before confirming receipt on any marketplace. I never rely on third party balance checkers, because those are either outdated or controlled by other scammers. I also keep a spreadsheet tracking which sellers produce which failure rates, and I blacklist anyone who's ever sold me a double spent code. It slows things down, but the alternative is losing money repeatedly until someone reports you to the platform.
Red Flags That Separated From The Rest
Not everyone in this space is operating cleanly. Some people are outright criminals. Others are just reckless and lose money through ignorance. The ones who survive long enough to build real knowledge share a few behaviors that are worth tracking. Sellers who pressure for fast confirmation are always suspicious. Legitimate resellers want you to verify the code because they know it works. They have nothing to hide. Scammers want you to confirm before you've had time to test because confirmation locks in the sale and removes your ability to dispute it through the platform. Codes sold in bulk at deeper discounts than the market rate are usually compromised. If everyone else is selling a $100 card for $80 and someone lists one for $50, the code is almost certainly flagged or double spent. There's no legitimate reason to move product that cheaply unless you're trying to cash out before the card gets blocked.
Sellers with no transaction history who suddenly have large inventory are another warning sign. Either they're running a new scam, or they're a stolen account that someone just bought to resell quickly. I once bought from a seller who had five thousand dollars worth of codes available but only fourteen days of platform history. The codes worked for the first three transactions and then every subsequent code failed. By then the seller had disappeared and the platform had no way to recover the funds because the payment had already cleared.

Platform-Specific Dynamics
Different marketplaces attract different types of participants, and knowing the distinction matters. eBay has the most institutional oversight but also the highest volume of casual buyers who don't know what they're doing. The fees eat into margins, but the buyer protection is real, which means serious sellers stay because they want to build repeat business. Reddit communities operate on informal trust networks. Users build karma and reputation within specific subreddits over months or years. A seller with years of positive feedback in a dedicated subreddit is generally more reliable than a fresh account on eBay, but the consequences of a bad transaction are harsher because there's no formal dispute process. Chargebacks don't exist here. If you get scammed, you take the loss and move on. Discord is the current center of gravity for the higher volume trades. Servers require application or invitation, which filters out casual buyers and reduces some types of fraud but increases the sophistication of scams that do get through. The operators here understand the space well and will exploit any gap in your knowledge. I've seen experienced eBay resellers get burned on Discord because they brought eBay thinking to a Discord environment where the rules are completely different.
Telegram channels are the least regulated. Almost everything happens through direct payment, usually cryptocurrency. There's no middleman, no escrow, no dispute resolution. If the person on the other end decides to take your money and send nothing, you have no recourse. The codes you do receive tend to be cheaper because the risk premium is baked into the pricing, but the risk itself is enormous.
The Operational Reality
The math on this trade is brutal if you do it wrong and viable if you do it right. A typical successful reseller buys codes at 75 to 85 percent of face value and resells at 80 to 90 percent after fees and failures. The gross margin per card is maybe five to ten dollars. On a $1,000 volume of cards, that's fifty to a hundred dollars profit before factoring in the time, the failed transactions, and the occasional total loss from a bad seller. The failure rate across the entire market averages around twelve to fifteen percent for average buyers, meaning one in seven codes you purchase won't work. Experienced buyers who know how to vet sellers bring that down to maybe eight percent. People who don't bother vetting see failure rates above twenty five percent and usually quit within a month. Banks and card issuers are getting better at catching fraud faster. The window between a code being issued and being flagged has shrunk from days to hours in many cases. This compresses the time resellers have to move product and increases the importance of speed in the supply chain. A code that takes three days to sell is more likely to fail than one that sells within the first hour.
There's also the matter of platform bans. eBay suspends accounts for gift card trading regularly, usually in batches tied to fraud investigations. Discord servers get raided and shut down. Reddit communities get locked. The infrastructure that supports this trade is constantly degrading, which means the operators adapt or disappear. I've watched several well known sellers transition from one platform to another, rebuild their reputation from scratch, and start the cycle again.
What Beginners Get Wrong
The biggest mistake I see is assuming that a lower price always means a better deal. It doesn't. A code priced at forty percent of face value is not a bargain. It's a code that the seller knows is likely to fail or has already failed on someone else. These deep discount codes are usually the ones sold by fraudsters who know the code has a limited lifespan and are trying to move it before it dies. The second mistake is trusting balance verification tools that aren't official. Third party balance checkers claim to verify gift card status without redeeming the code, but most of them are run by other resellers feeding false data or harvesting codes for their own use. I learned this the hard way when a balance checker told me a code was active and valid, I purchased it, and it failed immediately. The checker had been fed outdated information from a code that had been redeemed hours earlier. The third mistake is not understanding the difference between a chargeback and a genuine discount. A legitimate reseller who bought a card during a promotion and is selling below face value will have transaction history, consistent pricing, and a willingness to let you verify the code. A fraudster will push for quick payment, offer inconsistent pricing, and resist any attempt at independent verification. The distinction matters more than the price.
The Legal Landscape
Purchasing a gift card code itself is not illegal. Selling one isn't either. What crosses the line is knowing the code was obtained through fraud and buying it anyway. That's receiving stolen property in most jurisdictions. The problem is proving knowledge, and that's why enforcement is spotty. Most people involved in this market don't know where the codes came from. They trust the seller. The seller doesn't know either, or doesn't care. The code works, the transaction completes, everyone moves on. Gift card issuers do pursue legal action occasionally, usually against organized resellers moving large volumes. Individual buyers are rarely targeted unless they're part of a coordinated scheme. The issuers' primary concern is reducing the fraud loss on their balance sheet, which they do through improved detection systems rather than prosecution. Chargeback systems exist precisely because this market creates friction. When a gift card is purchased with a stolen credit card, the cardholder's bank initiates a chargeback, the merchant loses the revenue, and the gift card balance gets voided. The code becomes worthless to whoever held it. The whole cycle repeats with the next stolen card. It's an arms race between fraudsters and issuers, and the buyers on the secondary market are collateral damage.

Practical Guidance If You Want To Participate
Start small. Buy one or two cards and learn the process before committing significant money. Use a payment method with buyer protection. Keep records of every transaction, including screenshots of the code, the balance verification, and any communication with the seller. This documentation is useless in most cases but can help if a platform investigation gets triggered. Build relationships with reliable sellers over time. Reputation in this space is earned slowly and lost instantly. A seller who delivers consistently for three months will earn your repeat business, and that relationship is worth more than saving a few dollars on a single transaction. I learned this the hard way when I skipped a trusted seller to save ten dollars on a deal with a new contact. The new contact's codes all failed, and I lost the money plus the opportunity to buy from the seller I'd been working with. Understand the failure modes before you enter. Know that some codes won't work and that losses are a normal part of the process. Budget for a twelve to fifteen percent failure rate and calculate your margins accordingly. If the math doesn't work with that built in, the trade isn't viable for you.
Don't romanticize this space. It's not a secret economy or a hacking community. It's a thin margin resale business built on fraud losses, with all the risks and stresses that come with dealing in compromised goods. The people who make money here treat it like a job, not an adventure. They track their numbers, manage their risk, and move on when the margins stop working.
