What Liabilities Actually Look Like When the Numbers Turn Mean
Most people think liabilities are just what's on the bottom half of a balance sheet. That's technically correct and practically useless. The hidden weight comes from obligations that don't show up cleanly in the totals. I spent three years doing credit analysis for a regional bank, and the deals that killed us weren't the ones with obvious debt. They were the ones with lease obligations buried in the footnotes, pension underfunding that looked fine on the face of the income statement, and revenue recognition practices that were legal until a customer defaulted and the entire contract structure unraveled. Liabilities in economics are broader than the accounting definition. An obligation is anything you owe that can be measured in money and has a due date or a triggering event. The market calls them contingent claims. You call them problems waiting to happen if your cash flow dips even slightly.
The Hidden Weight Of Liabilities Definition Economics How Obligations Shape Business Reality And Personal Finance
The formal definition is straightforward enough. A liability is a present obligation arising from past events, the settlement of which is expected to result in an outflow of resources. IAS 37 and ASC 450 both say roughly the same thing with different levels of bureaucracy. What they don't tell you is that probability thresholds matter more than the definition itself. A contingent liability only hits the balance sheet when the outflow is probable and estimable. Probable means roughly a 70 to 80 percent chance depending on which framework you're reading. Below that, you footnote it. Below 40 percent, you might not even mention it unless you're being thorough. Here's what nobody explains in the textbooks: the distinction between a recognized liability and a contingent one is where the real danger lives. Recognized liabilities are boring. You know about them. The contingent ones are the ones that surprise you during a downturn because they were always there, just hidden behind a probability label that management felt comfortable using. I once worked a deal where a manufacturing company looked perfectly leveraged by standard metrics. Debt to EBITDA was under two times. Current ratio was above 1.5. Clean on the surface. Then I dug into the environmental remediation footnote. The company had a pending EPA investigation and a potential cleanup obligation they classified as reasonably possible rather than probable. That pushed it to footnote disclosure instead of balance sheet recognition. Two years later, the EPA settlement came in at $47 million. The company had to restate earnings, breach a covenant, and restructure. All because someone decided the probability threshold wasn't met.
The workaround I developed was simple and it still applies anywhere I look now. Every time I pull a financial statement, I go straight to the footnotes before I touch the ratios. Specifically, I look for section titles like commitments and contingencies, lease obligations, pensions and post-retirement benefits, and litigation. That section alone tells you more about the true obligation load than any leverage ratio ever will. It takes about five minutes and it catches things that standard screens miss 90 percent of the time.
Get the Full Details

How Obligations Actually Shape Business Decisions
Cash flow coverage ratios matter more than leverage ratios when you're assessing whether a company can survive a shock. Debt service coverage ratio, or DSCR, measures operating cash flow against mandatory debt payments. A DSCR below 1.2 is where things get uncomfortable for most lenders. Below 1.0 and you're burning through reserves or rolling debt just to stay current. Interest coverage ratio tells you something different. It measures earnings before interest and taxes against interest expense. High EBITDA with a thin interest coverage ratio usually means the company is carrying more principal than the interest numbers suggest. This happens a lot in capital-intensive businesses like telecom and infrastructure. The interest looks manageable because the debt is long-dated and rates are low. The principal repayment schedule is the real killer that sits quietly in the maturity wall. Operating leases used to be the favorite hiding spot for off-balance-sheet obligations. Before ASC 842 and IFRS 16 took effect in 2019 and 2020 respectively, companies could lease equipment, buildings, and vehicles without putting those obligations on the balance sheet. The capital was effectively borrowed to pay rent, but it showed up as an operating expense instead of debt. This distorted leverage metrics across entire sectors. Retail and airlines were the worst offenders.
Now that leases are capitalized, the game has shifted rather than ended. Companies found other places to hide obligations. Service contracts with minimum purchase requirements. Take-or-pay agreements in energy and logistics. Long-term supply contracts with penalty clauses for early termination. These create economic obligations that behave exactly like debt even though they don't carry interest. During a stress scenario, they still require cash outflows on schedule. The practical implication is that your analysis of obligations needs to look beyond the balance sheet entirely. Adjusted debt should include capitalized operating leases, minimum lease payments beyond the current period, significant service commitments with fixed terms, and pension funding shortfalls. This gives you a picture of what the company actually owes versus what the accounting framework permits it to conceal.
The Personal Finance Side That Nobody Talks About
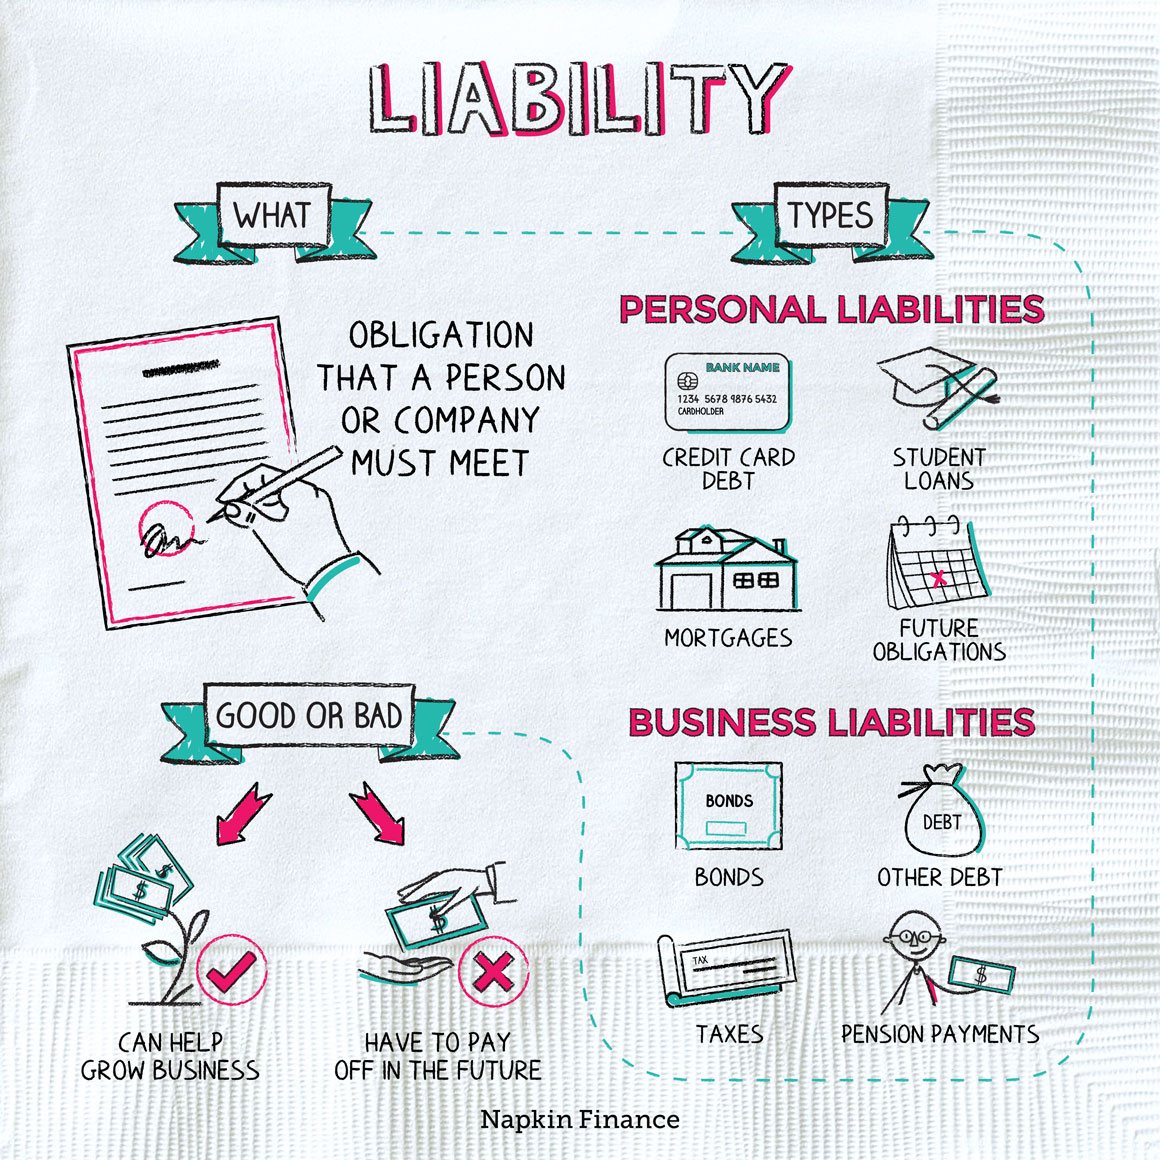
Personal liabilities operate under the same principles but with less transparency and more emotional decision-making. Most household debt analysis stops at the debt to income ratio. That's inadequate. What matters is the debt service ratio including all obligatory payments against net take-home income. A mortgage payment, car payment, student loan, minimum credit card payments, insurance premiums that are technically Obligatory, and any alimony or child support all count as debt service. When that total exceeds 43 percent of gross income, you hit the qualified mortgage threshold in the United States. Exceed it comfortably and you become vulnerable to any income disruption. One missed paycheck becomes a cascade. The hidden weight in personal finance usually comes from obligations people don't count. Subscription services that auto-renew. Insurance premiums paid annually but budgeted monthly. Minimum payments on credit cards that compound because people only pay the minimum. And the big one that catches everyone: lines of credit that are available but unused. Available credit doesn't create an obligation until you use it, but it does create a behavioral temptation that often leads to actual debt. I've seen borrowers treat home equity lines like additional income rather than a liability option. That mindset turns a tool into a trap within months.
Common Pitfalls in Liability Analysis
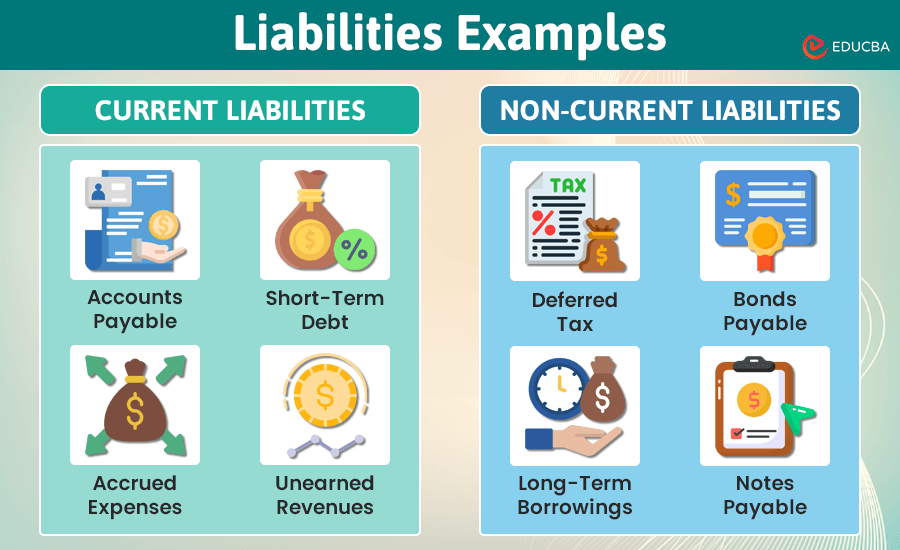
The biggest mistake beginners make is treating all liabilities the same. Not all debt carries equal weight. Secured debt has different risk characteristics than unsecured debt. Short-term debt refinances constantly and creates rollover risk. Long-term debt locks in rates but may contain call provisions that force refinancing at worse terms. Operating liabilities like accounts payable are generally flexible. Trade creditors will negotiate terms if you're a good relationship rather than calling for immediate payment. Financial debt does not offer that flexibility. Another pitfall is ignoring the currency and jurisdiction of obligations. A company reporting in USD with EUR-denominated debt faces translation risk that doesn't show up in the obligation amount until the exchange rate moves. A subsidiary operating in an emerging market with local currency revenue but parent-company debt in a hard currency creates a structural mismatch that can destroy margins overnight during a currency crisis. This happened repeatedly in Latin America during the 2018 period and again during the 2022 dollar strengthening cycle. People also overlook the timing mismatch between obligation maturity and asset liquidity. A company might have strong total assets but those assets are illiquid. Real estate, specialized machinery, and intellectual property don't convert to cash quickly during a stress event. Meanwhile, the debt payments are due monthly. This maturity and liquidity mismatch is what turns a solvent company into an insolvent one during a crisis. Solvency is about total assets versus total liabilities. Liquidity is about whether you can meet payments right now. They are completely different questions.
Advanced Nuances That Separate Experienced Analysts From Everyone Else
Revenue recognition create implicit liabilities that rarely show up as debt. When a company recognizes revenue upfront for a multi-year service contract, it has an obligation to deliver future performance. If it can't deliver, it owes refunds or faces litigation. The revenue looks great today. The liability is future performance risk. Enron built its entire fraud around this mechanism. You don't need that extreme to see it in normal business. Software companies with large upfront licenses and minimal ongoing support obligations sometimes book revenue that doesn't match their actual service commitment. The gap between recognized revenue and remaining performance obligations is disclosed in the footnotes but ignored by most investors. Another advanced concept is the liability discount rate. When companies measure long-term obligations like pension benefits or asbestos claims, they discount future cash flows to present value. The discount rate assumption changes the liability amount significantly. A one percentage point change in the discount rate can alter a pension obligation by 10 to 15 percent depending on the duration of the cash flows. Management often selects the discount rate that produces the most favorable liability number within the allowable range. This is legal accounting optimization, not fraud, but it still distorts the true obligation picture. The workaround for discount rate manipulation is to stress test the liability using alternative discount rates. Run the numbers at a rate one percentage point higher and one percentage point lower. The range of outcomes reveals how sensitive the reported obligation is to a single assumption. This takes ten minutes and provides more insight than reading the entire footnote section.
Where This Framework Breaks Down
The liability analysis framework I've described has real limitations. It works well for established companies with audited financial statements and reasonable disclosure practices. It breaks down for start-ups with minimal track records, private companies with limited disclosure requirements, and entities in jurisdictions with weak accounting enforcement. In those cases, the obligation picture is genuinely opaque and no amount of footnote diving will resolve the uncertainty. The framework also assumes that obligations can be quantified. Some obligations are structural and cultural rather than contractual. A company with a history of voluntary restructuring payments to suppliers creates an implicit obligation even when no contract requires it. Dividends that have been paid consistently for decades create an expectation that becomes a de facto obligation even if legally discretionary. These invisible liabilities don't appear anywhere in the financial statements but they affect cash flow behavior in predictable ways. When the standard framework fails, the alternative is scenario-based obligation modeling. Instead of trying to find the exact liability amount, you model cash flow under different stress conditions and observe where obligations create binding constraints. This is less precise but often more useful than a false sense of accuracy from incomplete data.
Practical Steps for Applying This Today
Start with whichever financial statement you have access to. Pull the liability section and categorize each line item by type and maturity. Separate financial debt from operating obligations. Separate current from non-current. Then go to the footnotes and locate the commitments and contingencies section. Read it thoroughly. Look for lease obligations, pension assumptions, litigation exposure, and contractual commitments. Calculate adjusted debt by adding capitalized leases and significant off-balance-sheet obligations to reported debt. Calculate adjusted leverage by dividing that number by EBITDA or operating cash flow depending on what's more appropriate for the industry. Compare the adjusted figure to the reported figure. The gap between them is the hidden weight. In well-disciplined companies, the gap is small. In aggressive or complex organizations, it can be substantial. For personal finance, list every obligatory monthly payment including minimum credit card payments. Divide the total by net monthly income. If the result exceeds 40 percent, you have limited cushion for unexpected obligations or income disruption. The goal isn't to eliminate all liabilities. It's to ensure the obligation load doesn't create fragility in your financial structure. A moderate level of well-managed debt is normal and often necessary. The problem arises when obligations grow faster than the capacity to service them.
The concept behind The Hidden Weight Of Liabilities Definition Economics How Obligations Shape Business Reality And Personal Finance is simply that what you owe determines what you can do more than what you own. Assets can appreciate or depreciate. Obligations are fixed in amount and schedule. They don't care about your revenue cycle or your market conditions. They come due regardless. Understanding that asymmetry is the foundation of practical financial analysis whether you're evaluating a corporation or your own budget.