Reading Open Interest Like Something Other Than A Fancy Chart
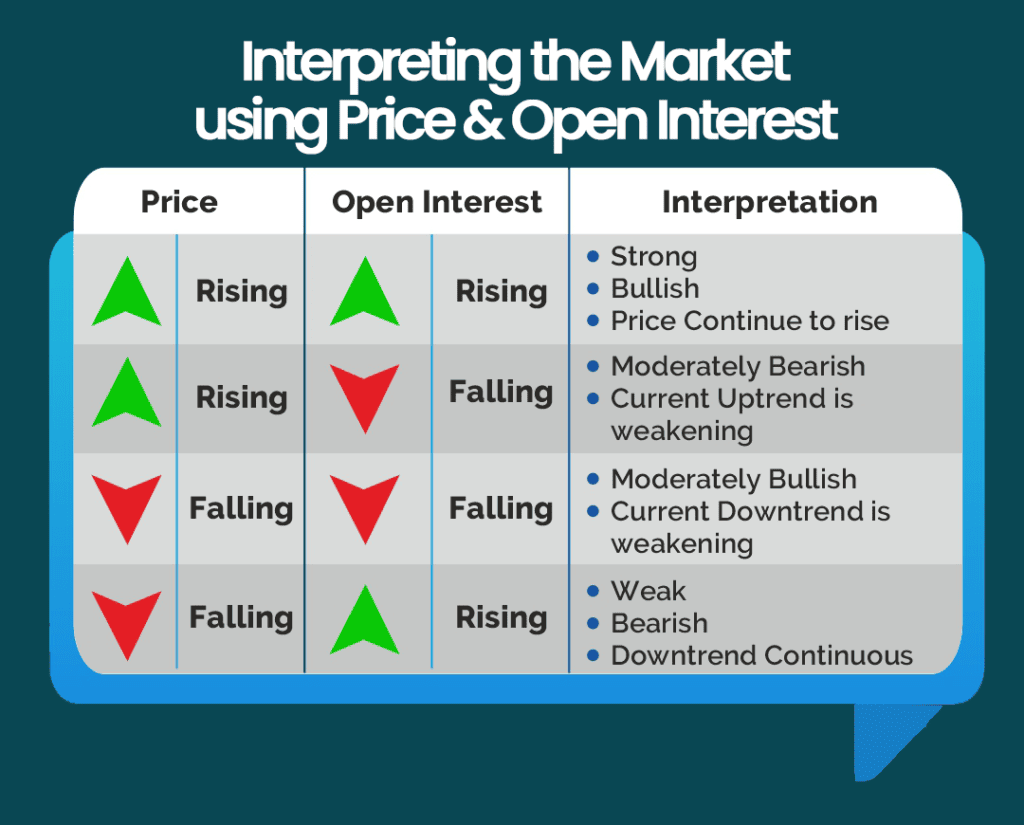
Open interest is the total number of outstanding derivative contracts that haven't been settled. Futures and options both report it. It tells you whether money is flowing into or out of a particular contract. Most people treat it as a secondary confirmation tool, which isn't wrong, but they also mostly use it wrong. The raw open interest number means almost nothing on its own. What matters is the direction it's moving combined with price action. When open interest rises while price rises, new money is supporting the trend. Short sellers are getting covered. Longs are entering. The move has fuel behind it. When open interest climbs while price falls, new shorts are piling in and the downtrend has fresh ammunition. That's the basic mechanic. Where people trip up is assuming open interest always confirms price. It doesn't. You'll see open interest surge on expiration week when people are rolling positions. The number goes up but nobody's taking a directional bet. They're just extending their exposure to next month's contract. If you're trading based on that open interest spike, you'll get caught in a sideways chop that lasts three days and drains your margin.
The Mechanics Behind The Numbers
Here's how it actually works under the hood. Every futures or options contract is a two-sided agreement. One party is long, one is short. Open interest represents the total count of these pairs. When a new buyer and a new seller meet and both open fresh positions, open interest increases by one contract. When an existing long closes by selling to an existing short who is closing, open interest decreases. When a new buyer takes over an existing short's position through assignment or offset, open interest stays flat. This distinction between new money and closing money is where the signal lives. New open interest means new conviction. Closing interest means people are bailing. The problem is that retail traders rarely see which type of activity is driving the change in real time. Data vendors show you the net change, not the breakdown. You have to infer it from price behavior. I spent roughly eighteen months working with CME data feeds before I stopped treating open interest as a standalone indicator. The breakthrough came when I started tracking the difference between daily open interest changes and implied volatility shifts across the same expiration cycle. Normally these move independently, but during genuine institutional positioning they start correlating. When OI jumps and IV compresses at the same time, someone with deep pockets is building a directional position and hedging it cheaply. That's not a retail pattern.
Options Market Open Interest Is A Different Beast
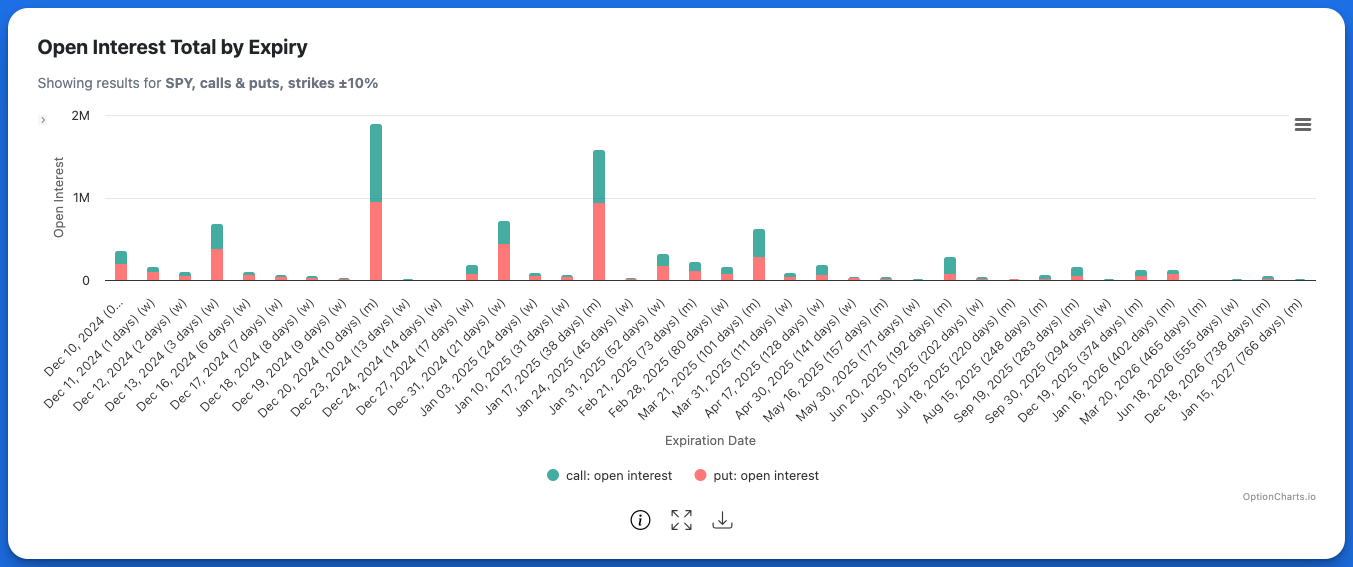
Futures open interest is cleaner because it's centralized. Options open interest is reported by individual exchanges and then aggregated, which introduces lag and occasional double-counting depending on your data source. The CBOE publishes aggregate options OI daily, but if you need intraday granularity you're looking at different vendor feeds with different update schedules. Call and put open interest by strike creates a map of where market participants think price might land. High call OI at a specific strike acts as a magnet or a wall depending on whether the price is below or above it. This isn't a guaranteed theory. It's a probabilistic one based on how market makers hedge. When call writers need to delta-hedge near expiration, they buy the underlying. That creates buying pressure. Put writers do the opposite. The result is often a self-reinforcing loop around heavily traded strikes. The counter-intuitive part nobody teaches is that extremely high put open interest at a strike below current price doesn't necessarily mean bearish sentiment. It often means institutional protection. Large holders buy puts as portfolio insurance. The OI stays elevated even if their view on direction hasn't changed. A beginner sees massive put OI and assumes everyone's betting on a crash. Usually the opposite is true. The puts are being held, not traded actively for speculation.
Get the Full Details

A Practical Workaround I Use
My main friction point has always been getting clean, consolidated open interest data across multiple asset classes without paying five figures a year for a Bloomberg terminal. I ended up building a simple aggregation script that pulls from free CME and CBOE datasets, normalizes the timestamp differences, and flags anomalies where the reported OI change exceeds three standard deviations from the rolling thirty-day average. The script runs on a schedule and outputs a daily spreadsheet. The real value isn't the alert itself. It's what comes after. When the anomaly flag fires, I cross-reference it with volume profiles and options flow data from the same window. Usually the spike correlates with a specific large trade or roll that explains the movement. If it doesn't correlate with anything obvious, that's when I pay closer attention. Unexplained OI spikes tend to precede volatility expansions within two to five trading sessions, based on my backtesting across S&P 500 futures and E-mini Nasdaq over the past six years.
Limitations And Where It Fails Completely
Open interest data has structural weaknesses that most guides gloss over. First, it's backward-looking. The OI reported today reflects positions opened or closed yesterday. By the time you see a meaningful change, the market may have already priced it in. Second, exchange-specific reporting means you can miss cross-listed contracts. A single underlying like crude oil will have open interest spread across WTI, Brent, and various regional exchanges. Aggregating them manually is error-prone. Third, during expiration weeks, open interest data becomes nearly useless for direction because the sheer volume of rollover activity drowns out genuine positioning signals. For expiration week analysis, I switch to tracking individual trade flow and block trades instead. Retail platforms don't give you block trade data, but if you have access to a CME market depth feed or services like SpotGamma or Cheddar Flow, the institutional order flow becomes visible. It costs money though. The free alternative is watching the roll spread between the front month and second month. Widening spreads often signal where smart money is positioning, even if the OI numbers themselves look noisy. Also worth noting: open interest works best on liquid contracts. For thinly traded options or futures with low volume, the OI signal gets distorted by a handful of large positions. A single institutional trade can swing the daily OI change by twenty percent on a contract that only has ten thousand open contracts total. In those cases, the metric is noise, not signal. Stick to contracts where daily OI changes are under five percent of total open interest unless you specifically understand the participant base for that contract.
How To Start Using It Today
Pick one liquid futures contract or one major index option chain. Don't try to track everything at once. S&P 500 E-mini futures or SPX options work fine for this. Pull the daily open interest number for thirty consecutive days. Note the price direction and the OI direction on each day. Mark instances where OI rose with price, rose with falling price, fell with rising price, or fell with falling price. After thirty days you'll have a basic sense of how that particular contract behaves. Then add implied volatility to the mix. Track whether OI and IV move together or diverge. This exercise takes about forty minutes to set up and maybe ten minutes per day afterward. It replaces the guesswork of thinking OI alone predicts direction. You'll start seeing patterns specific to each contract. What works for ES won't necessarily work for CL or ZB. Each has different participant profiles and different rollover behaviors. The metric itself doesn't change, but its reliability does depending on what you're looking at.