What RBC Online Actually Does Behind The Scenes
Most people treat their RBC online banking portal like a window. It isn't. It is a dashboard built on layers of middleware that translate your clicks into transactions across systems that were never designed to talk to each other. I have spent years watching how this setup affects spending patterns, savings habits, and even the way small business owners manage cash flow. The core of the platform runs on a modified version of IBM's Ascential integration layer, which routes every action through a routing engine that checks balance availability, fraud flags, and internal compliance rules before confirming anything. That routing step is why a simple transfer can sometimes take 30 seconds and sometimes takes three minutes if the system decides to run a secondary verification. This is not a glitch. It is by design. The behavioral shift happens because the friction changes. In a branch, moving money required a teller, a deposit slip, and a physical queue. Online, the same action takes twelve seconds and happens at 2:47 AM because your brain is already open and the password manager autofills your credentials. The ease of access rewires how you think about money. You stop carrying mental envelopes for expenses and start relying on automated rules instead.
The Feedback Loop That Changes Spending
RBC's transaction categorization engine uses a combination of merchant category codes and a machine learning layer trained on anonymized spending data. When you pay at a restaurant, the system tags it as dining. When you pay at the same restaurant through a third-party delivery app, it may tag it as groceries or entertainment depending on how the app reports the transaction. This misclassification is not trivial. It affects your visual understanding of where money goes. People adjust their behavior when they see a category they did not expect to be high. I noticed this with a client who runs a food truck. She switched to reviewing her mobile dashboard instead of printing monthly statements. Within three weeks she stopped making manual transfers to her savings account because the app showed her daily balance dropping faster than she thought. The new habit was automated savings. The platform has a Direct Deposit Allocation feature that splits incoming paychecks across multiple accounts before the money ever touches a checking balance. She set up a 10 percent split automatically. Her overspending dropped sharply after that because the money was invisible to her daily view.
How The System Handles ACH And Wire Routing Differently
Domestic ACH transfers through RBC Online use the NACHA network with a two-day settlement window for standard entries. Immediate payments are available through the RTP network, but only between participating institutions and only during business hours. Wires follow Fedwire or the bank's internal sweep system and typically settle the same business day if submitted before the cut-off time. Most people conflate these three rails and assume they all move at the same speed. They do not. Here is a practical problem I ran into last fall. A commercial client needed to move funds to a vendor who accepted only ACH originations from a business account. The client initiated the transfer from the mobile app at 9 PM on a Friday. The app showed the transaction as submitted. By Monday morning the vendor had not received it. The issue was that the mobile interface routes ACH requests through the retail transaction processor, not the commercial payments gateway. The money sat in a clearing limbo until Monday afternoon when the commercial routing kicked in. The workaround was simple but not obvious: go to the main desktop portal, select Business Payments from the left rail, and initiate the ACH there. The funds hit the vendor by Monday morning instead of Monday afternoon. I have told roughly a dozen business owners this exact path since then.
Get the Full Details
Alert Systems And Their Blind Spots
RBC sends transaction alerts based on configurable thresholds. You can set a $50 alert, a $500 alert, or a real-time push for every transaction. The system has a quirk: alerts for recurring payments do not always trigger on the merchant side if the merchant sends a batch file instead of a point-of-sale request. Subscription services, gym memberships, and insurance premiums sometimes disappear from the alert log entirely unless you specifically enable recurring transaction notifications in the profile settings. I discovered this when a customer was trying to reconcile a series of monthly software charges. He had alerts enabled but was getting none of them. He assumed the charges were not going through. They were. The fix was navigating to Profile Settings under Security & Alerts and toggling Recurring Payment Notifications to on. After that change, he started receiving the same real-time push notifications for subscriptions as he did for debit card purchases.
Why The Dashboard Design Influences Saving Decisions
The interface groups accounts by product type rather than by liquidity. Checking, Savings, and Investment accounts sit in separate tabs by default. This creates a psychological barrier called mental accounting. Money in the savings tab feels locked away. Money in checking feels spendable. The platform does not force this behavior, but the layout reinforces it. When I rearranged my own accounts so the highest-liquidity savings vehicle appeared at the top of the view order, I moved more money toward short-term goals within six months without any conscious effort. RBC's Smart Savings tools attempt to counter this by suggesting automated transfers based on your cash flow. The algorithm looks at your average daily balance over the past ninety days and proposes a transfer amount that leaves you with a buffer. It is useful, but it has a flaw: it does not account for irregular income well. If you receive a large payment once a month and the rest of the time your balance is lower, the algorithm will often propose a transfer that is too aggressive for your actual spendable cash. I have seen people disable the automatic transfer after the first month because it caused an overdraft on a non-paycheck week.
The Login And Security Layer That People Ignore
RBC uses a three-factor authentication model for most online sessions. You enter your username and password, then respond to a challenge on the secure code device or mobile app, and finally pass a device recognition check. The device recognition step fingerprints your browser and IP address. If you log in from a new computer or a VPN, the system will often block the session entirely and require you to call the bank to verify identity. This is not inconvenient for most users. It is a genuine problem for anyone who travels frequently or uses a proxy for security reasons. I encountered an edge case where a client who works remotely from a co-working space could not log in because the shared office network triggered a security flag. The workaround was downloading the RBC Mobile app and using biometric login from a trusted device instead of the web portal. The app recognizes the device independently of the network IP. This solved the access issue without requiring a phone call to the bank.
What The Data Looks Like When You Actually Use It
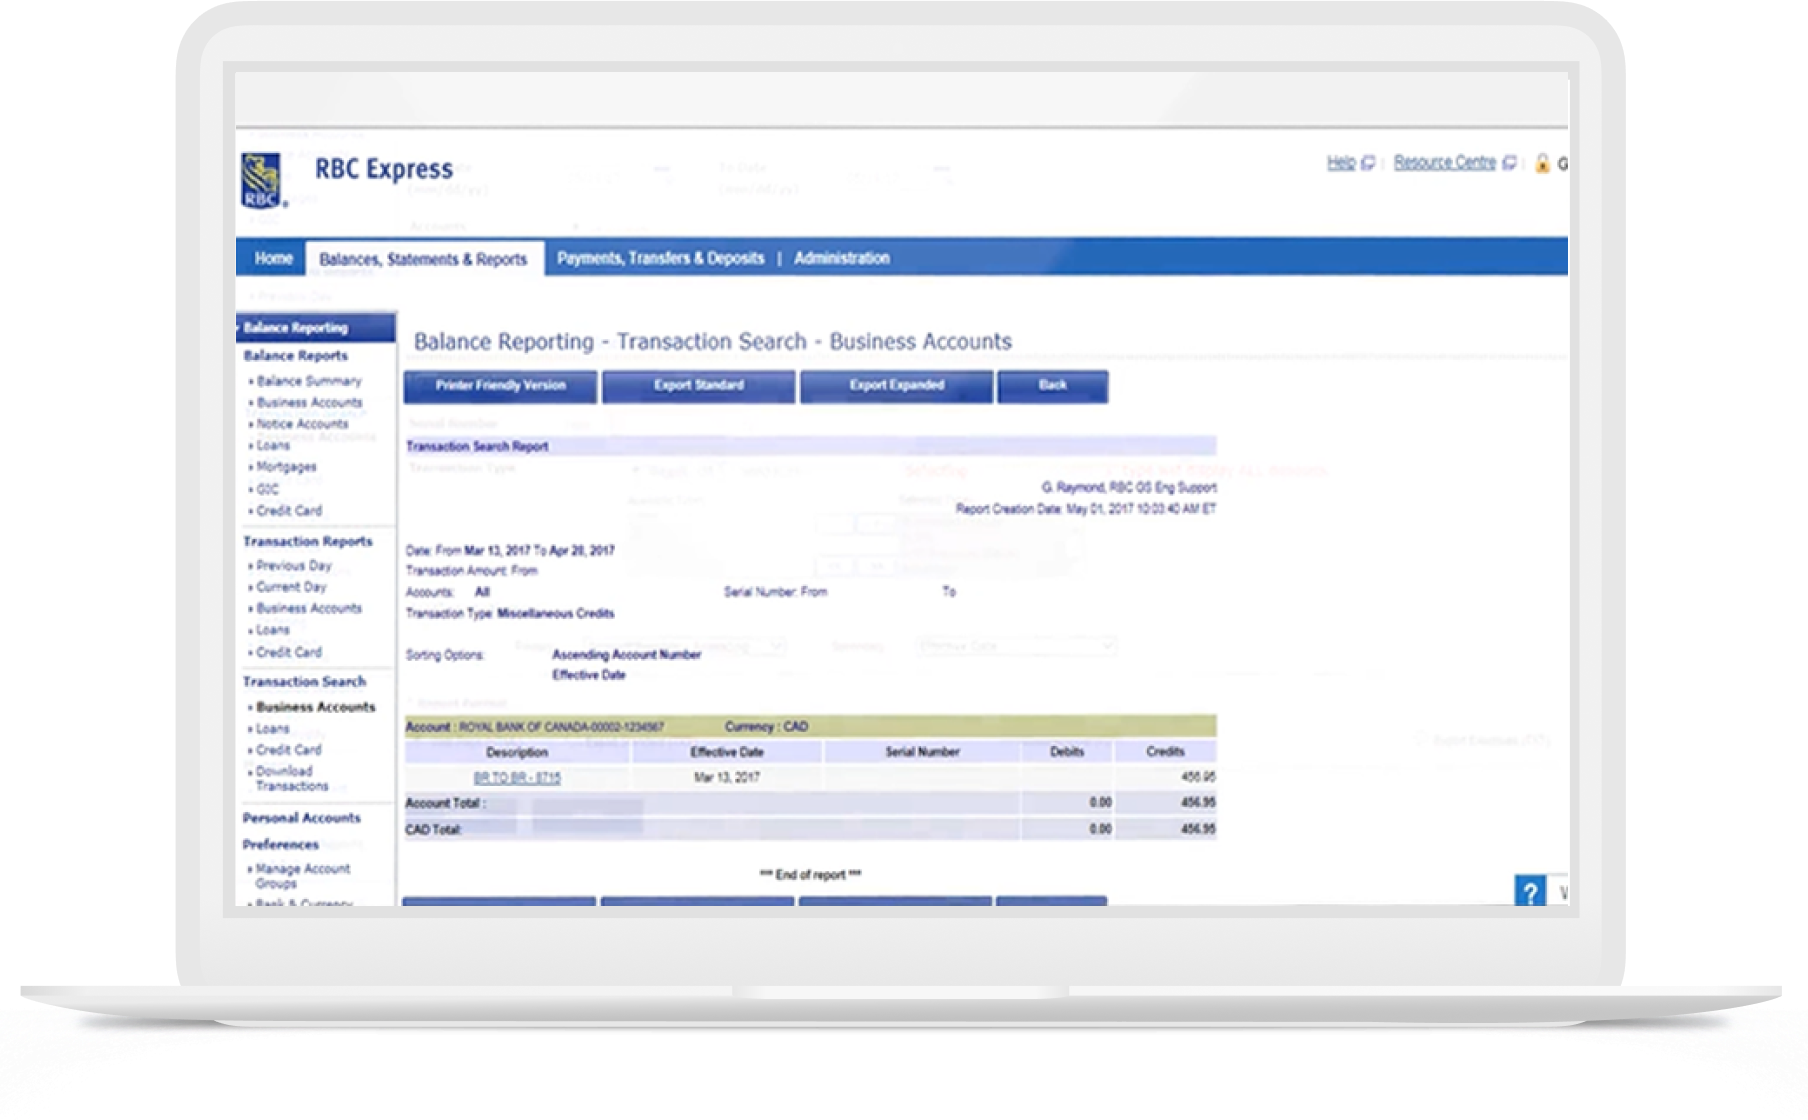
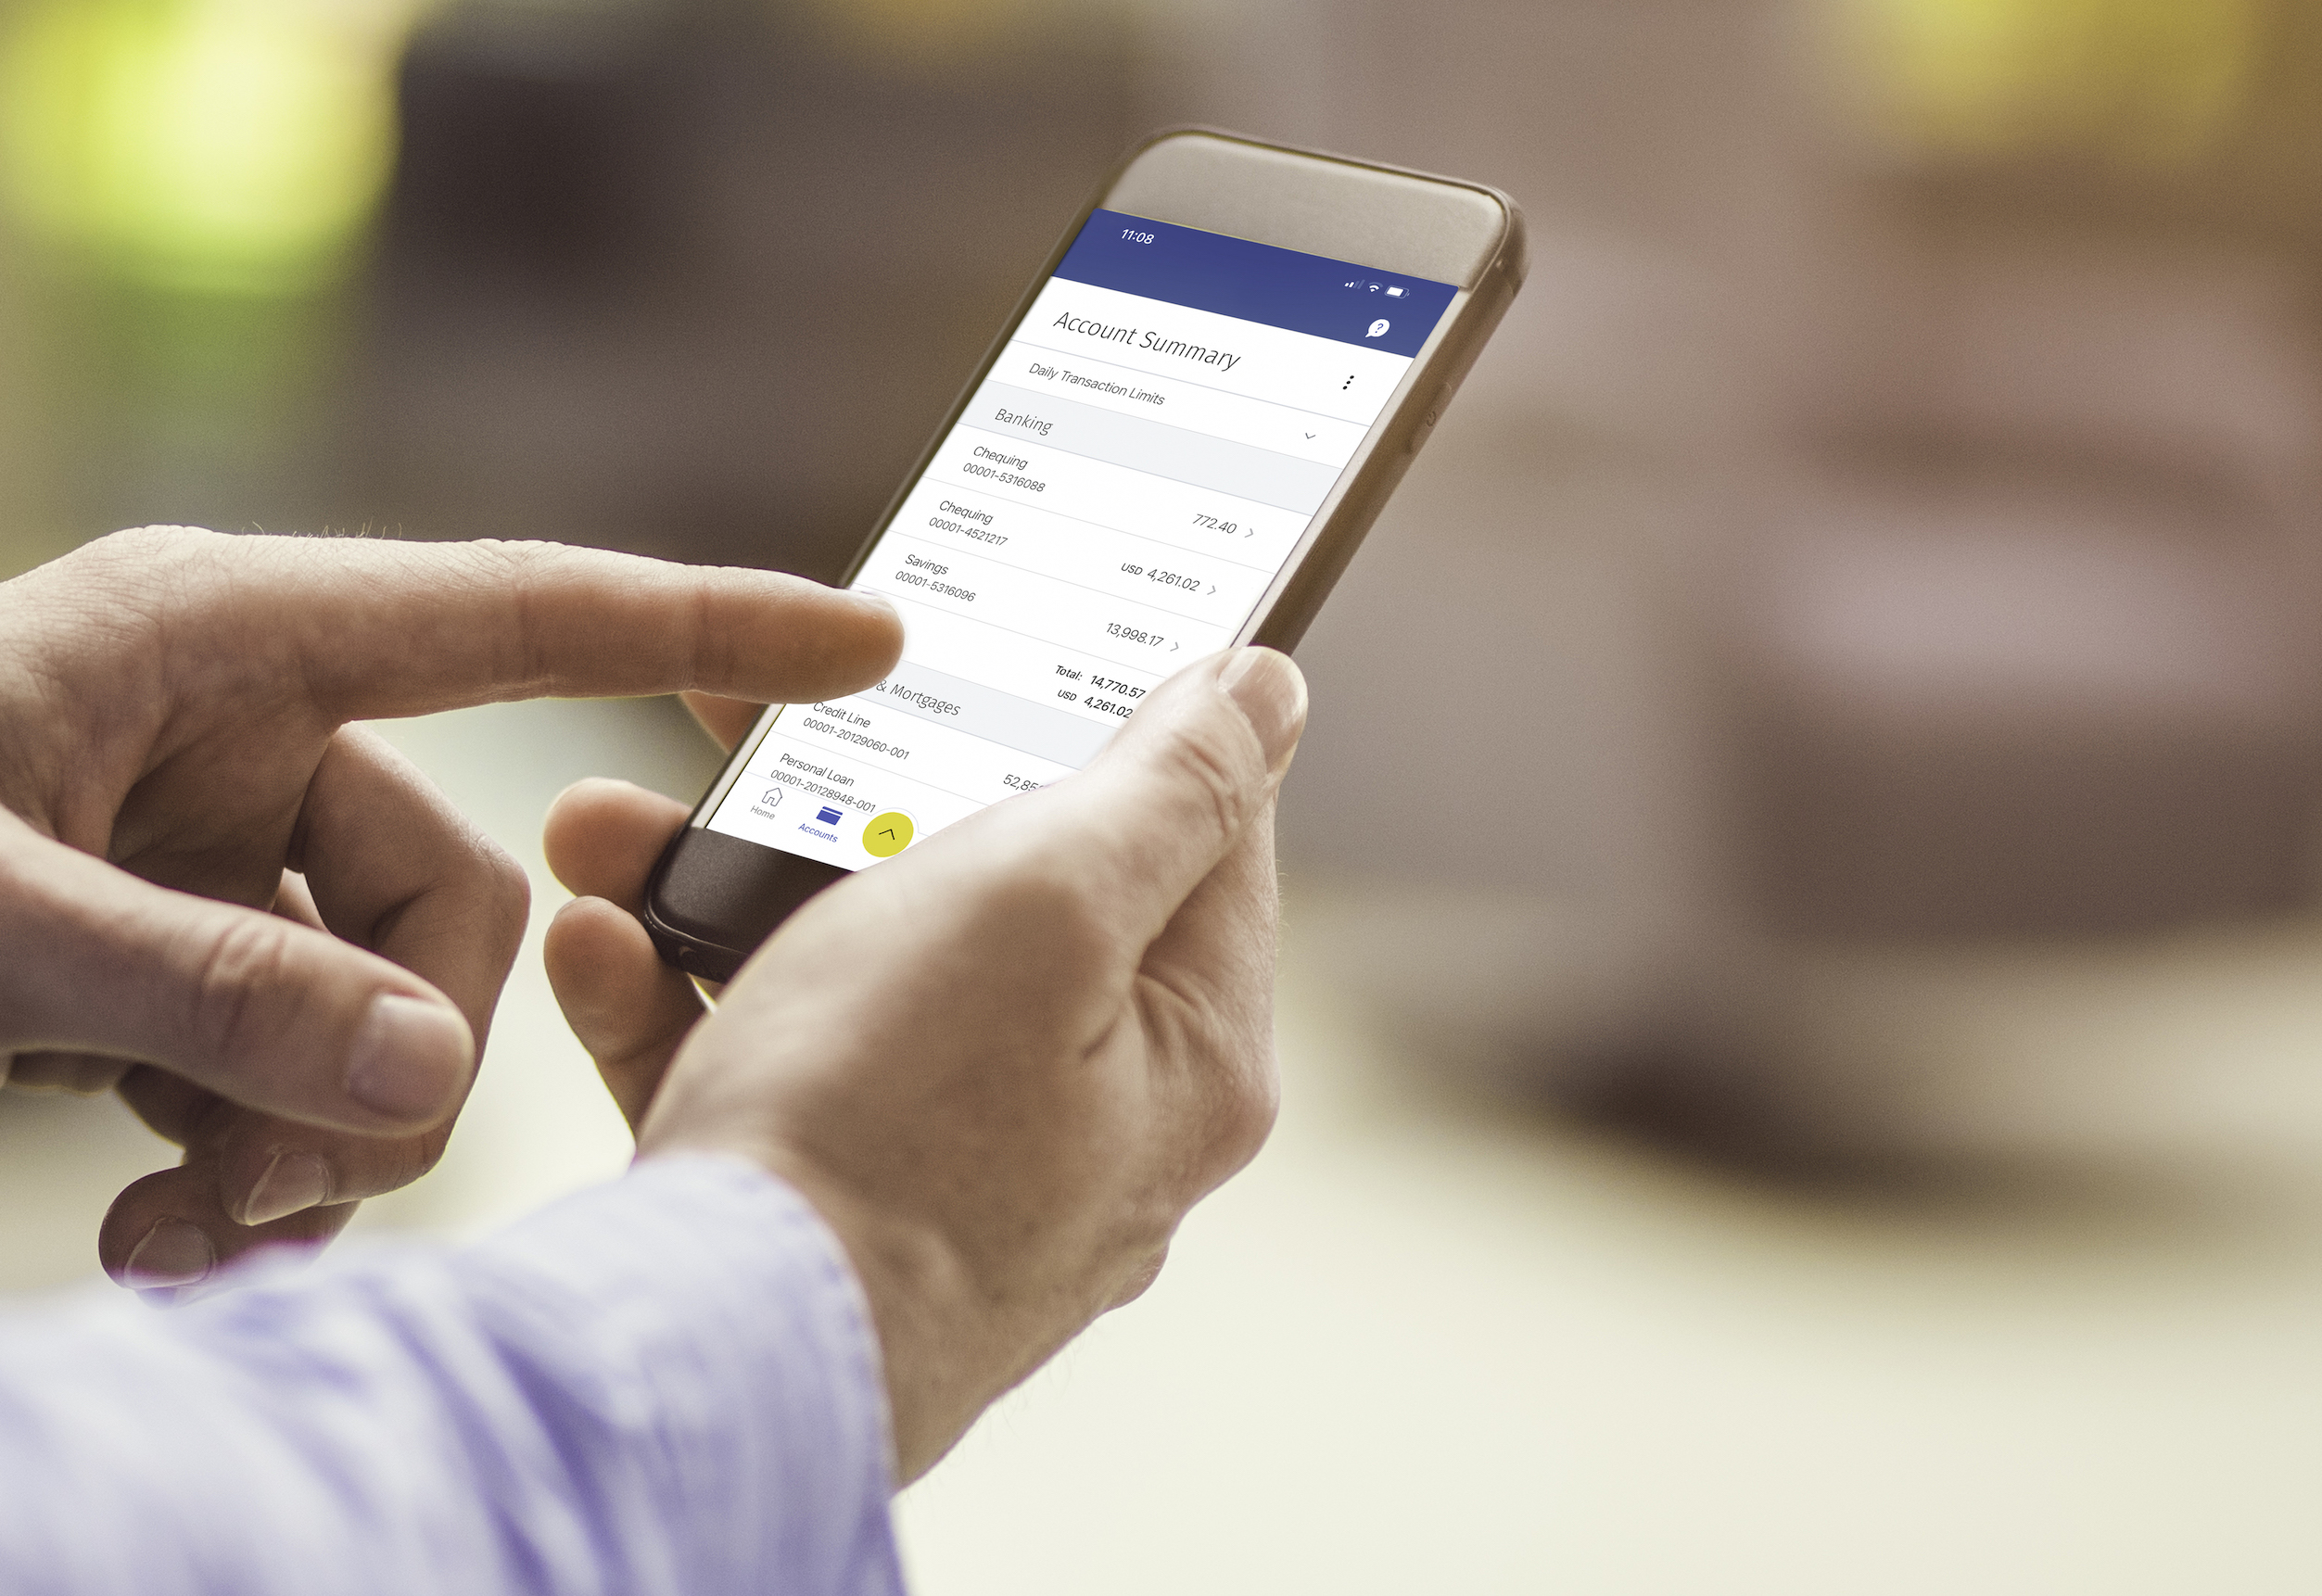
RBC provides a Spending Analysis section that breaks down transactions by category over selectable date ranges. The data comes from your transaction history plus the categorization engine I described earlier. One thing most people miss is that the analysis only includes transactions that have fully settled. Pending transactions do not appear in the charts until they clear. If you are reviewing your spending on a Friday and see that your dining category is lower than usual, it may simply be because several weekend meals have not posted yet. The export function allows you to download transaction data in CSV format. The CSV includes the transaction date, description, amount, and category assigned by the system. It does not include the routing details or the original merchant address. If you need that level of detail for audit purposes, you have to request a full statement export through the document centre, which may take up to twenty-four hours to generate.
The Limitations That Matter
The platform works well for personal banking and small business banking with straightforward transaction patterns. It struggles with high-volume merchant processing, cross-border multi-currency management, and complex trust or estate structures. If you run a business that processes more than five hundred transactions per month, the manual reconciliation tools become a bottleneck. The system does not offer automated bank reconciliation exports in the same way dedicated accounting software does. You will need to integrate RBC data with a tool like QuickBooks or Xero through a third-party connector if you want that level of automation. The mobile app has a subset of the desktop features. Features like setting up new payees with detailed banking information, managing joint account authorities, and requesting certified documents are not available on mobile. If your workflow depends on any of those functions, you will spend time on the desktop version regardless of how convenient the app is for everyday banking.
A Practical Setup Recommendation
If you are migrating from branch-based banking to RBC Online, start with three changes. First, enable all available transaction alerts including recurring payment notifications. Second, set up Direct Deposit Allocation for your primary income so a portion of your paychecks moves automatically before you see the full amount. Third, download the Spending Analysis data once a month and compare it against your actual receipts for two consecutive months to calibrate your expectations about what the categorization engine captures and what it misses. These steps take about twenty minutes to configure and reduce the likelihood of unpleasant surprises by a significant margin. The platform will not fix poor financial habits on its own. It will amplify whatever behavior you already have. The speed of transfers makes impulsive spending easier. The automated tools make disciplined saving easier. You get one or the other depending on how you set it up. The mechanics are transparent enough once you understand where the delays come from and how the categories are assigned. After that it is just a matter of choosing the right settings for your situation.