Understanding Beta in Real Trading
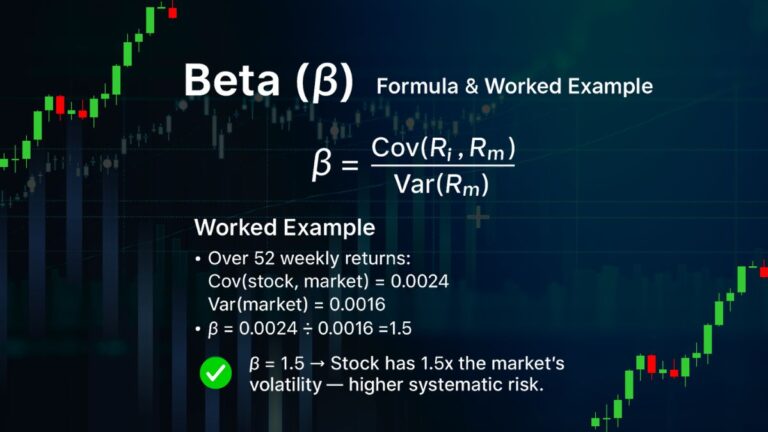
Beta is just a number that tells you how much a stock moves relative to the overall market. Most people treat it like a crystal ball. It isn't. I learned that the hard way during the 2022 downturn when my entire portfolio was sitting on high-beta tech names that dropped 40% while the S&P only fell 19%. I kept expecting mean reversion. It didn't come fast enough. Here's the calculation without the textbook preamble. You take the covariance of the stock's returns with the market's returns and divide by the variance of the market's returns. In Excel terms that's COVARIANCE.S between your asset and SPY, divided by VAR.S of SPY. I usually pull 60 months of data because short windows give you garbage numbers during regime shifts. A 24-month window during 2020 showed betas of 0.6 for several stocks that immediately jumped to 1.8 when inflation hit. That discrepancy wrecked my positioning initially. The formula itself:
Beta = Covariance(Stock, Market) / Variance(Market) But here's what nobody tells you at the beginner level. Beta is backward-looking. It measures how the stock behaved, not how it will behave. That gap between historical and future beta is where most retail traders get burned. I started cross-referencing trailing twelve-month beta with the betas from the prior two years. When they diverged by more than 0.3, I treated the number as suspect and weighted recent data more heavily. That adjustment alone kept me from being overweight in a few names that suddenly became riskier. Some counter-intuitive things about beta that took me years to absorb. A stock can have a beta below 1 and still obliterate you if the correlation with the market breaks down. I held a utilities position for three years with a 0.4 beta and thought I was diversified. When rate hikes accelerated in early 2023, that utility stock fell 22% alongside the Nasdaq instead of moving independently. Beta doesn't account for idiosyncratic risk. It only measures systematic co-movement.
Another thing: beta changes depending on which market index you use. Compare a stock against the S&P 500 versus comparing it against the Russell 2000 and you get different numbers. I switched one of my positions from a S&P-centric beta to an equal-weight index beta and the number went from 1.1 to 0.7. That difference changed my sizing decision entirely. Pick your benchmark based on where the capital actually flows, not what your broker shows by default. Now for the practical application. I use beta in three specific scenarios. First, when building a portfolio, I calculate the weighted average beta so I know my exposure before a macro event hits. Second, I use it for options hedging, specifically when deciding between buying puts versus selling calls. A stock with a beta of 1.5 needs roughly half the put notional compared to a beta of 0.8 to achieve the same dollar hedge. Third, I use it to adjust position sizing for high-volatility names. I scale down positions on anything above 1.3 beta unless I have a conviction trade set up, and even then I keep it under 5% of the portfolio. There are situations where beta fails completely and you need something else. Small-cap biotech stocks with binary event risk, stocks caught in earnings collapses, and sector rotations where the beta flips negative. I ran into this with a semiconductors name that had a stable 1.4 beta for eighteen months, then went to 0.3 after a major customer announcement. The beta wasn't wrong historically, it was just irrelevant going forward. In those cases I switch to tracking the stock's own realized volatility instead of market beta. It's messier but it actually tells you something about the position's behavior in that moment.
Get the Full Details
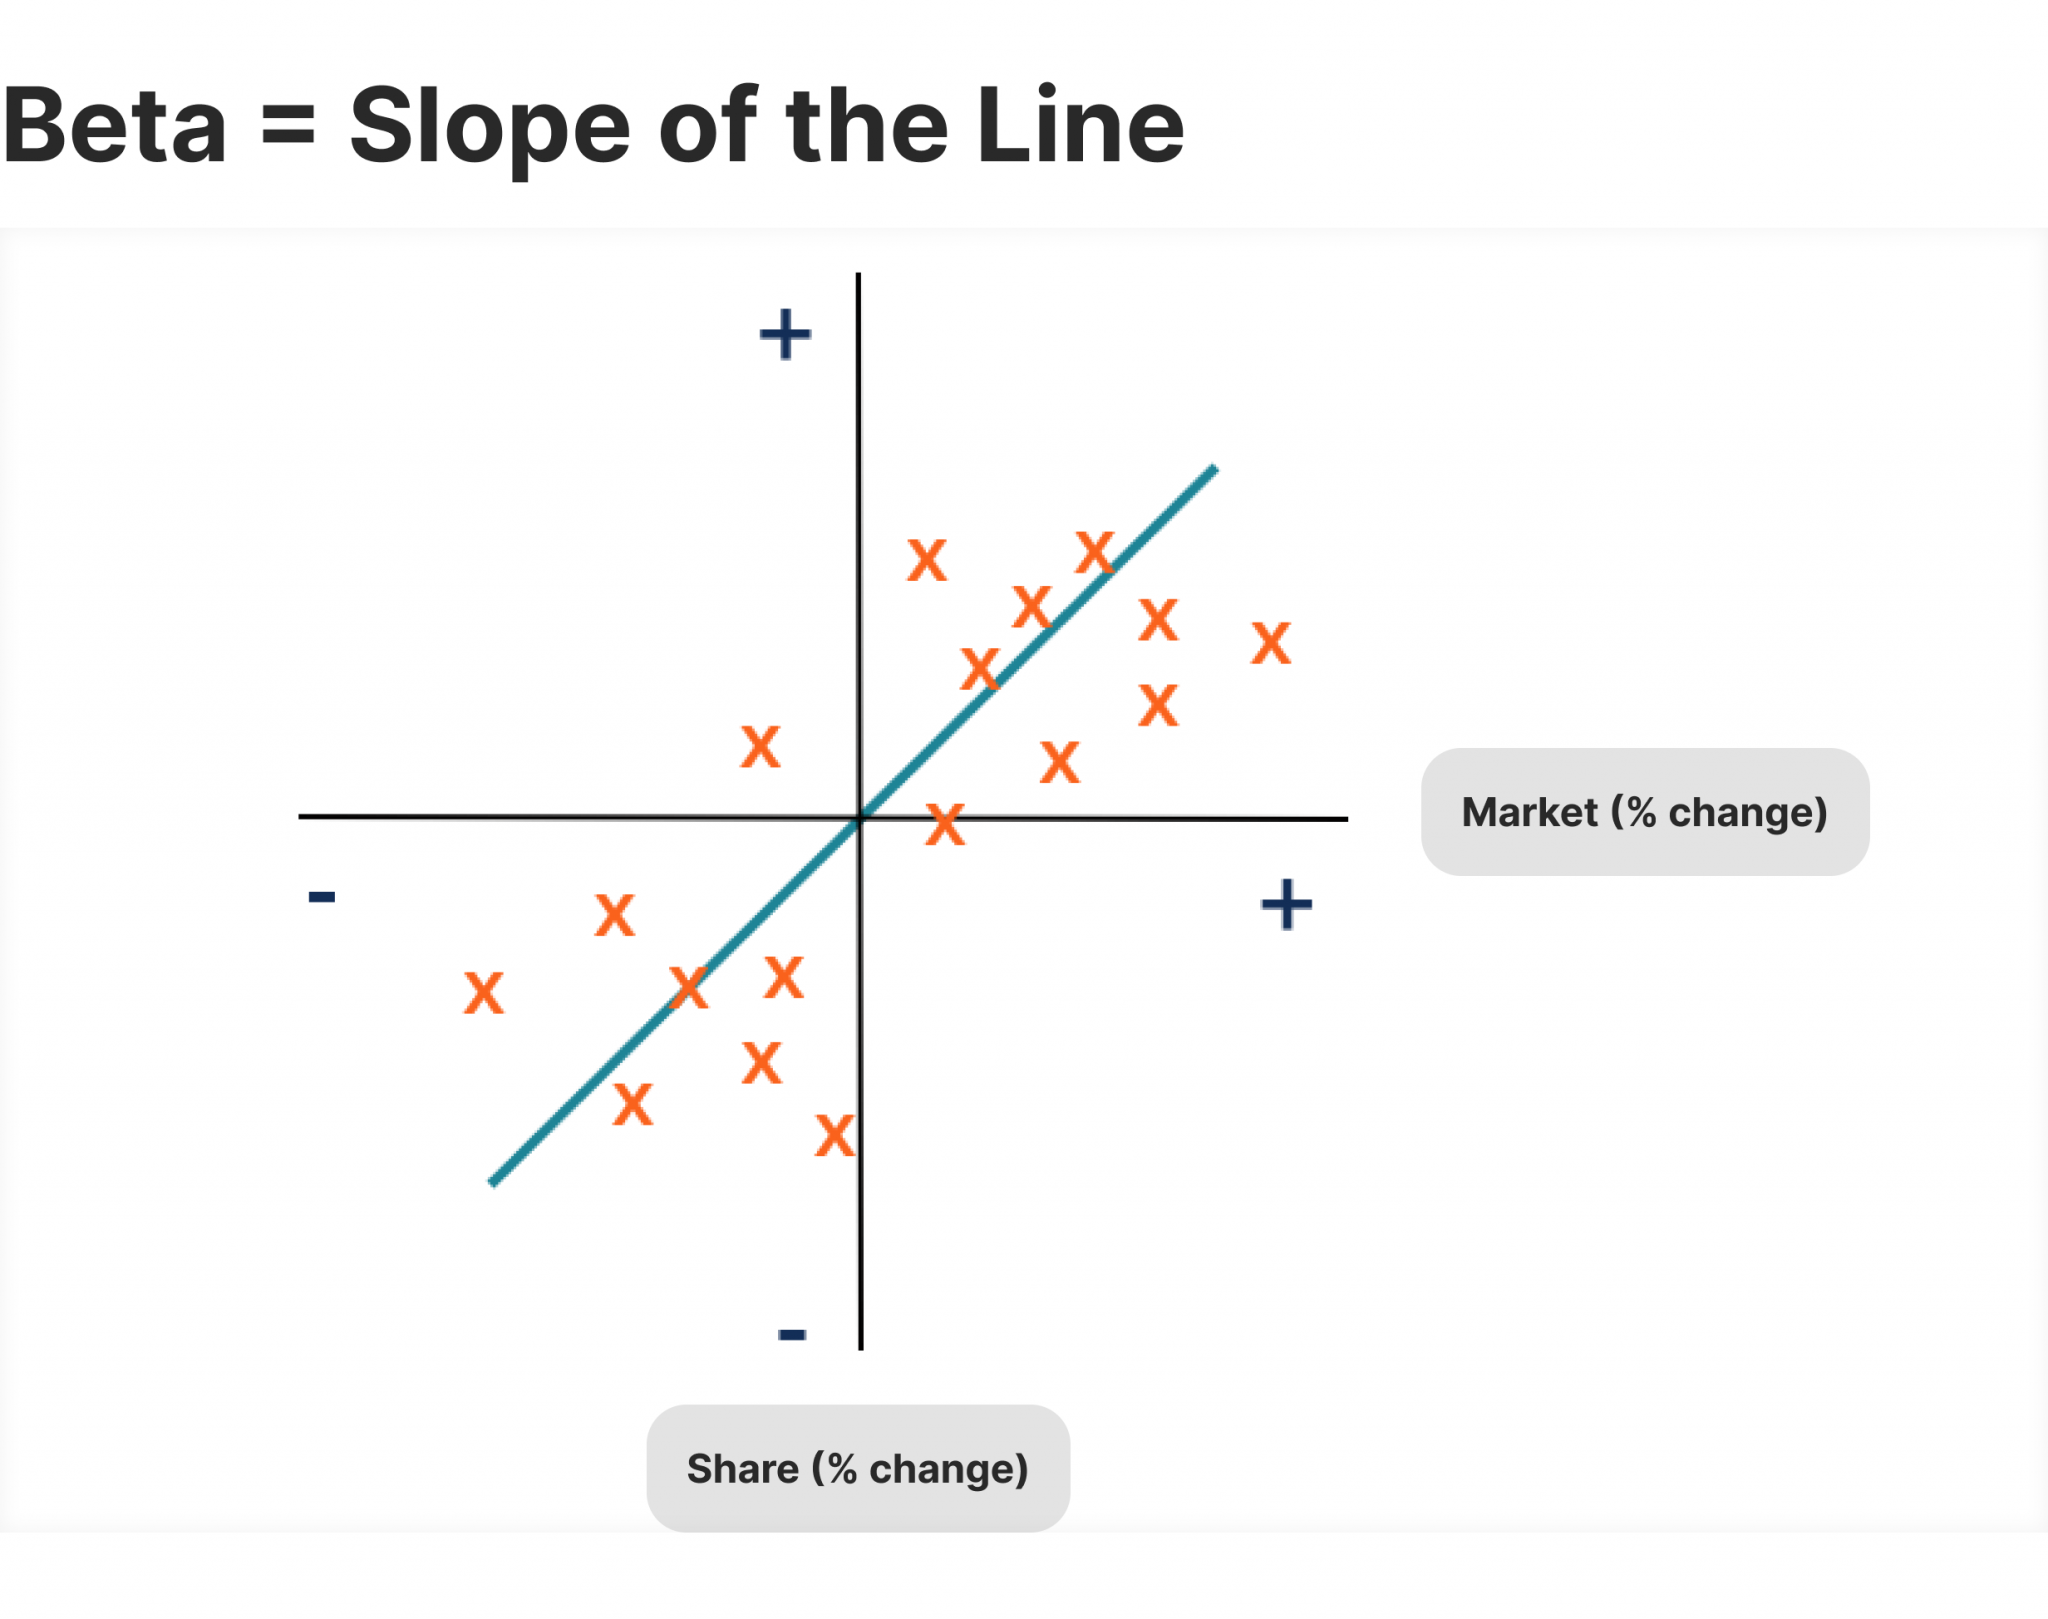
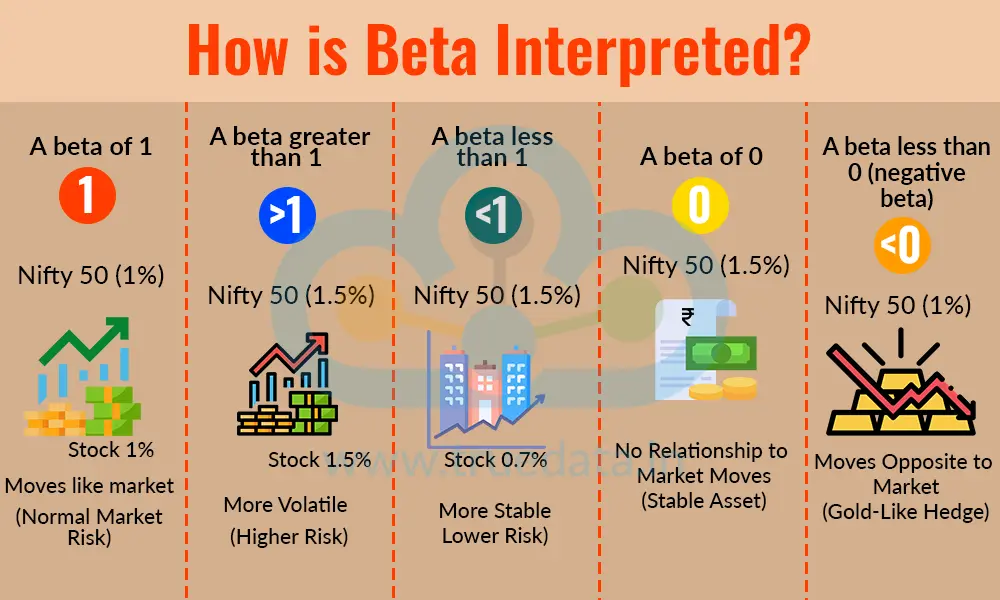
If you're building this into a spreadsheet or script, here's the approach I use. Pull adjusted closing prices for your stock and SPY over the last 60 trading months. Calculate daily log returns. Run covariance and variance on those return series. Annualize by multiplying covariance by 252 and variance by 252, though the annualization factor cancels out in the division so it doesn't matter. Store the result. Update monthly. Check quarterly whether the trailing three-year beta differs materially from the trailing one-year beta. If it does, flag the position for review. The tools to do this yourself are everywhere if you want to avoid paying for Bloomberg terminals. Yahoo Finance shows a five-year beta on the key statistics page. Google Sheets can pull the data with the GOOGLEFINANCE function using symbols like "SPY" and the ticker you want. For anything beyond a handful of positions, I recommend Python with pandas_datareader or yfinance. A basic script takes about twenty lines and runs in under a minute across a full watchlist. The free version works fine for personal use. The biggest mistake I see people make is treating beta as a risk metric in isolation. It's a directional sensitivity metric. A beta of 0 means the stock moves independently of the market, which sounds safe until you realize it could be a declining stock that nobody cares about. A beta of 2 doesn't mean double the returns. It means double the sensitivity to market moves. In a rising market you benefit. In a falling market you get crushed faster. I learned that distinction after losing money on a pair trade that assumed symmetric outcomes around beta adjustments.
For portfolio construction, I recommend pairing beta analysis with correlation analysis. Two stocks can each have a beta of 1.2 relative to the market but move in opposite directions to each other. That's a useful diversification dynamic that beta alone won't show you. I started tracking pairwise correlations alongside my beta calculations. The combination gave me a clearer picture of where my actual risk concentration lived versus where I thought it lived based on sector labels alone. Beta is a useful tool if you understand what it measures and what it doesn't. It tells you about systematic risk exposure over a specific historical window using a specific benchmark. That's it. Everything else is interpretation. I wish more articles made that limitation clear upfront instead of selling it as a prediction tool. Use it alongside other metrics, update it regularly, and adjust your sizing when the numbers stop making sense. That's the practical approach that actually works.