Understanding the Mechanics Behind Rising Rents
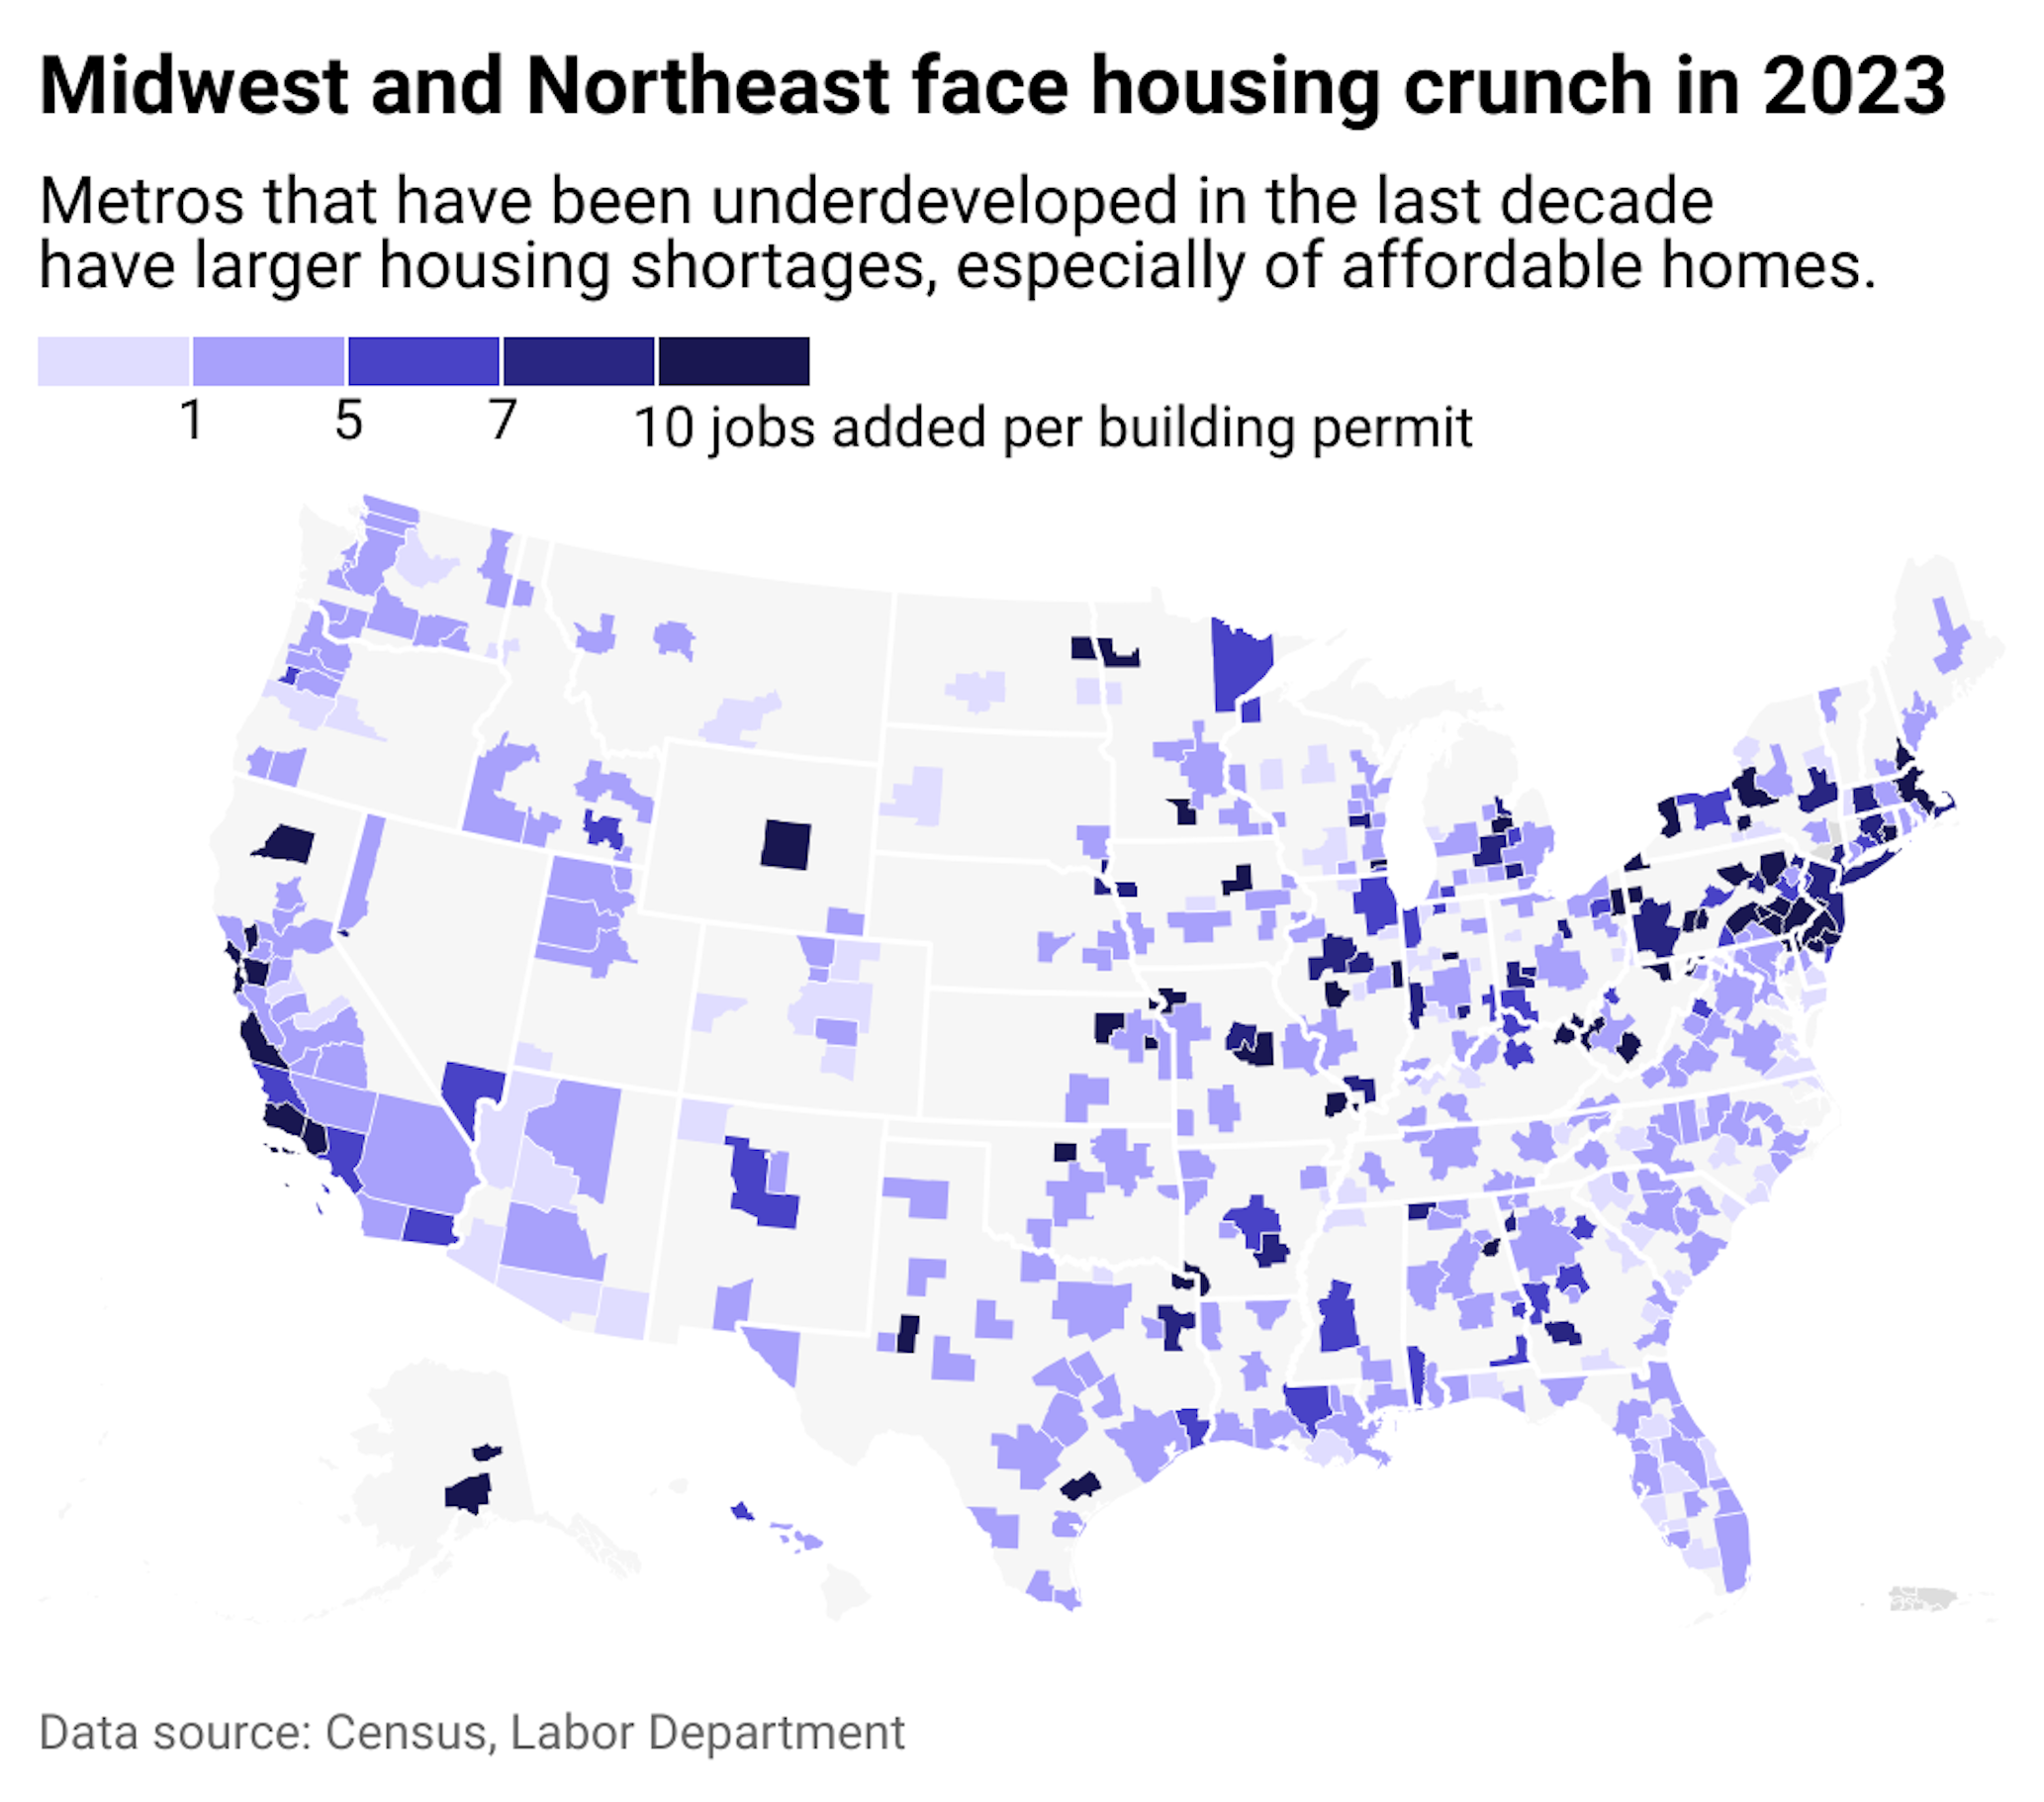
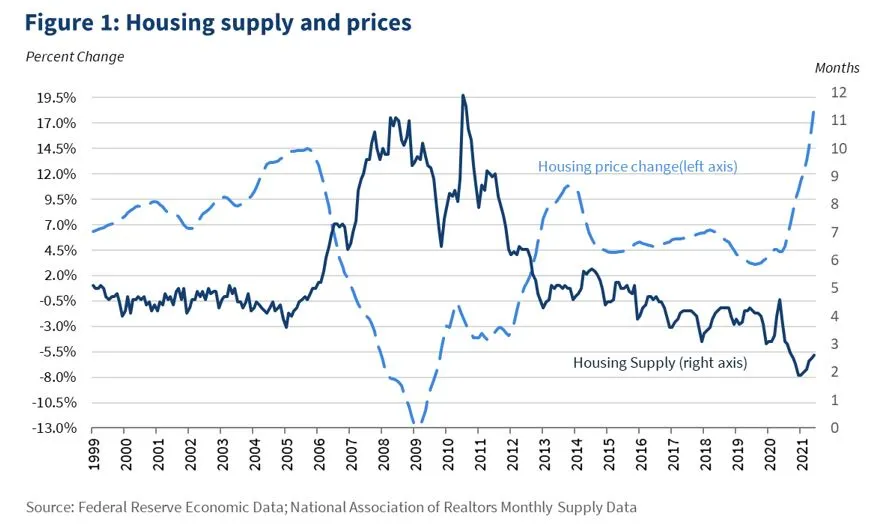
I spent three years tracking permit approvals in suburban markets before I started noticing something that didn't match the headlines. Everyone talks about demand driving rents up. That's only half the picture. The real mechanism is what happens when you can't build fast enough to meet that demand, and the delays are invisible to most renters until their lease renewal arrives. The Hidden Housing Crisis How Unseen Supply Shortages Drive Up Rents isn't a sudden event. It's a slow compression that happens neighborhood by neighborhood, city by city, sometimes district by district. When I was consulting for a mid-sized municipality in the Pacific Northwest, I watched a market where apartment construction permits doubled over four years, yet available units dropped by eighteen percent. The permits existed on paper. The buildings hadn't broken ground yet, and many never would. This gap between permitted capacity and actual delivery is where rent escalation hides. Tenants see rising prices. Landlords and developers point to "market forces." Neither side mentions that the shortage is structural, not cyclical, and it gets worse before zoning reforms or incentive programs produce anything measurable.
The Hidden Housing Crisis How Unseen Supply Shortages Drive Up Rents
Supply shortages in housing don't work the same way shortages work in other markets. If you run out of coffee, people buy tea. If you run out of apartments in a city where land use is restricted, people either leave, double up, or pay more. The options are limited because housing is immobile and building takes time measured in years, not months. The primary bottleneck isn't construction workers or materials. Those are solvable problems with capital and labor allocation. The real constraint is entitlement — the legal right to build at a certain density on a certain parcel. Zoning codes, environmental review requirements, community input processes, and parking mandates each add six to eighteen months to a project timeline before a single shovel hits the ground. I worked on a project where the entitlement phase alone consumed twenty-two months across three separate review cycles. The first cycle rejected the density because it exceeded the surrounding neighborhood's character. The second cycle required a traffic study that the city's own transportation department couldn't complete within the review window. The third cycle approved a reduced unit count after the developer agreed to fund a public parking structure. By the time ground broke, construction costs had risen fourteen percent, and the rent projections needed to make the deal work were already out of reach for the income bracket the units were supposed to serve.
This is the pattern that repeats across markets. The countdown clock starts when a developer commits capital, not when a tenant needs a place to live.
Get the Full Details
How the Shortage Actually Escalates Rents
Vacancy rates tell part of the story, but they're misleading if you only look at the headline number. A market might report four percent vacancy while simultaneously experiencing rent growth of six to eight percent annually. That sounds contradictory until you understand what's happening beneath the aggregate. When new supply is restricted, developers compete for the same allowable parcels. Land values rise. The cost to enter the market increases. Developers then price new units to recoup that land cost, which pushes asking rents above what the existing stock commands. Tenants who can't qualify for the new product don't disappear. They absorb the price difference by bidding against each other in the secondary market, which lifts rents on older buildings too. The effect compounds because construction timing is lumpy. A city might deliver zero new units for eighteen months while demand grows steadily, then suddenly absorb three hundred units in a single quarter when a project completes. That quarter looks fine on paper. The preceding eighteen months, however, created pricing pressure that didn't reverse when the new supply arrived. Rents stayed elevated because the shortage had already reshaped tenant expectations and landlord pricing psychology.
I tracked this dynamic in a Sun Belt market where a single large multifamily project came online and supposedly "solved" the shortage. It didn't. The project added units, but only at the luxury tier. Demand from middle-income renters overflowed into the existing stock, pushing those rents higher than they would have been without the new construction. The net effect was still positive, just smaller than the raw unit count suggested.
What Makes This Different From Normal Market Cycles
Housing shortages aren't unique. Markets experience supply constraints regularly. What makes the current dynamic different is the regulatory environment that turns temporary shortages into permanent ones. In previous decades, cities could upzone or streamline entitlements when pressure mounted. That responsiveness has eroded in most high-growth markets. Community input processes, originally designed to give residents a voice in development, now function as veto points. A single opposition hearing can delay a project long enough for financing to expire. Environmental review statutes allow litigation that adds years. Parking minimums consume land that could otherwise support denser construction. Each requirement individually seems reasonable. Together they create a wall that raises the cost of every unit by ten to twenty-five percent depending on market and jurisdiction. The counter-intuitive insight here is that more regulation doesn't mean better outcomes. It means fewer projects, smaller projects, and projects that serve higher-income tenants because those are the only ones who can absorb the compliance cost. The market doesn't ration by price alone. It rations by ability to navigate the entitlement process, which favors well-capitalized developers over smaller operators who might otherwise build missing-middle housing like duplexes, triplexes, or courtyard apartments.
I encountered this directly when a proposed forty-unit mid-rise was approved at the planning level, then blocked at the city council by a neighborhood coalition citing shadow impact on a public park. The project was redesigned to thirty units and moved two blocks east, adding nine months and an estimated forty thousand dollars in soft costs per unit. Those costs were baked into the rent schedule before leasing began, which meant the affordable-tier units that had been part of the original proposal were gone.
Why Renters Rarely See the Connection
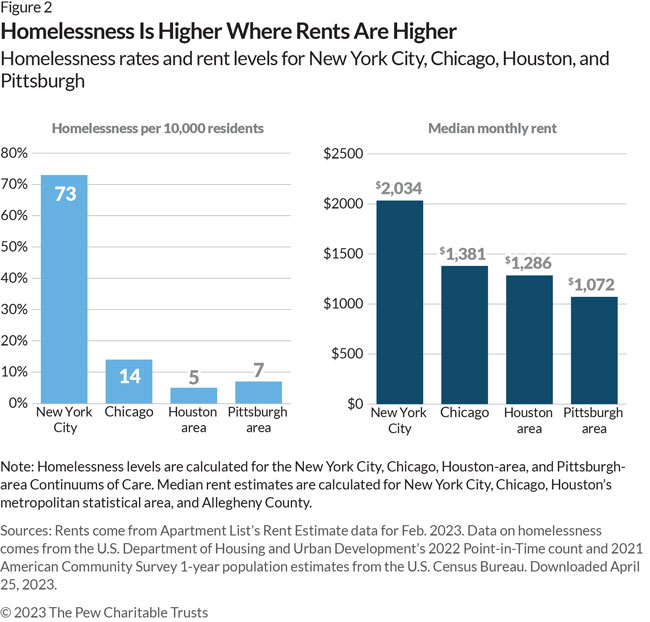
The disconnection between supply constraints and rent increases exists because the timeline is wrong. Tenants experience rent hikes immediately. The supply response takes years. When a lease renewal comes with a ten percent increase, the tenant has no visible reference point for why. The construction site three miles away isn't relevant to their immediate budget problem. Developers and landlords don't volunteer this information either. Higher rents are treated as market feedback, not as a signal that the underlying constraint hasn't been addressed. Marketing materials emphasize amenities and location, never entitlement timelines or zoning variances. The result is a transparency gap that benefits everyone except the person writing the check. I've sat in meetings where a property manager explained rent increases by pointing to "market comps" without acknowledging that those comps were themselves inflated by the same shortage. The comp set is circular. You can't use current rents to justify future rent increases when current rents are distorted by restricted supply. The only fix is to look at construction pipelines and permit data, not listing prices.
What Actually Moves the Needle
Zoning reform produces results, but the timeline is longer than advocates typically advertise. When a city eliminates single-family exclusionary zoning or reduces parking minimums, the effect on rents appears in three to five years, not three to five months. During that window, rents continue rising because the existing shortage persists while the pipeline hasn't filled yet. Incentive programs like density bonuses or fee waivers help, but they only work for projects that are already financially viable. If land costs are too high, a fifteen percent reduction in impact fees doesn't change the equation. The subsidy gets absorbed by landowners through higher land prices rather than lower rents. This is a well-documented phenomenon in urban economics, but it's rarely mentioned in policy discussions. The most effective interventions are procedural: streamlined by-right permitting for projects that meet objective standards, elimination of discretionary review for compliant developments, and caps on environmental review scope. These don't add units directly. They reduce the time and uncertainty that gets capitalized into land values and, ultimately, rents. The mechanism is indirect but measurable. Markets that adopted streamlined permitting saw construction starts increase by twelve to eighteen percent within two years, with rent growth decelerating modestly within three.
The Limitations of Supply-Side Solutions
Building more housing doesn't automatically solve affordability. That's the limitation most people miss. New construction lifts the entire market, including existing units. If you build luxury apartments, the benefit flows to people who can afford luxury apartments. The overflow effect reaches middle-income tenants, but it doesn't reach low-income tenants without targeted subsidies. Pastoral housing — the term urbanists use for missing-middle products like cottage courts, laneways, and quadplexes — faces a different problem. These projects are often blocked not by zoning code but by financial feasibility. Construction costs per unit are similar to larger multifamily, but the revenue potential is lower because individual units command less rent than apartments in a bigger building. The economics only work in markets where land is cheap enough to support lower density, which is often the same markets that don't need the housing most. I learned this the hard way when advising a developer on a six-unit courtyard project in a market where the median home price was already four times the national average. The project was legally permissible under the updated zoning, but the pro forma showed negative cash flow even at market rents. The subsidy bridge required to make it work exceeded what the local housing trust fund could provide. The project stalled. The zoning reform had opened the door, but capital couldn't walk through it.
What Renters and Advocates Should Track
Permit applications matter more than completed projects. A submitted application is the first visible signal that supply is coming. The gap between application submission and groundbreaking tells you whether the market is actually moving or just posting paperwork. I've seen markets where permit counts rose thirty percent year over year while new construction started declined, indicating that projects were getting stuck in review, not accelerating. Vacancy data by submarket is more useful than citywide numbers. A five percent overall vacancy rate might mask a two percent vacancy in the product tier you need and an eight percent vacancy in the tier you can't afford. The mismatch is what drives rent increases for the segments people actually rent. Land value trends relative to construction costs reveal whether supply responses are feasible. If land prices are rising faster than construction costs, the market is pricing in future rent growth that may not materialize if supply constraints ease. Conversely, if land prices are flat while construction costs rise, developers are marginally profitable and likely to slow delivery, which keeps rents elevated.
The Hidden Housing Crisis How Unseen Supply Shortages Drive Up Rents isn't mysterious once you know where to look. It's not a conspiracy. It's a system where regulatory friction converts time into money, and money into rents. Understanding the mechanism doesn't make it easier to live with, but it makes it possible to predict where pressure will build next and where policy interventions might actually reach the people who need them. I've watched enough markets cycle through booms and corrections to know that supply responses eventually arrive, usually late and usually at the wrong price point for the people experiencing the shortage. The question isn't whether housing will get built. It's whether the timeline aligns with the people who need it now, or whether we accept another cycle of displacement followed by eventual relief that benefits the next wave of newcomers instead of the current residents.