Public Records As A Due Diligence Shortcut
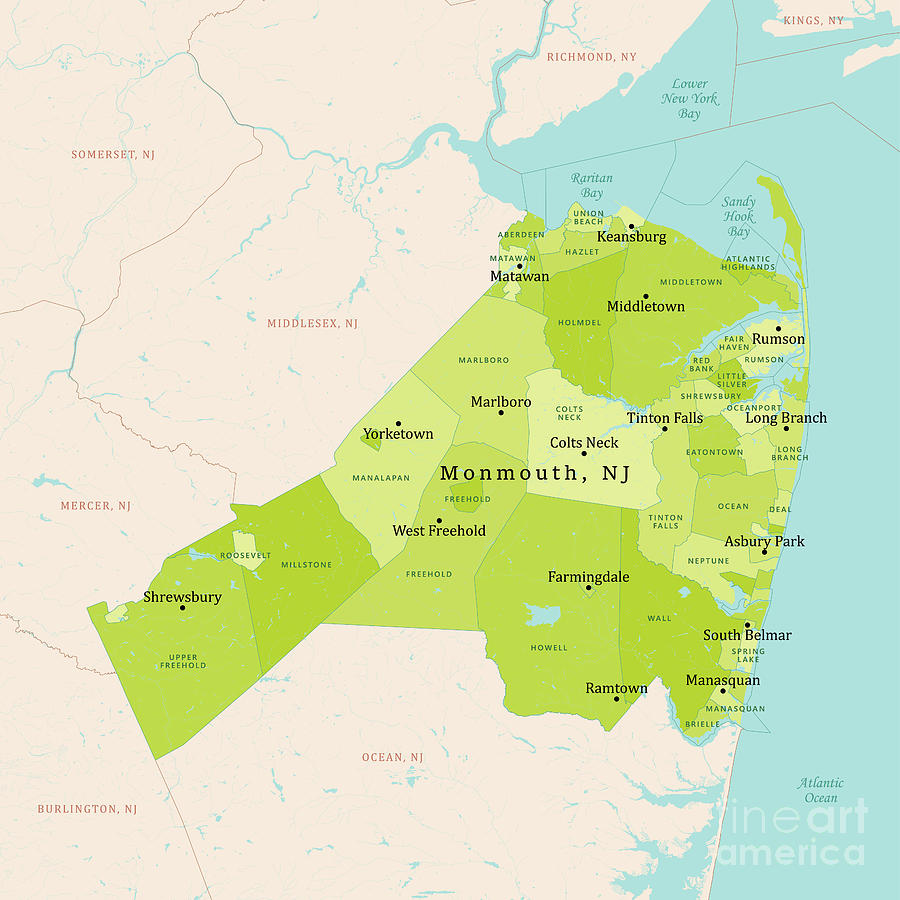
Monmouth County, New Jersey, has a property records system that most casual investors completely overlook. It is not glamorous. It is also not particularly difficult to navigate once you understand where the county clerk, the register of deeds, and the tax assessor each hold pieces of the puzzle. What sits there is raw data about ownership, lien positions, transfer history, and sometimes more than people realize about why a property moved hands the way it did. I spent years pulling these records for residential and small commercial deals around Atlantic Highlands, Holmdel, and Toms River. The process is tedious but predictable. The payoff only matters if you know what signals to look for. Most people look at a deed and stop. That is where the opportunity hides.
The Hidden Goldmine Of Monmouth County Mortgage Records How To Uncover Property Secrets And Investment Opportunities
Where The Records Actually Live
New Jersey is a recording state, which means every mortgage, lien, and conveyance gets entered into the public land records. Monmouth County does not run a fully digital image system the way some jurisdictions do. You can search indices online through the county recorder or the Freehold courthouse portal, but high-quality scanned documents often require an in-person visit or a records request through the county clerk's office. The assessor's site at monmouthcountynj.gov handles parcel data, tax maps, and valuation histories. The court system handles lis pendens and foreclosure filings. All three feeds together give you something close to a timeline. Practical workflow: start with the assessor to lock down the parcel ID and current owner. Pull the deed history through the recorder index. Cross-reference any recorded liens or satisfaction documents. Then check the superior court docket for active litigation or foreclosure actions. That sequence usually takes about twenty minutes if you know the shortcuts and longer if you are learning the interface for the first time.
What You Can Actually Extract
Deeds show transfer dates and consideration, but the recorded mortgage and its subsequent satisfaction or modification carry more useful intelligence. The original loan amount, the recording date, the lender name, and any refinance activity create a shadow profile of how much equity existed at different points in time. Satisfaction documents reveal when debt was retired, which often lines up with sales or refinances. Subordinations and lien priority documents show who gets paid first if things go sideways. Assessor records give you assessed value trends and exemption flags. Homestead exemptions do not exist in New Jersey the way they do in other states, but you will see owner-occupancy indicators and sometimes veteran or disabled exemptions that affect tax bills. Transfer forms and declaration of value worksheets, when recorded alongside deeds, can show whether the sale price matched arm's-length terms or if the transaction involved related parties.
Get the Full Details
Edge Case I Ran Into More Than Once
A few years ago I was evaluating a duplex near Middletown. The deed chain looked clean, the assessed value was reasonable, and the comparables supported the price. Then I pulled the mortgage history and found a recorded lien from 2008 that never showed a satisfaction document. The recorder's index listed it as released, but the actual satisfaction instrument was missing from the index entry. The seller claimed the loan was paid off in a 2012 refinance, but the new mortgage document referenced the old lien by volume and page and did not explicitly satisfy it. The workaround was straightforward but required patience. I went to the Freehold recorder's office, requested a full index printout for the original mortgage under the grantor's name, and found the satisfaction recorded three months after the refinance under a slightly different instrument number. It was not hidden, just poorly indexed. I flagged it for the title company before closing and made sure the title policy included an exception for any unrecorded liens that might attach. Without that check, I would have inherited a first lien position that was not actually first. This happens more often than you would expect in older suburban markets where refinances overlap and satisfaction documents get filed under the wrong party name or in the wrong volume. Always verify satisfaction instruments directly, not just rely on a database flag that says released.
Signals That Actually Matter
Rapid flip chains. If a property transferred within a two year window and then sat for a decade before another transfer, something happened. Check whether the intervening period included a modification, a partial satisfaction, or a second lien that got recorded and never tracked through to satisfaction. Quick flips themselves are not inherently bad, but paired with high loan-to-value recordings from the original purchase, they often signal distressed origins or speculative leverage. Lender concentration. When the same community bank or credit union appears across multiple nearby properties in the same neighborhood, that is not random. Local lenders tend to underwrite similarly and hold similar risk profiles. If you see a cluster of properties with mortgages from a single institution that later shows up in a modification or satisfaction cascade, that lender may be managing a portfolio workout. These properties sometimes surface at auction or through bank-owned channels before they hit mainstream listings. Partial releases on subdivision plats. Monmouth County has numerous parcels carved from larger tracts over the last fifty years. A recorded mortgage on the parent tract with partial release documents layered on top tells you exactly which portions were sold off and when. This is critical for understanding boundary disputes, easement conflicts, and whether a lot was legally built out at the time of construction. I once missed a nonconforming lot issue because I only looked at the current parcel map and ignored the 1994 partial release that showed the original subdivision lacked frontage on an improved road. The lot closed fine, but the municipal code enforcement risk was real.
Common Pitfalls
Assessed value equals market value. It does not. Monmouth County revaluation cycles create lags. A property assessed in 2023 based on a 2021 sales comparison may look undervalued in a market that shifted sharply. Always cross-reference assessed value with actual recorded sale prices, not the other way around. Mortgage amount equals outstanding balance. It rarely does. The recorded original loan balance is historical. Unless you see recent modification documents or a current statement from the holder, assume the balance is unknown. Many investors overpay because they assume a low recorded loan means high equity, when in reality the property may have been cash-flow negative and refinanced into a higher balance years later. Online indices are complete. They are not. New Jersey counties often have delayed indexing, misfiled instruments, or satisfactions recorded under variant names. The online search will show you what the index contains, not necessarily everything that exists. If a deal depends on clean title, budget time for a full title search through a local attorney or title plant, not just a database pull.
Costs And Time Estimates
Searching the assessor's online portal is free and takes five to ten minutes per parcel. Index searches through the recorder's online system are usually free as well, though certified copies cost between two and five dollars per document. Physical copies with certification run higher. A full title search through a local title company or real estate attorney typically costs four hundred to eight hundred dollars for a standard residential transaction and one to two hours of work on their end. If you are pulling records yourself for due diligence across multiple parcels, factor in twenty to thirty minutes per property for a competent search, plus additional time if you need to visit the recorder's office in Freehold. Properties tied to trust structures, LLCs, or out-of-state entities can obscure the actual beneficial owner. The recorded grantor may be a nominee trustee, and the satisfaction or modification history may reference the trust rather than the operating entity. In those cases, the public record shows a chain, but the real decision maker is invisible without a subpoena or a corporate records request. I have walked away from deals because the ownership layer was thick enough that I could not verify who actually controlled the asset within a reasonable timeframe. Pre-1990 documents sometimes exist only on microfiche or paper at the county archive. Digitized indexes may list them, but you cannot read the actual instrument without a request and a wait. If your analysis depends on a specific old lien or restriction, assume a one to three week turnaround for physical retrieval unless you have a relationship with the recorder's office that speeds things up.
A Practical Sequence You Can Replicate
Pull the parcel ID from the assessor site. Download the current deed and the prior three transfers if available. Request the recorded mortgage(s), any modification agreements, and every satisfaction document. Check the superior court docket for lis pendens or foreclosure actions tied to the grantor names. Verify lot lines against the most recent subdivision plat on record. Cross-reference the lender names across neighboring parcels to spot portfolio patterns. Run the assessed value trend against recorded sale prices to gauge revaluation lag. Only then do the numbers mean anything in context. Most of the work is assembly, not interpretation. The patterns become obvious once you have ten or fifteen Monmouth County properties in front of you. Before that, you are just collecting paper. The trick is to collect the right paper and read it in order.