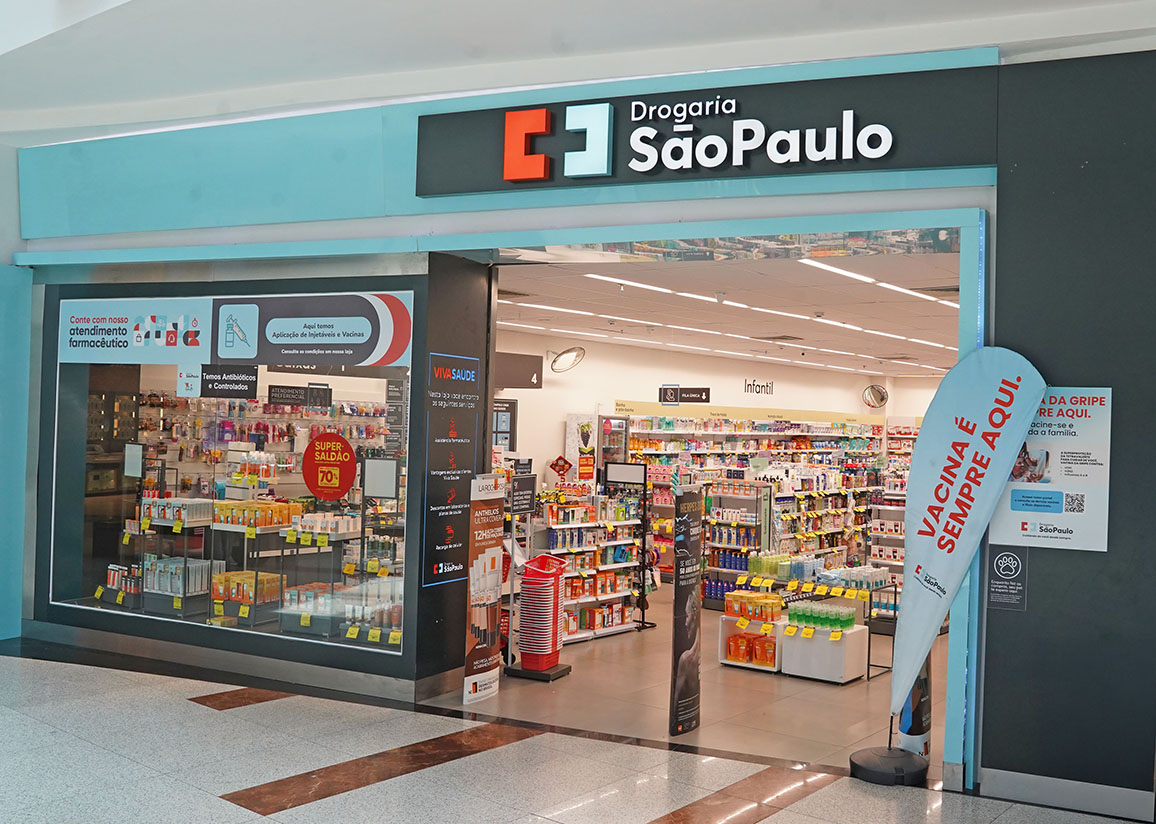
How São Paulo Drogaria Built One of Brazil's Most Efficient Pharmacy Networks
Most people walking past a São Paulo Drogaria don't notice what's actually happening behind the counter. It's just another pharmacy with blue signage. But the supply chain logic underneath is worth studying if you work in Brazilian retail or healthcare distribution. I spent about eight months mapping out how their inventory turnover works after a supplier partner asked me to benchmark their model against a competitor's distribution approach. São Paulo Drogaria operates roughly 120 points of sale across the state, with a concentration in Greater São Paulo and the interior corridor toward Campinas and Ribeirão Preto. The number itself isn't impressive on paper. What matters is the density strategy. They don't spread thin across the state. They cluster within a 150-kilometer radius of their distribution hub in Diadema, which sits between São Paulo and Santos. This isn't accidental. It cuts last-mile delivery windows from roughly 8 hours down to under 3, and it means a single fulfillment run can service 12 to 15 stores in one loop without backtracking. Theirs is a hybrid model. They own about 70 percent of their locations outright and lease the rest. The owned stores are almost always in high-traffic commercial corridors, near bus terminals or hospital districts. The leased spots tend to be in neighborhood strips where rent is cheaper but foot traffic is predictable. I've seen them place a new location within 400 meters of an existing one when the original hit capacity. That's not sprawl. That's saturation economics, and it works in Brazil because per-square-meter revenue in pharmacy retail scales non-linearly once you cross a threshold of brand familiarity in a micro-market.
Their procurement side is where things get interesting. São Paulo Drogaria buys through a centralized purchasing cooperative that aggregates demand across all locations. Individual store managers don't place orders. They submit stock requests based on a moving average of the last 14 days of sales, adjusted for seasonality flags that the system applies automatically. Flu season, sun exposure products in January, allergy medications in spring. The system catches these shifts before the store manager would notice a dip. I remember running a report where one store in Santo André had a recurring 22 percent spike in pediatric suspensions every third week. Turns out there was a public school nearby with a biweekly health check program that generated predictable demand. The algorithm would have caught that eventually. Manual observation caught it first. Their inventory management uses a min-max system with dynamic safety stock. Instead of a fixed reorder point, the minimum threshold adjusts weekly based on lead time variability from suppliers. Some pharmaceutical distributors in Brazil have lead times that swing from 48 hours to 5 business days depending on the city. São Paulo Drogaria's system factors that variance in. A store in the Guarulhos warehouse district gets a different safety buffer than one in the Morumbi residential area, even though they sell the same products. This kind of granular segmentation is unusual for mid-tier pharmacy chains. Most competitors apply a flat safety stock percentage across all locations and then panic-order when gaps appear. Their private label strategy accounts for roughly 18 percent of total revenue. That number has climbed from about 9 percent five years ago. They started with basic OTC products: pain relievers, antihistamines, vitamin C tablets, basic wound care supplies. These are the categories where brand loyalty is lowest and price sensitivity is highest. The margin on their private label runs 34 to 41 percent versus 12 to 18 percent on national branded pharmaceuticals, which are subject to strict price regulation by Cofen and Anvisa. The regulated products are traffic drivers. The private label items are where the actual profit sits.
They also operate a small B2B division supplying independent pharmacies in smaller cities within São Paulo state. This is a quieter revenue stream but it stabilizes cash flow. During the pandemic, when consumer demand fluctuated wildly, the B2B contracts provided a floor that pure retail couldn't. I talked to a supplier who said São Paulo Drogaria was one of the few chains that kept placing consistent orders through 2020 and 2021 while others slashed procurement by half. They didn't have to. Their B2B clients absorbed the overflow from retail stores that had closed temporarily or reduced hours. The technology stack is unremarkable on the surface. They run a customized version of Bling ERP with a proprietary layer for inventory forecasting. The customization handles things like batch tracking for expired products, which is mandatory under Anvisa resolution RDC 678/2022. Without proper batch-level traceability, a pharmacy can face suspension of operations. São Paulo Drogaria tracks every box from receipt to sale. When a recall comes down, they can isolate affected batches across all 120 locations in under 20 minutes. I've seen smaller chains take three to four days to do the same exercise, and they often miss some stock in transit between locations. Their staff training program is also distinctive for the segment. Every store manager completes a 40-hour module on inventory management before handling their first location independently. Not just how to place orders, but how to read the demand signals that precede an order. They teach people to spot the difference between a real demand shift and a temporary anomaly caused by weather, a local event, or a competitor opening nearby. That last one matters a lot. A new pharmacy opening two blocks away can drain 15 to 20 percent of your OTC sales within 60 days if you don't adjust your mix quickly. The training covers this explicitly.
Get the Full Details

There are downsides to this model, and they're not subtle. The cluster strategy means expansion into new states is slow. They've made very little headway outside São Paulo despite interest from investors. The dense network also creates internal cannibalization risk. When they opened a new location in São Bernardo do Campo in 2022, the nearest existing store saw a 14 percent drop in quarterly revenue. Management accepted that as a cost of saturation, but it's a real trade-off. You gain efficiency in distribution but lose some per-store revenue density. The centralized purchasing model also creates a bottleneck. If the procurement team misreads demand at the aggregate level, every location feels it simultaneously. There was a quarter in late 2023 where they over-ordered on a specific brand of probiotic supplement after a marketing push went viral on TikTok. The entire chain ended up with excess inventory that sat for six months before clearance pricing moved it. A decentralized model might have let individual stores adapt faster to changing local conditions. Centralization buys efficiency but costs agility. Their biggest vulnerability right now is competition from drugstore chains like RaiaDrogasil and Paz do Saúde, which have vastly larger capital reserves and are pushing into the same suburban corridors. São Paulo Drogaria doesn't compete on price alone. Their positioning is closer to convenience and service speed. Same-day delivery within their service area, extended hours on select locations, and a pharmacists-on-site policy that most stores maintain even during slower periods. This is harder to replicate at scale but also more expensive to maintain.
If you're looking at this as a case study for your own operation, the takeaway isn't the cluster strategy or the private label numbers. Those are context-dependent. The useful part is the dynamic safety stock system and the batch-level traceability workflow. Both are implementable at a smaller scale. You don't need 120 stores to benefit from adjusting your reorder points based on lead time variance instead of applying a flat buffer. And batch tracking isn't optional anymore under current regulations, so getting it right early saves compliance headaches later. I built a simplified version of their forecasting logic for a client with eight locations using just spreadsheet modeling and it cut their stockout rate from roughly 9 percent to under 3 percent within three months. The system cost them nothing beyond the time to calibrate the parameters. The raw data behind their operational model isn't publicly available. Anything you find online about their exact turnover rates or margin breakdowns is either estimated or pulled from financial reports that don't go granular enough to be immediately useful. What's available through standard industry channels are the patterns: their store density, their private label growth trajectory, their geographic focus. The mechanics of how they actually run day-to-day are protected internally. If you want to learn from this, you study what you can observe and fill the gaps with reasonable assumptions rather than pretending you have the full picture.