Understanding How Liquidity Actually Moves In Modern Markets
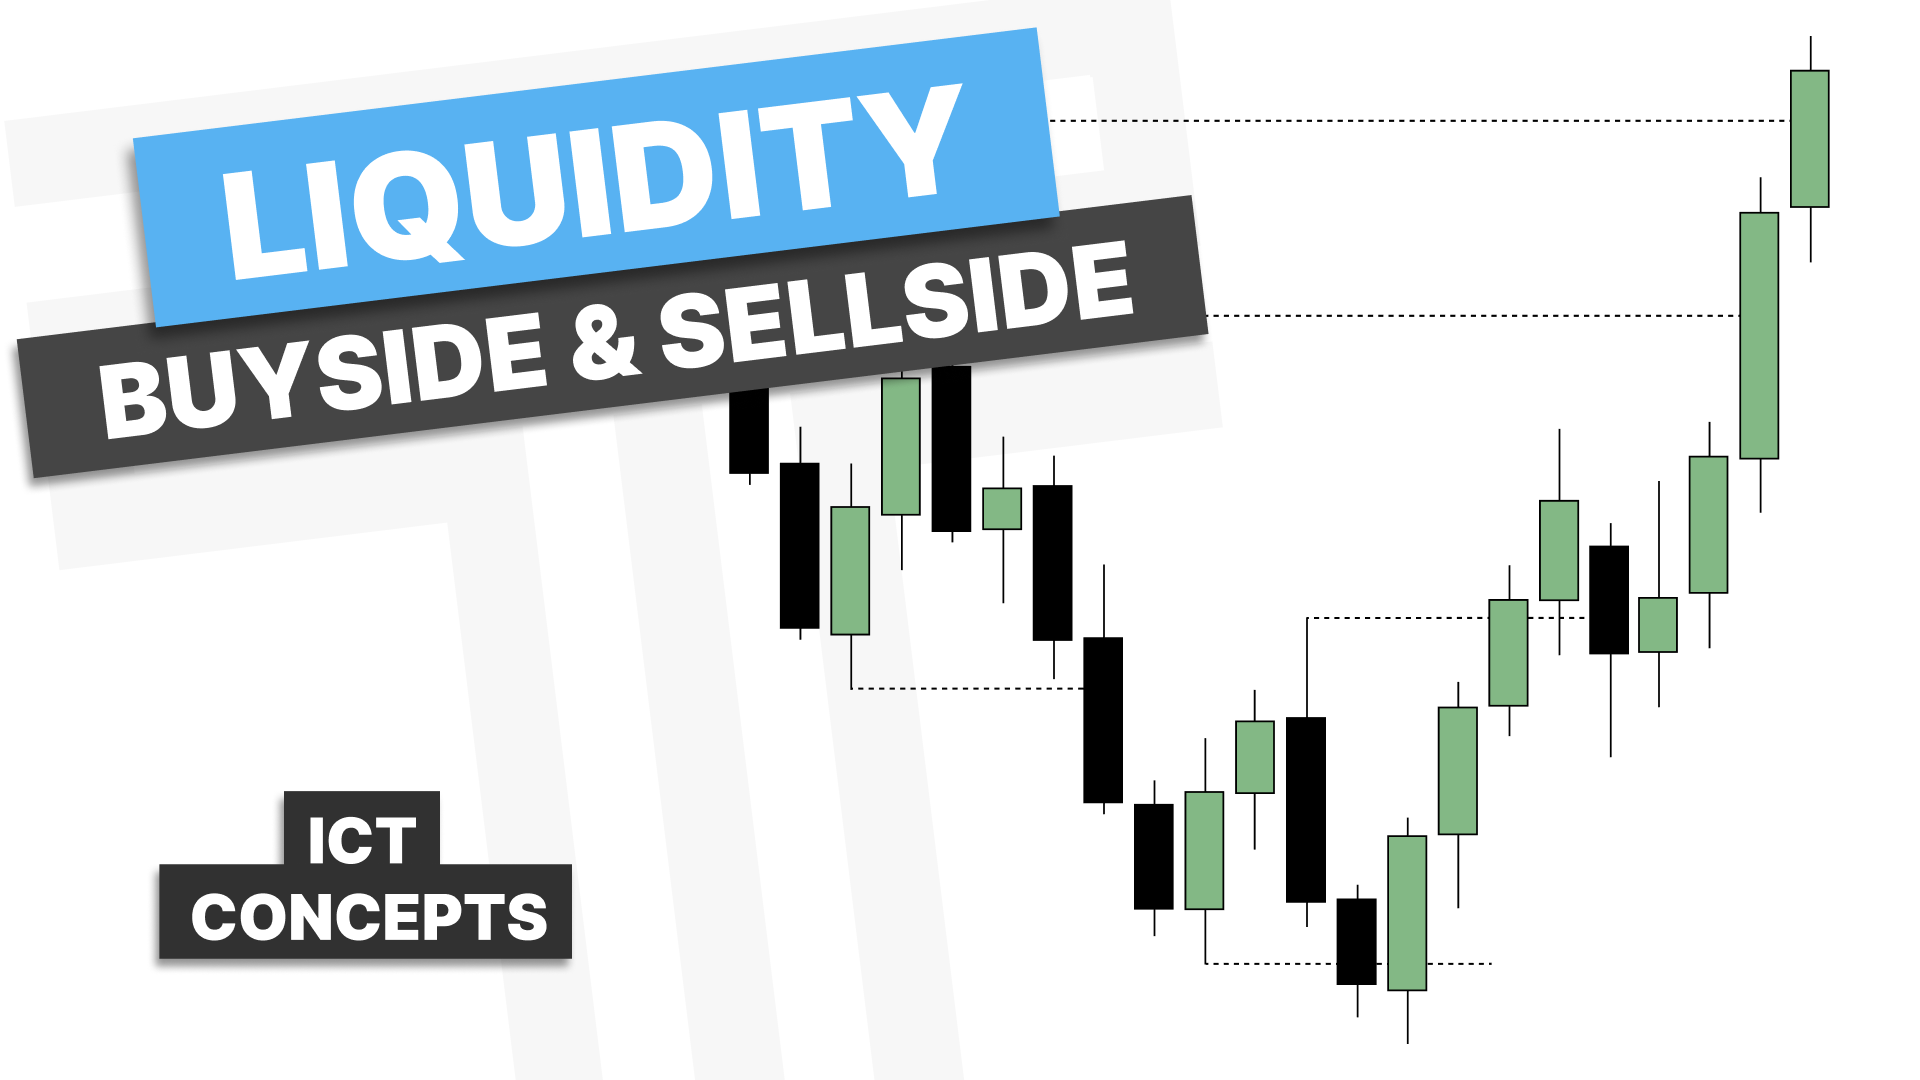
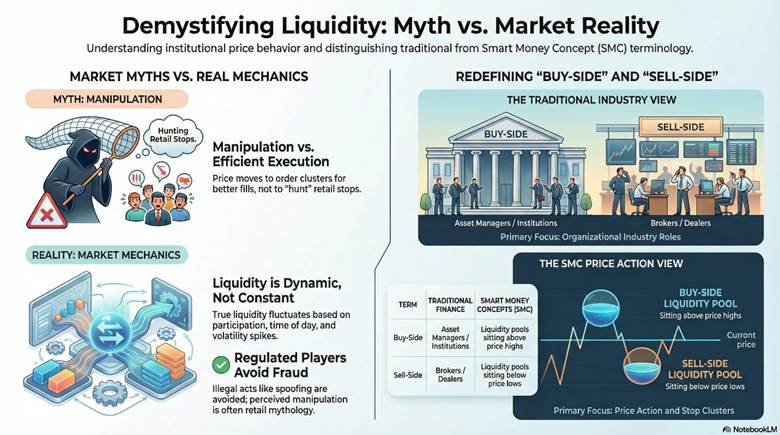
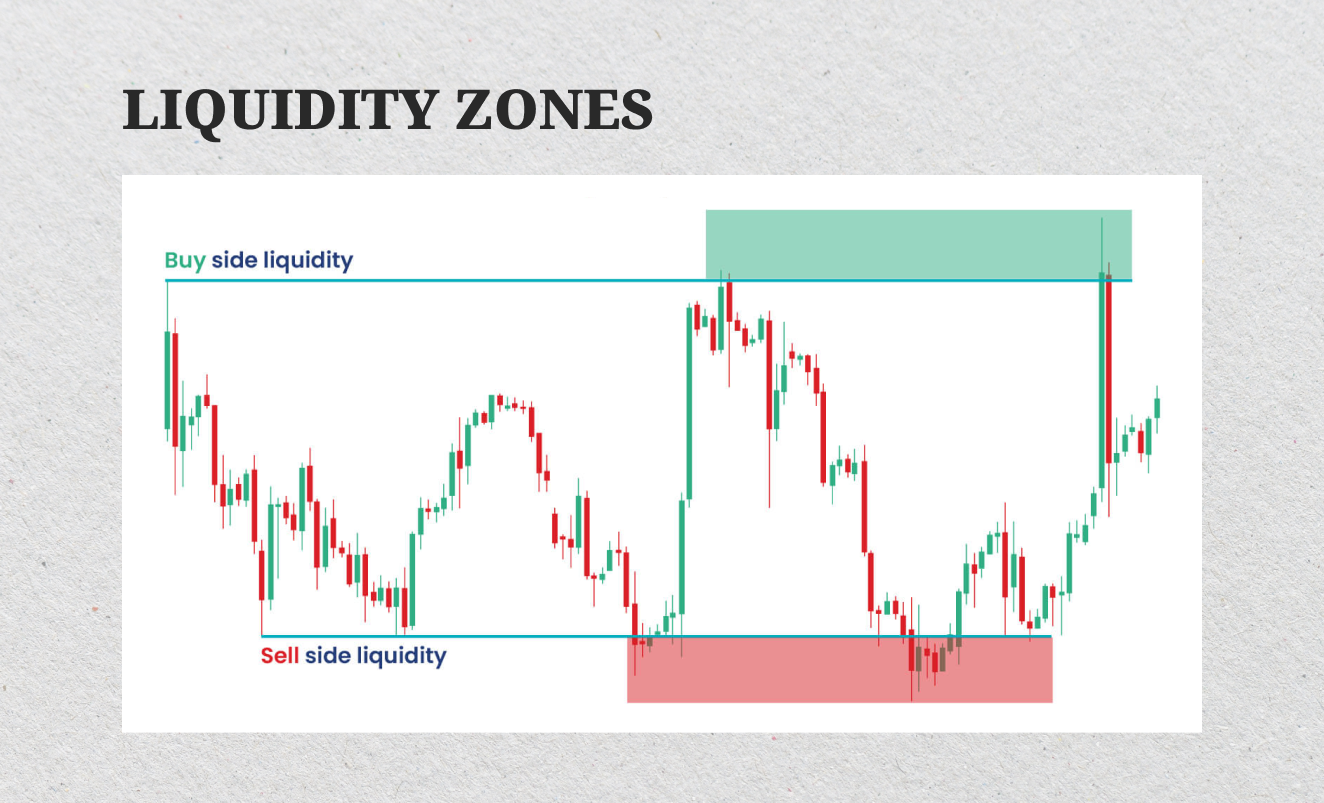
Liquidity isn't something you find on a chart. It's something you infer from price behavior and order flow. The market is populated by participants on both sides, and every exchange displays buy-side and sell-side liquidity constantly. Most traders look at level 2 data and think they understand it. They don't. The hidden drivers are the structural reasons why liquidity appears where it does, disappears when it shouldn't, and gets hunted before meaningful moves develop. ICT concepts tried to formalize this, but the reality is messier than any course will admit. Buy-side liquidity sits above current price. It's made up of resting buy stops, limit orders waiting to be filled, and institutional demand zones that show up as consolidation areas on higher timeframes. Sell-side liquidity sits below price and consists of resting sell stops, sell limits, and supply zones. The market moves toward liquidity because large orders need counterparties. When a hedge fund needs to buy two hundred million dollars of a stock, they can't just click buy and hit the tape. They need enough sellers at acceptable prices. That's why price gravitates toward areas where those counterparties are likely waiting. ICT taught traders to look for liquidity sweeps, fair value gaps, and order blocks. The core idea was sound. Price hunts stops before reversing. But here's what most tutorials skip: liquidity sweeps happen constantly and most of them fail. You can sit there watching every swing high get taken out and start losing money quickly if you assume each one leads to a reversal. The market sweeps liquidity all day long. What matters is identifying which sweeps occur in context with higher timeframe structure and which are just noise from algorithmic trading desks rebalancing positions.
The actual edge comes from understanding timing and volume profiles. Liquidity pools tend to form during specific windows. The London open between 2:00 and 5:00 AM EST creates different liquidity dynamics than the midday lull from 11:00 AM to 1:00 PM. Volume drops significantly during those midday hours, which means sweeps are less reliable and fakeouts are more common. I learned this the hard way trading European indices around noon. I took three consecutive losing trades believing a sell-side liquidity grab signaled an immediate long. The market just drifted lower for another hour before any real move developed. The lesson was straightforward: time of day matters more than the pattern itself.
How To Identify Real Liquidity Versus Fake Liquidity
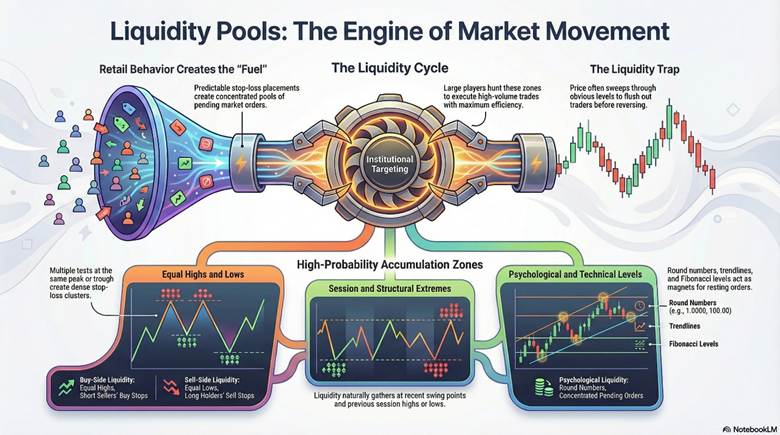
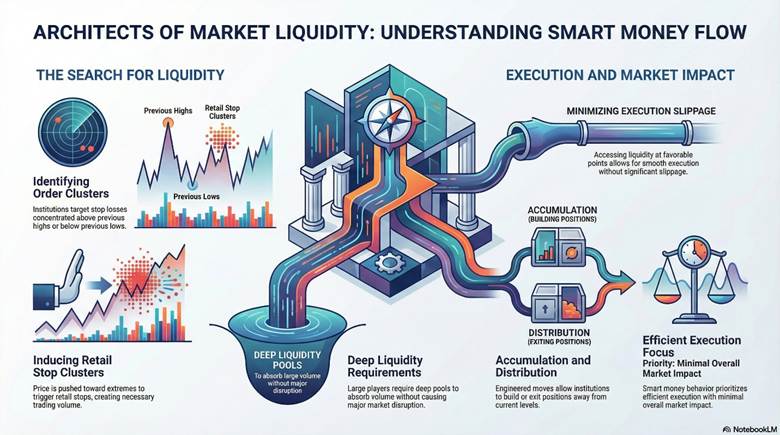
The first thing most traders miss is that not all consolidation equals liquidity. A tight range on a five-minute chart doesn't mean there's a fat pool of stops sitting above it. Sometimes it's just indecision with thin volume and no real interest. Real liquidity shows up when you see repeated wicks into the same area, increasing volume on rejection candles, and stop runs that occur at predictable times. You need to combine multiple signals rather than trusting a single visual pattern. Another counter-intuitive point: sometimes the biggest moves happen away from obvious liquidity. Traders cluster their stops around obvious swing highs and lows, and smart money knows this. The result is that price often moves toward less obvious areas where retail traders haven't placed their stops. I remember analyzing the S&P futures around 3:30 PM EST one afternoon. The obvious sell-side liquidity was clearly visible below the morning low. Everyone was positioned to short that break. Instead, price rallied hard through the day's highs, swept buy-side liquidity that nobody had anticipated, and ran forty points in ten minutes. The trap was too obvious and exactly what most retail traders were counting on. If you want to track where liquidity actually is, use footprint charts or market profile data if your broker supports it. You can see where the volume nodes are concentrated and where thin areas exist. Thick volume nodes at price levels suggest established liquidity. Thin areas suggest the market will move through quickly. This is more reliable than guessing from candlestick patterns alone.
Get the Full Details
Practical Workflow For Trading Liquidity Concepts
Start with a higher timeframe map. Look at the daily and four-hour charts first to identify major swing points, consolidation zones, and clear liquidity pools. Mark the areas where price has reversed sharply in the past. These are your primary zones of interest. Then drop down to the one-hour and fifteen-minute charts to see how price interacts with those zones during active sessions. Wait for confirmation. The biggest mistake I see is traders entering before a liquidity sweep completes. They anticipate the sweep and place orders ahead of time. The market sweeps anyway but then continues in the opposite direction, stopping them out before the real move happens. Better approach: wait for the sweep to occur, watch how price reacts, and only enter if you see a clear rejection with increasing volume in the new direction. This usually means giving up two to five ticks of price, but it filters out a significant number of false setups. Use multiple timeframes to validate your bias. If the daily chart shows a strong bullish order block and the fifteen-minute chart is sweeping sell-side liquidity into that same zone, you have confluence. If the timeframes disagree, sit on your hands. Most traders overtrade because they force entries when the alignment isn't there. You'll miss moves. That's fine. Missing moves is better than losing capital on low-probability setups.
I recently worked with a trader who was struggling with consistent results using ICT concepts. His issue wasn't understanding the terms. He knew what fair value gaps and order blocks were. His problem was that he was trading every single signal on every timeframe. We cut his chart setup time down from about forty-five minutes of active monitoring per session to roughly twelve minutes by focusing only on London and New York overlap windows and only taking trades where three timeframes aligned. His win rate improved from around forty-one percent to sixty-three percent over the next month. The strategy didn't change. His filter for entries did.
Limitations And Where This Approach Breaks Down
This isn't a magic framework. Liquidity-based trading fails in several scenarios. Low-volume markets like certain forex pairs during Asian sessions or small-cap stocks with thin order books don't respect the same liquidity patterns. Algorithmic execution has made stop-hunting more sophisticated and less predictable. Large institutional players use order splitting and iceberg orders to hide their true intent, which means what you see on the tape is only a fraction of actual activity. Another hard limitation: liquidity concepts work best in directional markets. During ranging conditions with no clear trend, price will sweep liquidity levels randomly without any meaningful follow-through. You can spend an entire week getting stopped out on what look like perfect setups if the broader market lacks directional conviction. I've seen this repeatedly with commodities like crude oil during summer months when geopolitics aren't driving supply concerns. The charts look clean, the patterns are textbook, and price just churns sideways while hunting both sides of every liquidity pool. If you're relying solely on ICT concepts without understanding macro context, sector rotation, or economic calendar events, you'll underperform. A non-farm payrolls report can erase weeks of careful liquidity mapping in thirty seconds. No amount of order block analysis protects you from a central bank announcement or an unexpected earnings surprise. Always check the economic calendar before trading. Skip sessions that align with high-impact news events unless you have a specific strategy for handling volatility spikes.
The tools you need are straightforward. A platform with footprint or volume profile capabilities like Sierra Chart, NinjaTrader, or TradingView with a proper data feed. A watchlist of liquid instruments. A trading journal. That's it. Most expensive courses sell the same concepts at inflated prices. The hard part isn't the theory. It's the discipline to wait for confluence, accept missed opportunities, and manage risk when the setup isn't clear. Nobody makes money by trading more. They make money by trading less and better.