How International Wire Fees and FX Margins Add Up Faster Than People Expect
I've been sending money abroad for about twelve years now. Started with Western Union when I needed to pay my landlord in Manila while living in Seattle. Back then, the app looked nothing like it does today. You walked into a physical store, filled out a paper form, and waited. The exchange rate they gave you was already terrible, but you didn't notice because everything felt fast. Now I know better. The reason people keep using these services isn't speed anymore. It's habit and lack of alternatives at the point of need. Here's what actually happens when you send $500 through Western Union to the Philippines. The fee might show as $9.99 on the screen. That's the easy part. Then there's the exchange rate margin, and this is where most people stop doing the math. Western Union typically builds in a markup of four to six percent on the mid-market rate. You won't see this as a separate line item. It's hidden inside the rate they quote you. I did this calculation last month when sending money to my sister in Lagos. I sent 300 dollars. The fee was exactly 5.40. The rate they offered was 447 naira per dollar. The actual mid-market rate that day was closer to 468. That's a difference of about 21 naira per dollar, which works out to roughly 6,300 naira or about thirteen dollars lost. Added to the fee, I paid nearly eighteen dollars in total costs on a three-hundred-dollar transfer. That's six percent of the amount I was sending.
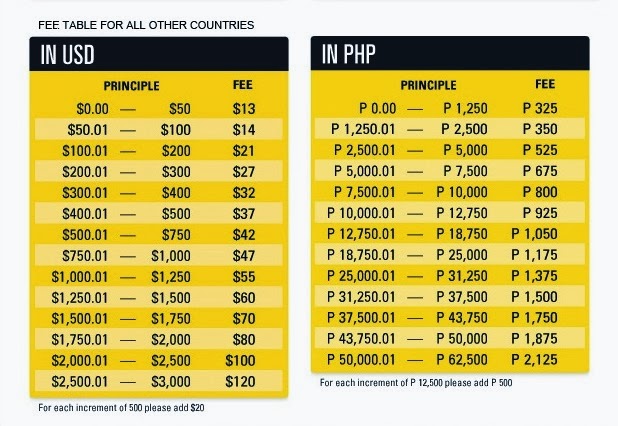
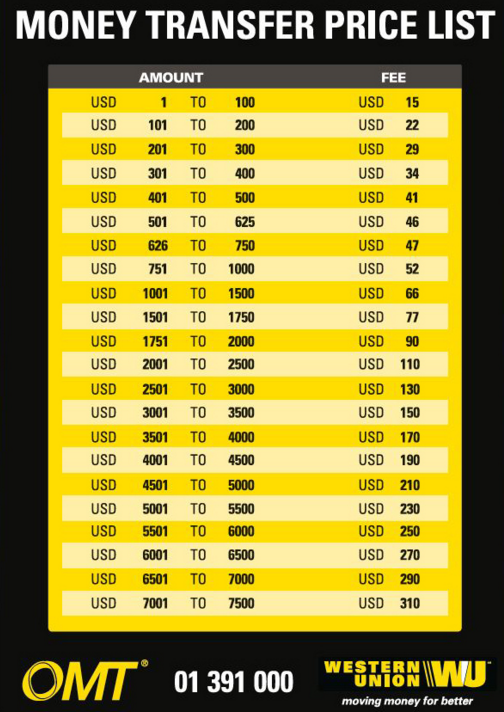
Western Union publishes their fees online, but the exchange rate they show at checkout is the one that matters. You can compare the rate they give you against XE.com or OANDA's mid-market rate to see the actual spread. Most people never do this comparison. They click accept and move on.
The Fee Structure Nobody Explains Clearly
Western Union uses two components for pricing. There's the transfer fee, which varies by country pair, payment method, and delivery option. Then there's the exchange rate margin, which is the silent cost. Some promotions advertise zero fees, but those offers usually come with worse exchange rates. A zero-fee transfer to India might still include a five percent margin built into the rate. The payment method affects your cost too. Paying with a debit card costs more than paying with a bank account or cash pickup. I learned this the hard way when I was in a hurry and used a credit card to send money to my daughter's university in London. The fee jumped from four dollars to eleven dollars, and the exchange rate was slightly worse than what I'd get with a bank transfer. Total cost came to about sixteen dollars on a four-hundred-pound transfer.
Get the Full Details

What Happens With Smaller Amounts
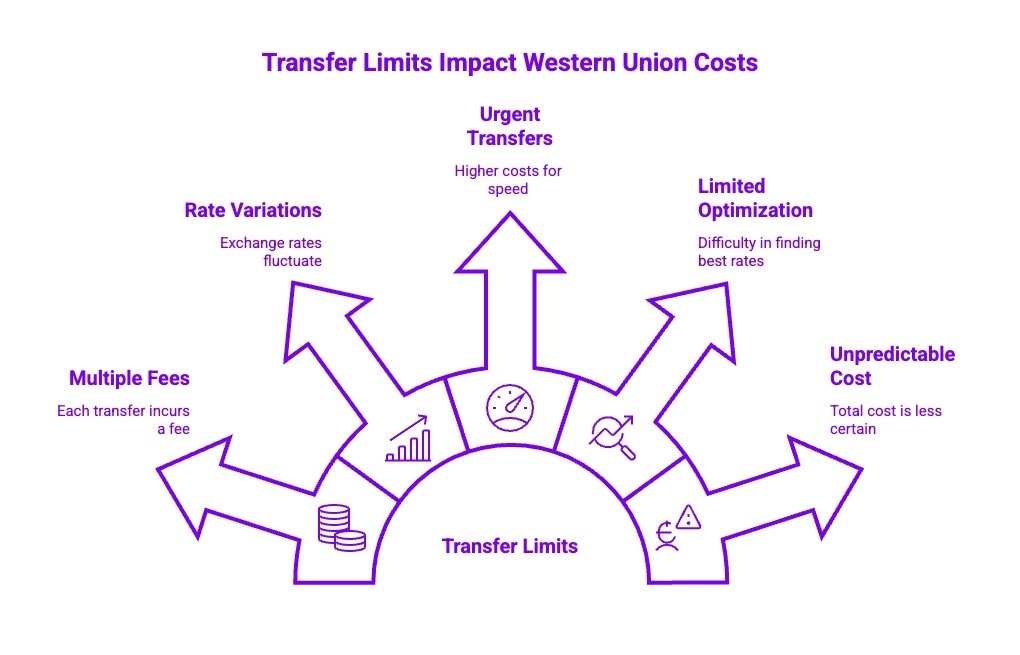
The percentage cost hits harder on small transfers. Sending fifty dollars might cost you eight dollars in combined fees and margin. That's sixteen percent. Sending five thousand dollars might cost you thirty dollars total, which is only six percent. The percentage drops as the amount grows, but the absolute dollar cost still matters for everyone. I've seen people send small amounts frequently because they think it's simpler than setting up a recurring transfer. This approach costs more in the long run. Each transfer triggers a new fee and a new exchange rate conversion. Doing five transfers of one hundred dollars instead of one transfer of five hundred dollars will cost roughly five times the fees and expose you to five different exchange rate moments.
Workarounds That Actually Help
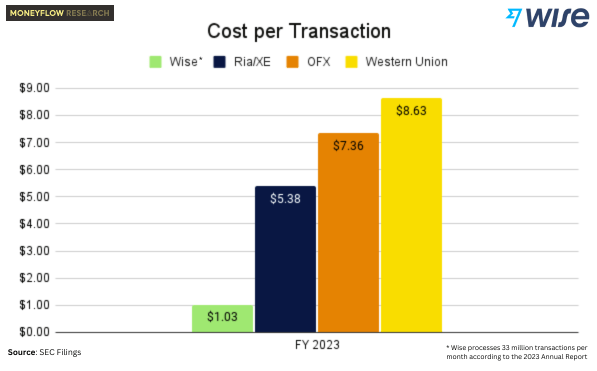
The first thing I changed was timing. Western Union's rates fluctuate throughout the day. I started checking rates at different times before committing. Sometimes waiting forty-five minutes changed the quoted rate by half a percent. On a thousand-dollar transfer, that's five dollars. The second change was comparing multiple providers. I now check Remitly, Wise, and WorldRemit before using Western Union. For Philippines transfers, Wise usually comes in two to three percent cheaper on the total cost. For Nigeria, Remitly occasionally runs promotions that undercut everyone else. Western Union remains competitive only when you need cash pickup within fifteen minutes and you're already near a location. The third change was using bank transfers for larger amounts. If you're sending more than two thousand dollars, a SWIFT transfer through your bank might cost less overall, even though it takes two to four business days. The exchange rate at major banks is usually closer to mid-market. The fee is higher in absolute terms sometimes, but the total cost is lower.
When Western Union Still Makes Sense
There are specific situations where Western Union is the right choice. Cash pickup availability in remote areas is one. If the recipient lives in a village without bank access, cash pickup is often the only option. Digital-only providers simply cannot reach those locations. Another scenario is emergency transfers where speed outweighs cost. I once needed to send money to my mother in Guatemala City the same day she had an unexpected medical bill. The clinic would not treat her until payment was confirmed. Western Union delivered to her bank account in forty minutes. Wise would have taken two business days. The extra twelve dollars in cost was worth it that day.
The Data You Should Track Yourself
I started keeping a simple spreadsheet after the Lagos incident. Each transfer I log includes the amount sent, the fee shown, the exchange rate offered, the recipient's currency amount, and the mid-market rate on that date. After six months, the pattern became obvious. Western Union was consistently two to four percent worse than Wise for the same corridors. The gap widened on weekends when interbank rates move but consumer rates lag. This tracking also revealed that some corridors are cheaper than others. Transfers to Mexico consistently cost less than transfers to India for the same amount. The difference comes down to competition and volume. Mexico has many providers competing for remittance dollars. India has high volume but also high operational costs for cash pickup networks.
What I Wish I Knew Before Starting
The exchange rate margin is not fixed. It changes based on time of day, destination country, amount, and even the recipient's bank. Two transfers to the same person on the same day can have different rates if sent at different times. I learned this when I sent one transfer in the morning and another in the evening. The evening rate was slightly worse, probably because the provider adjusted for end-of-day positioning. Another thing I missed initially is that promotional rates are not always available. The first-time user discount or zero-fee offer might only apply to the first transfer or the first ten thousand dollars sent. After that, you revert to standard pricing. I almost repeated this mistake when my sister asked me to help her set up recurring monthly support for our parents back home.
The Bottom Line on Hidden Costs
The total cost of any international transfer is the fee plus the exchange rate margin. Most people only look at the fee. That is why they think they are getting a good deal when they are not. The margin can be two to six percent depending on the provider, corridor, and timing. On recurring transfers, this compounds quickly. A monthly transfer of five hundred dollars over a year costs about sixty dollars more if the rate margin is three percent compared to one percent. I do not recommend abandoning Western Union entirely. It still has use cases. But I do recommend checking the rate against mid-market before confirming every single time. The habit of comparing takes thirty seconds and can save you hundreds of dollars over a year.
A Specific Edge Case I Ran Into
Last winter, I tried sending money to my cousin in Karachi using the Western Union app. The app showed a rate and a fee that seemed reasonable. But when I checked the rate against the State Bank of Pakistan's published midpoint, the difference was larger than expected. The margin was about seven percent that day. I cancelled and used Remitly instead, which offered a rate much closer to mid-market for that specific corridor. The workaround I now use for Pakistan is simple. I check three providers before sending. I never assume the first rate I see is the best. Sometimes the cheapest fee comes with the worst rate, and sometimes the worst fee comes with the best rate. The total cost is what matters, not either component in isolation.
Final Thoughts Without Wrapping Them Up Neatly
International remittances are expensive because the infrastructure is expensive. Cash pickup locations, compliance checks, and currency conversion all cost money. Providers build their margins somewhere. The question is whether they build it into the fee or into the rate, and how much they build in. You can influence the answer only by comparing and choosing deliberately rather than accepting the first option presented to you at the moment of need.