So You Think Instant Transfers Are Actually Instant
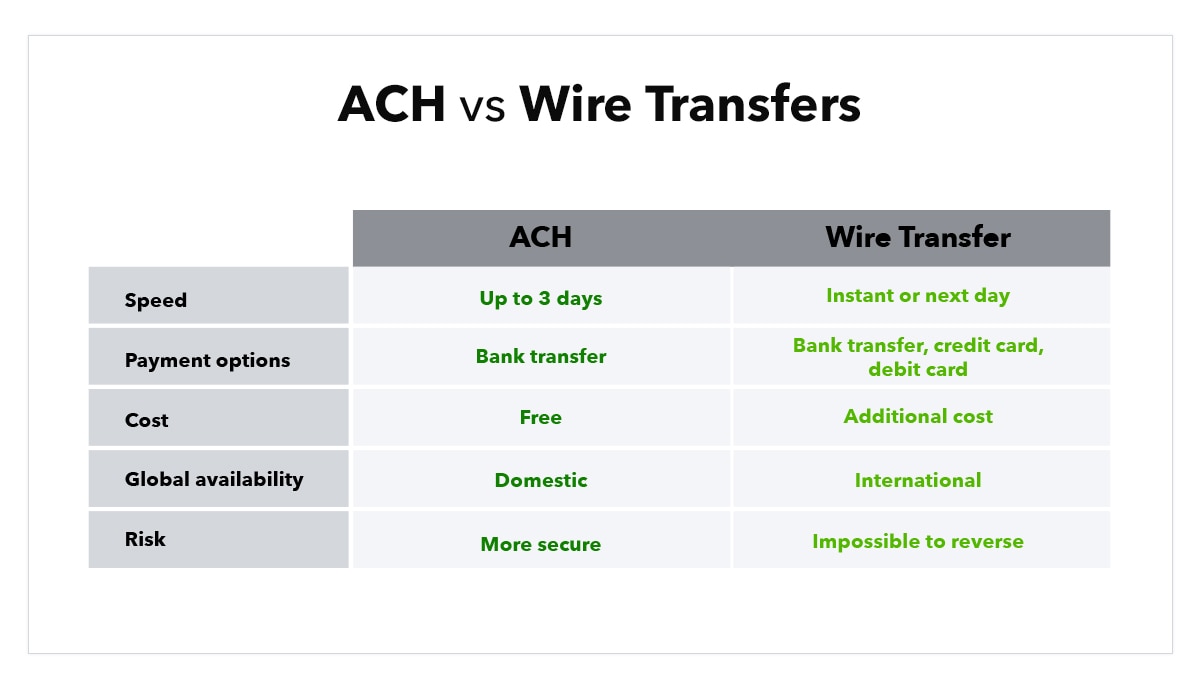
I spent three years running payment operations for a mid-market e-commerce company, and the collision between ACH holds and PayPal's instant transfer option cost us roughly $47,000 in overdraft fees and customer refunds before we figured out what was happening. It wasn't dramatic. It was just slow, boring money moving at different speeds through different pipes. Here is the basic shape of the problem. When a customer pays you through PayPal, you can request either a standard transfer or an instant transfer. The instant transfer hits your bank account within 30 minutes, usually. The standard transfer takes one to three business days via ACH. That seems straightforward until you factor in how sellers actually manage cash flow, and then the system starts eating itself.
The Hidden Cost Of Speed How ACH Holds Collide With PayPal Instant Transfers
The core issue is that PayPal does not treat instant transfers and standard transfers the same way when it comes to seller protection and hold periods. If you have a new account, or if your dispute rate spikes even slightly, PayPal may place a rolling 21-day hold on your funds. This applies to your entire balance, not just the portion sitting there from standard transfers. The instant transfers can get caught in that hold net too, or more accurately, they create an accounting illusion where you think you have available cash but you do not. I learned this the hard way in 2022. We had a product launch that went moderately viral. Orders came in fast, PayPal balance grew to about $82,000 over four days. I switched on instant transfers so we could pay suppliers and employees without waiting. Money started flowing into our checking account within minutes of each request. I authorized payroll. I paid two vendors. Then I got the email from PayPal: account under review, funds placed on a 21-day hold. The instant transfer money was technically in our bank account already, but PayPal had also flagged it as part of the held balance. Our bank saw the deposits. PayPay saw a liability. When our payroll ran, the check bounced because PayPal reversed the instant transfers while they were in review. That is not a bug, it is literally in their Seller Protection Policy document, buried in section 4 paragraph C. The workaround I used after that was brutal but effective. I stopped using instant transfers entirely during any period where we had high transaction volume or new product launches. I kept a separate operating account that received only standard transfers, and I never let that account drop below 35 percent of our typical weekly spend. I also set up a small line of credit with a community bank specifically for moments like that one, the kind where you look like an idiot in front of your employees because your payroll check bounced. The interest on that line of credit was about $200 for the longest it was ever drawn. Cheap compared to the alternative.
There are a few technical details most guides skip. First, instant transfers use a different network than ACH. They go through Visa Direct or similar real-time rails, which means they settle faster but also trigger different fraud detection logic inside PayPal's risk engine. A high volume of instant transfers coming into a newly verified account looks more suspicious to an automated system than the same volume arriving slowly through standard ACH. The system is not smart about understanding why, it just flags. Second, the timing of when you request an instant transfer relative to your seller level matters more than most people realize. If you are under the intermediate seller threshold, which requires 100 transactions and $2,000 in sales over 90 days, your instant transfers can be subject to a reserve hold of up to 25 percent of the transfer amount. This is separate from any account-wide hold. It means that even in normal operations, you are effectively losing a quarter of the speed advantage that instant transfers promise. For a business doing $10,000 a week in sales, that is $2,500 sitting in limbo every single week. Third, and this is the part nobody warns you about, instant transfers from PayPal do not always land in the account you expect. If you have multiple bank accounts linked, the instant transfer goes to whichever account PayPal's system determines is most recent based on its own internal verification state, not necessarily the one you clicked on in the app. I had this happen twice in six months. The money appeared in an old account I thought I had deactivated. By the time I caught it and transferred it back, I had triggered another fraud flag. Again, the documentation exists for this but it is not obvious unless you read the fine print of PayPal's Linked Bank Account policy.
Get the Full Details
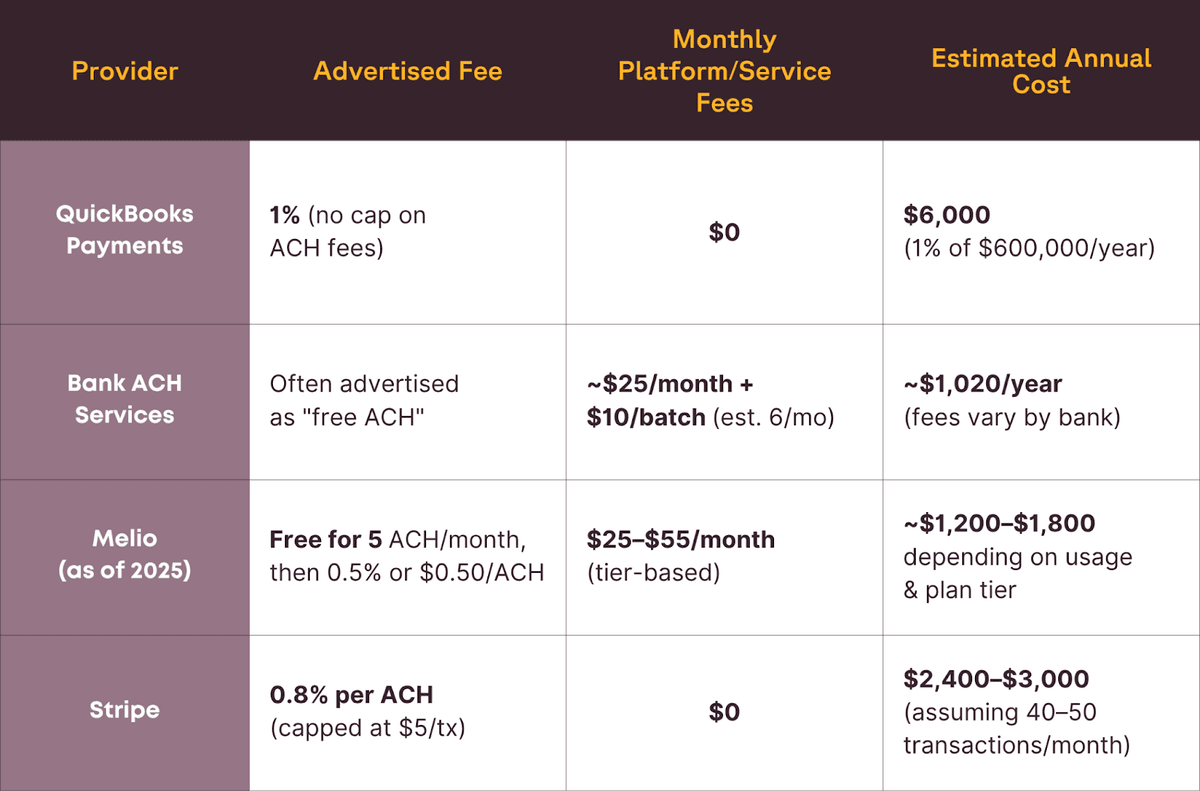
The real hidden cost here is not the fees, though those add up. Instant transfers run about 1.75 percent per transaction with a $0.25 minimum, while standard ACH is free. On $50,000 a month in sales, that is roughly $875 a month you are spending for the convenience of not waiting 48 hours. The hidden cost is the operational complexity of managing two different settlement timelines while trying to run a business, the cash flow illusions that make you think you are healthier than you are, and the occasional moment where everything looks fine right up until it is not. If you are running a small operation and your PayPal volume stays under $5,000 a month with consistent transaction history, instant transfers are probably fine. Use them. The convenience outweighs the cost. If you are scaling, or if your business has seasonal spikes, or if you are in an industry with higher dispute rates like cosmetics or digital goods, stick to standard transfers and build a cash buffer that covers at least two full ACH cycles. Keep that separate account. Get the line of credit. Do not pretend the instant option is free speed, because it is not. I still see people on forums asking whether they should enable instant transfers for their new store. The answer depends entirely on whether you understand what you are opting into, which is almost never the case. Read the policy documents. Do the math on the 1.75 percent fee against your margin. Calculate what a single bounced payroll would cost you beyond the immediate embarrassment. Then decide.