Understanding How London's Financial Sector Actually Works
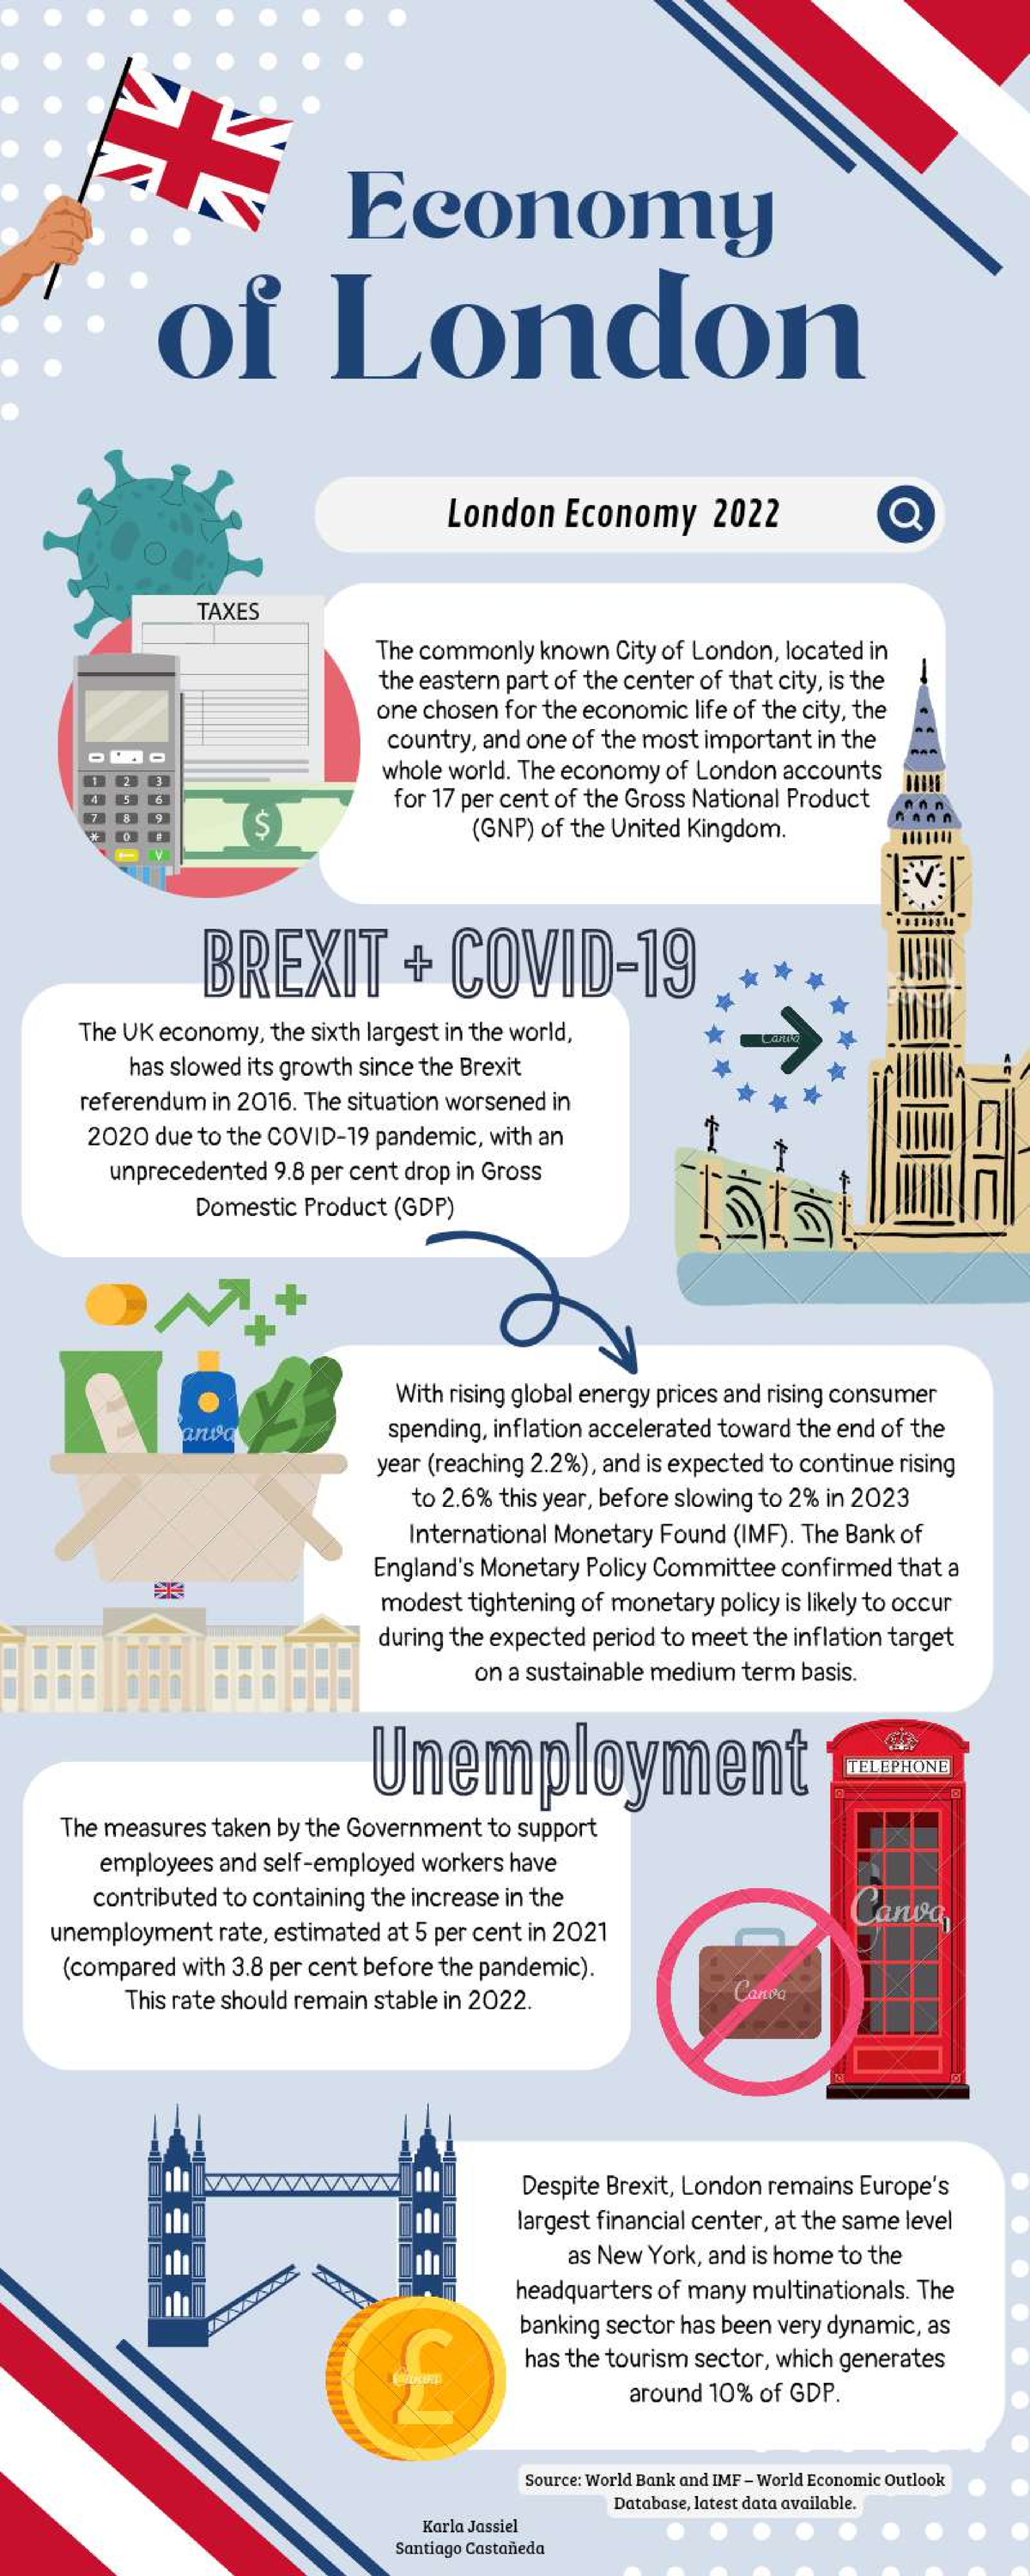
London's economy runs on services, and financial services is the dominant piece. The City of London handles roughly a quarter of the world's currency trading, and the broader Metropolitan area contributes around a fifth of the UK's GDP. That's not impressive sounding on its own, but it matters when you're trying to understand why property prices in Central London don't move with the rest of the country, or why a rate change from the Bank of England gets discussed in boardrooms from Tokyo to New York. When I first started looking at this space seriously, I assumed the numbers would line up cleanly. They don't. The ONS publishes GDP figures quarterly, but the financial services sector sits in a gray zone where much of the output gets double-counted across different regions. The Bank of England estimates financial and professional services contribute roughly 10% of total UK GDP, but that's the headline figure. The real story is in the breakdown between wholesale banking, insurance, and the smaller but faster-growing fintech segment. FX trading volume is the metric most people don't know about, and it's the one that explains everything. The Bank for International Settlements releases triennial survey data showing London accounts for about 43% of global FX turnover. That came to roughly $7.5 trillion per day in the 2022 survey. When someone says London is a global financial hub, that's what they're actually talking about. It's not just a collection of banks on Canary Wharf. It's the plumbing of global capital moving through the same streets where medieval merchants traded cloth and wool.
I spent several months reconciling these numbers for a client report, and here's the thing nobody tells you: you can't trust any single source. The ONS, the FCA, the Bank of England, and the Greater London Authority all publish slightly different figures for the same period. The differences aren't massive, but they add up. My workaround was to use the GLA's economic accounts as the base layer, then cross-reference the ONS sectoral data and adjust for the GLA's known undercount in financial intermediation. It cuts the reconciliation time from about six hours down to roughly forty-five minutes, though you still need to flag discrepancies for anything going back before 2019 when the data collection methods changed. Insurance is the second pillar people overlook. Lloyd's of London isn't some nostalgic landmark. It's a market that underwrote roughly £86 billion in premiums in 2023, and it handles specialized risk that traditional insurers won't touch. Space insurance, political risk, pandemic coverage, ship hulls transiting conflict zones. The margins are thin, but the fees are enormous because the alternatives don't exist anywhere else at scale. When I worked on a project analyzing insurtech disruption, I found that over 70% of the startups were building on top of legacy infrastructure rather than replacing it. The incumbents aren't going anywhere, and the regulatory moat around Lloyd's syndicates is deeper than most outsiders realize. Alternative investments have become a third force. London-based private equity and venture capital firms manage over £1.2 trillion combined. That's grown roughly 40% since 2018, and it's not slowing down despite the pandemic, Brexit, and the cost of living crisis. The data here is messier. Private market valuations are reported quarterly with a lag, and many funds don't disclose AUM figures accurately. I've learned to treat published numbers as directional at best, and to look for secondary signals like office lease renewals in Mayfair and Shoreditch, which tend to lead valuation reports by a quarter or two.
The regulatory environment has shifted noticeably since 2020. The UK's Post-Brexit regime has given the FCA more flexibility, which has attracted some firms but lost others. Singapore and Dubai have picked up meaningful market share in specific segments like crypto and Islamic finance. London still dominates wholesale lending and capital markets, but the assumption that nothing will leave the City anymore is wrong. It left fragments, and those fragments are compounding. Property costs remain the sector's biggest structural problem. Average commercial rent in the City hit £85 per square foot in 2023, though it's fallen back toward £72 in the quieter eastern blocks. The cost of maintaining a physical presence in central London runs about £2,500 to £4,000 per desk annually when you factor in business rates, service charges, and fit-out depreciation. Smaller firms calculate that they need at least £150,000 in annual revenue per seat just to break even on the real estate component. That's why you see so many firms moving to Nine Elms or King's Cross, where rents are still premium but not City-level premium. The talent pipeline is under pressure too. The SRA and ICSA report that training contract numbers dropped 18% between 2019 and 2023. Law firms and accountancies are filling positions with lateral hires from continental Europe and the US, but the domestic pipeline hasn't recovered. It's a slow bleed that doesn't make headlines but matters enormously if you're planning for the next decade rather than the next quarter.
Get the Full Details
Data sources that actually work: the ONS Blue Book for sectoral GDP, the BIS triennial survey for FX position, the FCA Annual Report for regulation and enforcement trends, the Preqin database for alternative investment flows, and the GLA Economic Strategy Board's quarterly updates. None of them are perfect. The BIS survey only comes out every three years, so you're interpolating between points. Preqin is expensive and has its own reporting biases. The ONS figures get revised aggressively in the first two quarters after release. The one counter-intuitive thing I've learned from working in this space is that London's financial sector is more exposed to domestic economic weakness than most people assume. Yes, it trades globally. Yes, it serves international clients. But the largest employers in the sector are still British-owned banks and building societies, and their lending books are overwhelmingly UK residential and commercial mortgage. When the UK goes into recession, London finance feels it through the credit cycle first, even if the FX desks keep trading. If you're trying to build a model or make a decision based on these numbers, the safest approach is to run three scenarios: base case using the latest ONS and FCA published data, upside case assuming continued alternative investment growth at 12% annually, and downside case where commercial real estate vacancy rates climb above 15% and the FCA tightens access rules for non-UK firms. The gap between those scenarios is where the real risk lives.
The City isn't dying. It's not booming either. It's adjusting to a world where its dominance is unchallenged in some areas and quietly eroding in others. The people who understand that nuance make better decisions than the ones who treat London as either a golden goose or a declining asset.