Market cap in digital assets is not what most people think it is
I spent the better part of 2017 and 2021 watching people use market cap as a magic number. It did not work then either. The basic math still holds, but the way you apply it to crypto, tokenized assets, and digital financial instruments requires reading between the lines of whatever dashboard you are looking at. I have seen enough portfolios blown up by people who treated market cap as a substitute for due diligence to want to be blunt about where the concept breaks. The growing significance of Assets Market Cap Understanding the Financial Tides Of The Digital Age is not a slogan. It is a practical necessity because market cap became the default shorthand for institutional allocation, fund sizing, and risk limits. If you cannot parse why a project with a two billion dollar market cap could still be dead on arrival, you will keep making the same mistake.
How to actually read market cap in the digital asset space
Start with the formula, but do not stop there. Market cap equals circulating supply multiplied by current price. That part is trivial. The part nobody teaches is how supply figures get published, and how often they lie by omission. I remember a specific incident in mid-2022 with a DeFi token that claimed a fully diluted valuation above seven hundred million dollars while its market cap dashboard showed one eighth of that number. The discrepancy came from an unlock schedule the project had buried in a GitHub commit instead of a readable vesting document. I ended up cross referencing the token contract directly against Etherscan's Verified Contract source and manually reading the release functions. It took about forty five minutes, and it saved me from treating that asset as a mid cap when it was functionally a micro cap with an artificial supply floor. The workaround I use now for any token I am considering allocating capital toward is simple enough to remember but often ignored. I check three things before I trust the market cap figure: the circulating supply calculation method, the vesting schedule, and the maximum supply if one exists. Most projects publish a circulating supply that only counts tokens in hands of retail and community wallets while leaving founder allocations, team tokens, and ecosystem reserves uncounted. That changes your risk profile entirely. A project showing a five hundred million dollar market cap on CoinMarketCap could have an effective fully diluted valuation closer to two billion dollars once those locked tokens unlock. The price impact from that unlocking event is usually immediate and brutal.
What market cap actually tells you, and what it does not
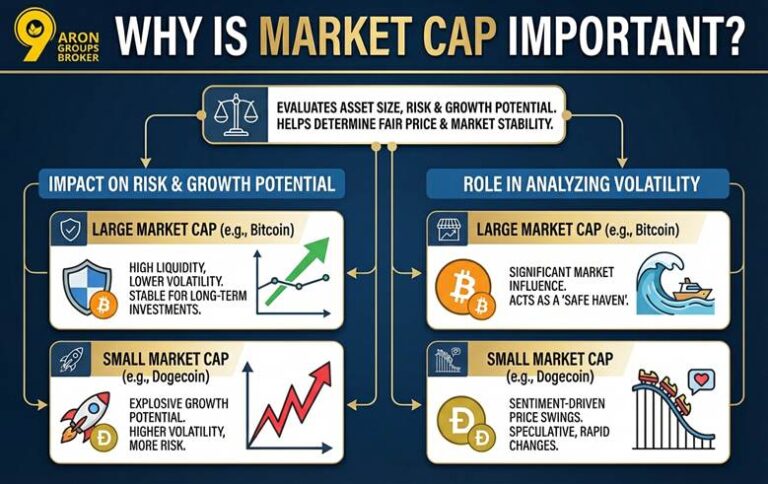
Market cap works well as a categorization tool. Large cap, mid cap, small cap, micro cap. The categories help you set expectations around liquidity, volatility, and exit liquidity. They do not tell you whether the protocol generates revenue, whether the token has utility, or whether the governance model is functional. I have watched perfectly healthy projects with strong fundamentals tank simply because someone with a large unlocked allocation dumped into thin order books. The market cap said the project was stable. The order book said otherwise. Here is a counter intuitive point that most beginners miss. Market cap is a lagging metric for price discovery but a leading metric for structural risk. When a token's market cap grows faster than its on chain activity, transaction volume, or real user count, that is usually a signal that speculation is detaching from fundamentals. You can measure this easily by comparing market cap to metrics like daily active addresses, total value locked, or protocol revenue depending on the asset class. If the market cap triples while TVL stays flat, the premium is speculative. That does not mean the price cannot go higher, but it does mean the downside risk is asymmetric.
Get the Full Details

Edge cases where market cap fails completely
There are scenarios where market cap is almost useless. governance tokens with no fee share mechanism. Stablecoin issuers. Liquid staking derivatives. Let me explain each briefly. A governance token that does not capture protocol revenue has a market cap with little connection to actual value creation. The token price trades on expectations of future control, which makes it extremely sensitive to narrative shifts and insider movements. I encountered this with a major DAO token in early 2023. The market cap sat around four hundred million dollars, but the protocol generated zero native fee revenue. The entire valuation rested on perceived influence over treasury assets worth billions. When the governance vote on treasury reallocation stalled, the market cap dropped forty percent in three days because the thesis had no cash flow anchor. The workaround I used was to treat the token as a voting rights instrument and value it separately from yield bearing assets. I stopped comparing it to revenue generating tokens and started comparing it to other governance instruments based on treasury size and voter participation rates. Stablecoin market caps are another category where the number means something different from what it appears to mean. A stablecoin with a ten billion dollar market cap does not indicate a ten billion dollar investment opportunity. It indicates ten billion dollars of liability on the issuer's balance sheet. The market cap reflects adoption and transactional usage, not equity value. People confuse the two constantly. I had a colleague attempt to build a valuation model around a major stablecoin's market cap in 2021 and got laughed out of every meeting. The fix is straightforward. Treat stablecoin market cap as a liquidity and adoption metric, not a cap table number.
A practical workflow for evaluating digital assets using market cap
I use a repeatable four step process that takes roughly ten to fifteen minutes per asset for initial screening and longer for deeper dives. The speed comes from habit, not from skipping steps. Step one is checking the supply structure. I pull the circulating supply, total supply, and max supply from the official documentation or token contract. I verify the numbers across at least two independent sources. Step two is mapping the unlock schedule. I look for vesting tables, announcement posts, and smart contract data. Step three is comparing market cap to fundamental metrics. This depends on the asset type. For yield generating protocols I compare market cap to revenue. For infrastructure projects I compare it to active users and transaction count. For meme coins I compare it to social volume and holder distribution. Step four is assessing liquidity depth. Market cap means nothing if you cannot exit without moving the price. I check the top order book levels and calculate the slippage cost for a exit position sized at roughly one percent of market cap. One practical shortcut that saves time is using on chain explorers for supply verification. Block explorers like Etherscan, BscScan, or Solana Explorer show the exact token contract data. You can verify circulating supply calculations directly from the contract functions. It is more accurate than trusting third party aggregator pages, which often update with delays or use different supply assumptions.
When market cap data will mislead you and how to catch it
Aggregator websites are convenient but they carry built-in biases. They often display market cap based on whatever circulating supply estimate the project submitted, which may exclude large locked allocations. I saw a case in late 2023 where a Layer two token had its market cap adjusted downward by sixty percent after an independent audit revealed the circulating supply figure was artificially inflated by counting tokens in bridge contracts that had not actually cleared their lock periods. The market had been trading on incorrect supply assumptions for weeks. The price corrected sharply once the data was corrected. Another common failure mode is cross chain asset duplication. Some projects deploy tokens on multiple chains and aggregators count each deployment separately when calculating total supply and market cap. This inflates the market cap number. Always verify whether the displayed market cap aggregates across chains or represents a single chain. If it aggregates, you need to adjust your analysis accordingly or the comparison becomes meaningless.

What I have learned about using market cap as a decision framework
Market cap is useful when you respect its limitations. It gives you a quick categorization signal and a rough liquidity check. It does not replace reading vesting schedules, verifying supply numbers, or understanding the revenue model. The assets that survive long term are usually the ones where market cap aligns with real economic activity. The ones that do not eventually unwind, and the unwind is rarely gentle. If you are building a portfolio around digital assets, treat market cap as the starting line, not the finish line. Verify the supply. Check the unlock schedule. Compare the number to actual usage metrics. Watch for governance edge cases. The work takes time, but the alternative is treating a dashboard number like a guarantee, and that has not worked out well for anyone I know.