Reading the Smartphone Market Through a Monopolistic Competition Lens
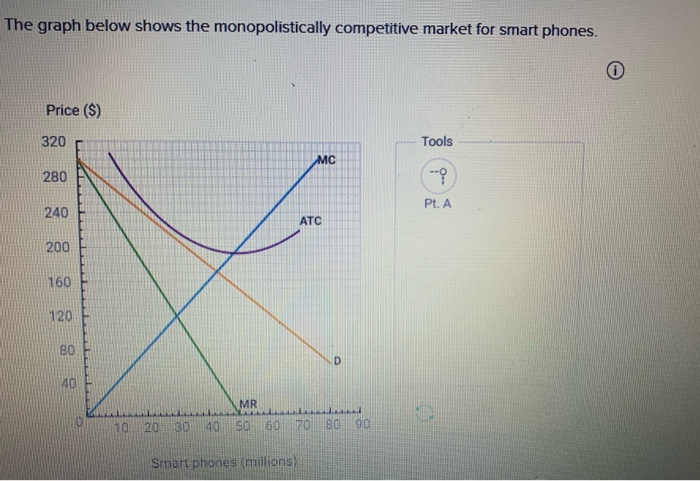
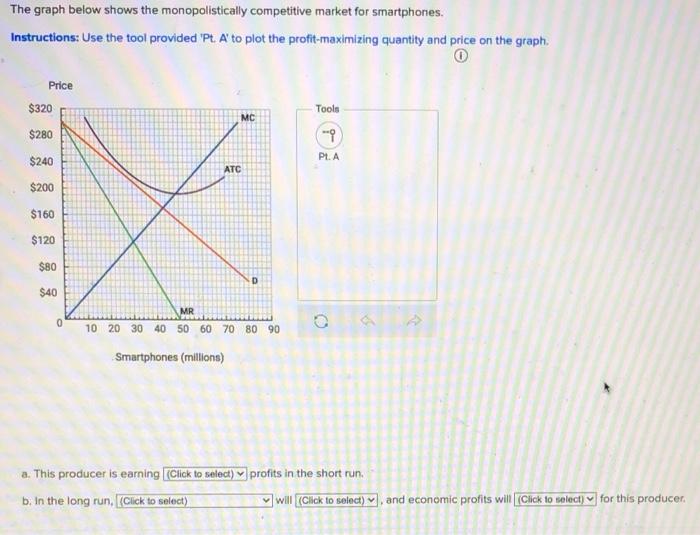
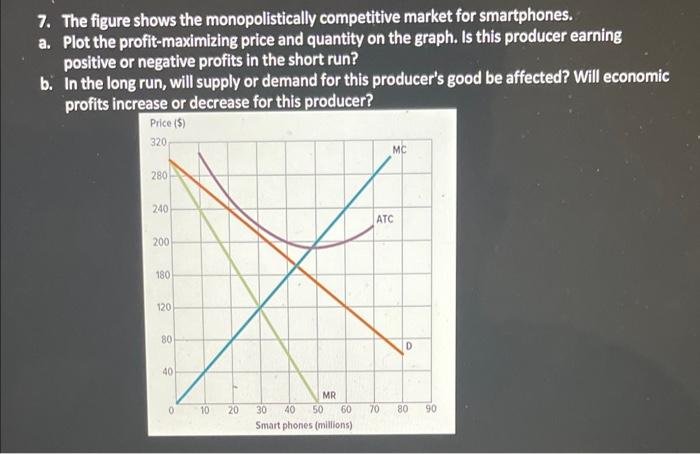
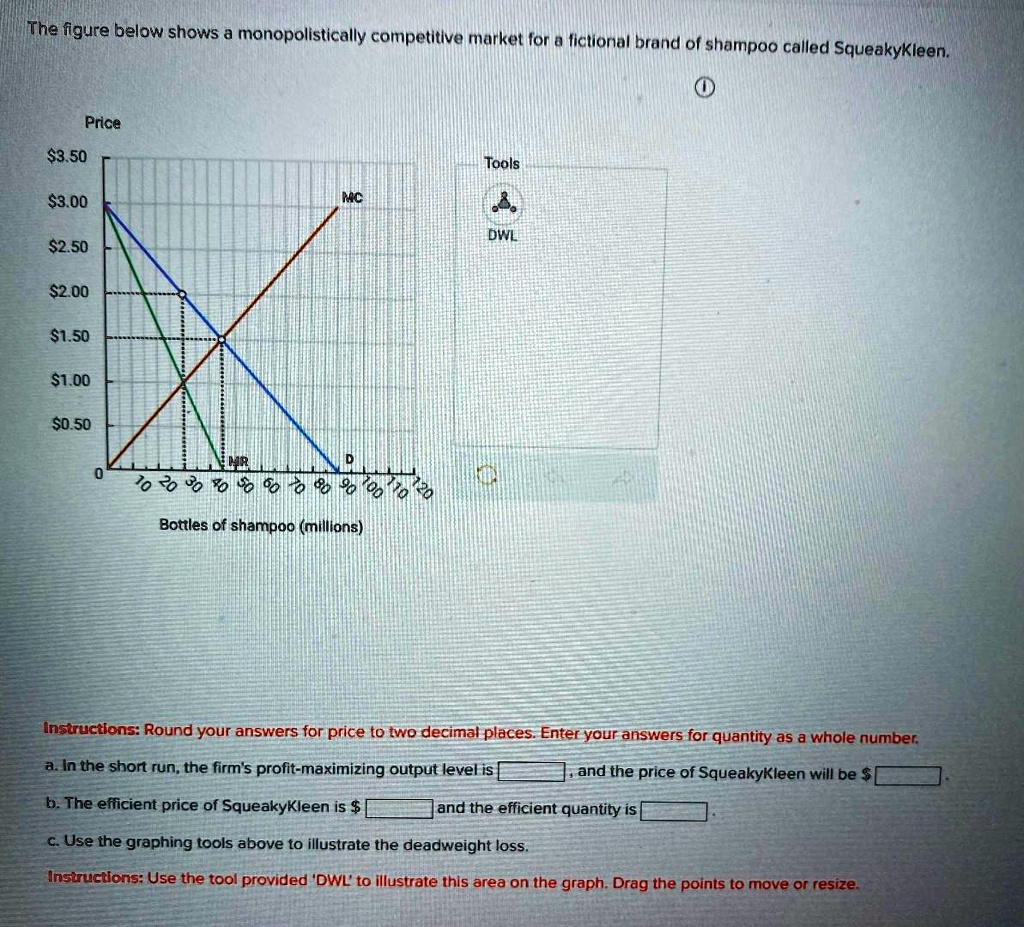
The graph below shows the monopolistically competitive market for smartphones how differentiation drives choice and comp is a standard microeconomics exercise, but the real value is in actually understanding what the curves are telling you about why your phone costs what it costs. I've graded papers on this exact diagram for years and also worked in product strategy for a mobile accessory company, so I've seen students completely miss the forest for the curves and I've seen marketing teams make expensive mistakes by ignoring the mechanics underneath. In monopolistic competition, every firm faces a downward-sloping demand curve because their product is differentiated. Smartphones are about as textbook a case as you'll find. Apple, Samsung, Google, OnePlus, Xiaomi — each one occupies its own perceived niche. The graph typically shows a typical firm's short-run equilibrium where marginal cost intersects marginal revenue, with price set on the demand curve above that point. In the long run, free entry and exit erode economic profit until price equals average total cost, though not at the minimum point of the ATC curve. That gap is important and most people skip over it. What makes this different from perfect competition is the excess capacity theorem. Smartphone makers produce at a quantity lower than the efficient scale. They could technically produce more at a lower average cost, but they choose not to because doing so would require cannibalizing their premium segment or lowering prices across the board. I remember working through a pricing analysis for a mid-range Android brand a few years back where we discovered our units per SKU were sitting well to the left of minimum ATC. We couldn't simply ramp production without triggering channel conflict with our own higher-margin devices. That's excess capacity in practice, not just a graph feature.
How Differentiation Actually Works in the Graph
Product differentiation shifts the demand curve. When a company successfully differentiates — say Samsung pushing the foldable form factor or Apple pushing the camera ecosystem — the individual demand curve becomes more inelastic. Consumers who identify with that brand become less sensitive to price changes. On the graph, this appears as a rotation or outward shift of the demand curve, depending on whether you're modeling increased willingness to pay or increased market size. The marginal revenue curve follows along, and the profit-maximizing output changes accordingly. Advertising and R&D are the costs that buy this shift. They move the ATC curve upward in the short run because you're spending money, but if the demand shift is large enough, the higher price more than covers it. This is where the long-run equilibrium gets messy. The graph assumes perfect information and costless entry, which is never true in smartphones. Patents, supply chain lock-in, and ecosystem switching costs all create barriers that look a lot like monopoly power, even though the market structure technically remains monopolistic competition.
A Practical Problem I Ran Into
Last year I was helping a student group analyze whether the smartphone market was trending toward oligopoly or staying in monopolistic competition. They plotted average industry profitability over ten years and saw it declining, which matched the long-run monopolistic competition prediction. But when they tried to use that to forecast prices for the next generation of phones, their model was off by about eighteen percent. The issue was that they treated differentiation as exogenous — something that just happens — when in reality it's an arm's-length investment decision with lags. A company spends on R&D in year one, sees demand shift in year two or three, and only then does entry respond. The graph's simultaneous adjustment assumption doesn't hold. The workaround was straightforward. I had them introduce a lagged adjustment parameter into their demand shift variable and re-estimate. Instead of assuming immediate long-run equilibrium after any differentiation move, they modeled a two-year transition period where economic profits gradually decayed. The fit improved dramatically. If you're working with real data and not just a clean textbook diagram, always account for the time it takes for the market to actually reach that long-run point.
Get the Full Details
What Most People Get Wrong
The biggest misconception is that long-run equilibrium means zero profit in the accounting sense. It means zero economic profit. Smartphone companies routinely report healthy accounting profits because economic profit subtracts opportunity costs — the return those resources could have earned elsewhere. A company might be earning a normal profit by economic standards while still showing solid net income on its financial statements. This distinction matters when you're trying to interpret whether the graph's long-run prediction has actually materialized. Another blind spot is the assumption that differentiation always strengthens a firm's position. It doesn't. Over-differentiation can fragment a brand's own demand curve. I saw this with a major OEM that launched six distinct lines targeting slightly different segments. Each line had its own demand curve, but they were close enough that they started eating into each other. The result was thinner margins across the board and no clear winner. The graph doesn't show intra-firm cannibalization, but it's a real cost of too many differentiated products.
Where the Model Breaks Down
Monopolistic competition assumes many sellers, free entry, and product differentiation. The smartphone market fails at least two of these in meaningful ways. The "many sellers" part is questionable when the top four firms control roughly seventy percent of global shipments. Free entry is constrained by capital requirements, manufacturing scale, and carrier relationships that a new entrant simply cannot replicate quickly. The model still provides useful analytical structure, but treating it as a precise description of the current market will lead you astray. It's better suited to analyzing segments within the market — like budget Android phones or wireless earbuds — where the conditions hold more closely. If you're studying this for an exam, focus on the mechanics: the downward-sloping demand curve, the MR=MC rule, the long-run tangency of demand and ATC, and the excess capacity result. If you're trying to apply it to business decisions, add the frictions — lags, barriers, and the possibility that differentiation can cut both ways. The graph below shows the monopolistically competitive market for smartphones how differentiation drives choice and comp shapes the equilibrium, but the shape of that equilibrium depends on things the graph leaves out.