Routing Numbers Are One Of Those Things You Ignore Until Something Breaks
A routing number is a nine-digit code that tells the banking system which financial institution a transaction belongs to. It's used for direct deposits, wire transfers, ACH payments, and automated bill pay. For Golden 1 Credit Union members, getting this right matters because a single wrong digit can send money to the wrong place or bounce back and forth until it resolves itself, which takes time you probably don't have. The routing number for Golden 1 Credit Union is 322272420. You can find this printed on the bottom left of your checks, listed on your monthly statements, and available on the credit union's website. It's the same number regardless of which branch you originally opened your account with, since credit unions typically use a single routing number across all locations, unlike large banks that assign different numbers by region. There are two routing numbers you might encounter. The standard ACH routing number is 322272420, which covers everyday transfers like payroll direct deposit and bill payments processed through the Automated Clearing House network. The Fedwire wire transfer routing number is 275092046. These are different because the Federal Reserve system and the ACH network operate on separate infrastructure. Using the ACH number for a wire or vice versa will cause the transaction to fail or get misrouted, and fixing that is rarely fast.
I learned this the hard way in 2022 when I was setting up an ACH auto-pay for a vendor who only accepted wire transfers initially. I gave them the Fedwire number on their direct deposit form instead of the ACH number. The payment sat in limbo for three business days, bouncing between intermediary accounts before it finally got flagged and returned. The workaround was straightforward once I understood what happened: I had the vendor change their receiving system to accept ACH, and I resubmitted using the 322272420 number. It took another two days to process after that correction, but at least the money moved the second time. Now I always double-check which network a transaction will use before submitting anything.
Why Routing Numbers Exist And How They Actually Work
The nine-digit structure follows a Federal Reserve standard. The first four digits are the Federal Reserve Routing Symbol, which identifies the Federal Reserve District and the specific processing center. Digits five and six indicate the bank's identifier within that district. The last three digits are the branch identifier or, more commonly now, a check digit calculated from the preceding eight digits using a weighted formula. The check digit uses odd positions multiplied by 3 and even positions multiplied by 1, summed together, and then the result modulo 10 should equal zero for a valid number. This checksum isn't perfect. It catches some single-digit errors and most transposition errors, but it won't catch every possible typo. I've seen people type the routing number in twice during online form entry and get two different answers, only to realize halfway through that they'd misread their own handwriting. The system accepted both because they each passed the checksum individually, even though only one was correct. That's a limitation of the design you should know about. Credit unions use the first four digits to signal their membership in a specific Federal Reserve District and their connection to the NCUA rather than the FDIC. The 3222 prefix maps to the San Francisco Federal Reserve District, which aligns with Golden 1's headquarters in Santa Clara, California. This matters less for day-to-day transactions but becomes relevant if you're processing high volumes of ACH entries or dealing with inter-institution clearing disputes.
Get the Full Details
Where To Find It And What To Do If You Can't
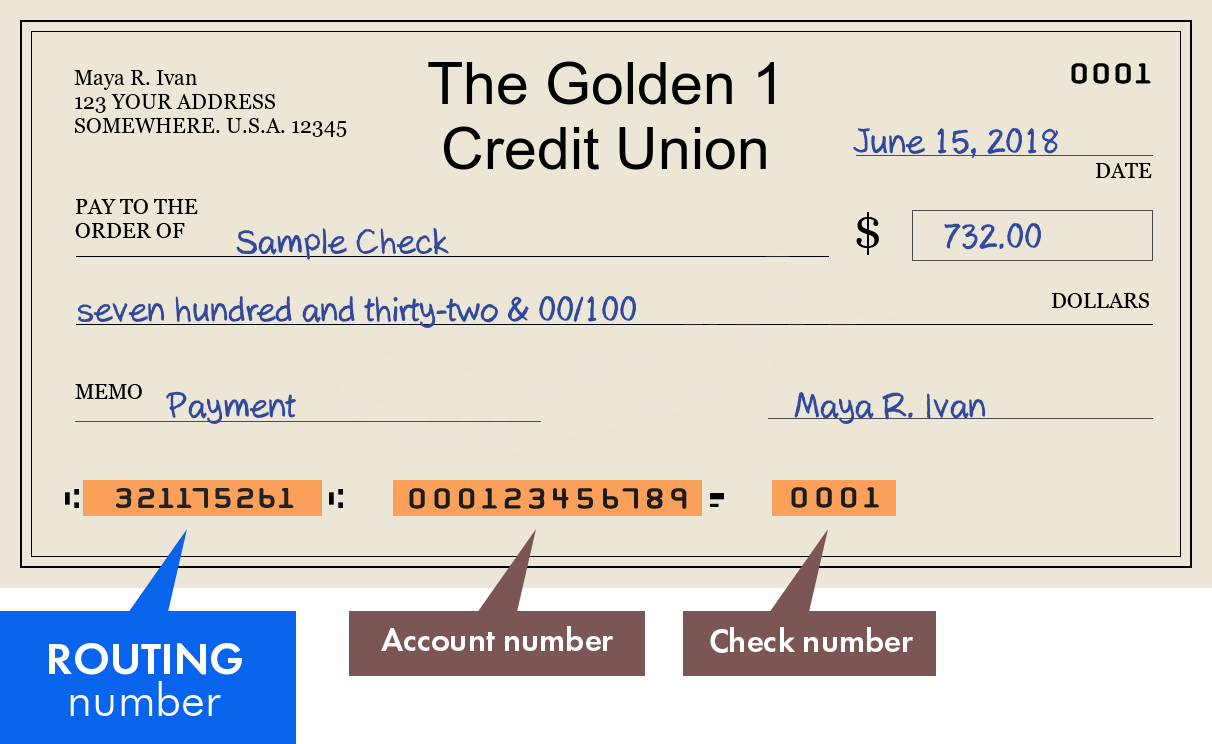
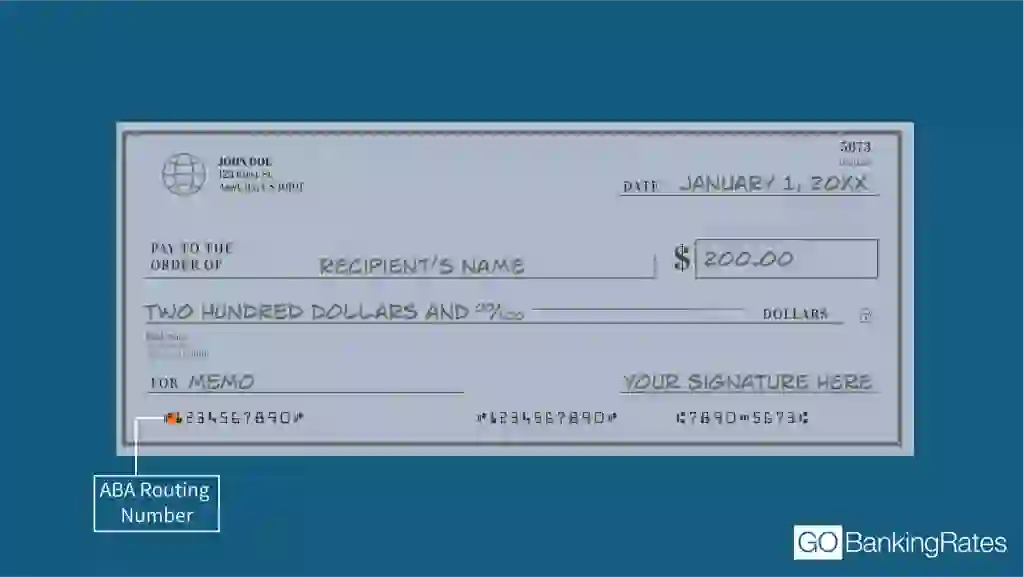
The fastest way to get your routing number is to look at any recent check. The first set of nine digits at the bottom left corner is the routing number. If you don't have checks anymore, log into your Golden 1 online banking portal and navigate to the account details page. The routing number appears next to your account number there. You can also call member services and verify it over the phone, though that adds friction if you're trying to set something up quickly. Some people try to look up routing numbers through third-party websites that aggregate banking information. These can be useful for quick reference, but I don't trust them for verification. I once had a colleague who entered a routing number from an outdated third-party site that hadn't been updated after a system migration. The number was technically valid by checksum standards, but the financial institution had migrated to a new routing code months earlier. The direct deposit he set up went into a holding pattern for five business days before the payer's bank contacted him to confirm the change. It resolved, but not without stress and a brief period where his paycheck was effectively frozen. If you've recently changed banks or your credit union has undergone a system merger, always re-verify the routing number rather than assuming it stayed the same. Institutional changes like that happen more often than most members realize, and the old numbers don't always get retired cleanly from public-facing directories.
Common Mistakes That Cost Time And Money
One of the most frequent errors is entering the routing number as part of the account number field or vice versa. Online forms sometimes label these fields confusingly, and if you copy the wrong sequence of digits, the transaction goes to the right institution but the wrong account. Fixing that means contacting both your bank and the recipient's bank to trace and reissue the payment, which can add several business days to the resolution. I've watched people lose a full week on a misrouted direct deposit because they swapped a routing number with an account number that happened to be the same length. Another mistake is assuming the routing number on an old statement is still current. Routing numbers can change during mergers, acquisitions, or system upgrades. If your credit union was acquired or rebranded, the old routing number may have been retired. Always confirm with a recent source before setting up any recurring payment or direct deposit. An expired routing number will return as a reject code, usually RT01 or RT02, but knowing what those codes mean won't speed up the reprocessing any faster than just verifying the number upfront. Wire transfers introduce a separate layer of complexity. If you're sending or receiving a wire, you need to confirm which routing number the sending or receiving institution requires. Some platforms default to the ACH number even when the transfer is routed through the Fedwire system. I had a client who sent a $42,000 wire using the ACH routing number instead of the Fedwire number. The money didn't disappear, but it landed in a suspense account at the receiving bank and required manual intervention to release. That involved phone calls, paperwork, and a two-week delay. She ended up paying expedited processing fees on both ends because the receiving institution couldn't attribute the funds to her account without the correct routing information.
What Routing Numbers Cannot Tell You
A routing number alone doesn't identify your individual account, your account type, your balance, or your transaction history. It only identifies the institution. Two people at the same credit union will share the same routing number but have completely different account numbers. This is by design, since the routing number's purpose is directional, not personal. It tells the clearinghouse where to send the money, not who it belongs to. Some people assume that because a routing number is public information, it's safe to share freely. It is public, but sharing it alongside your account number gives someone enough information to initiate transactions against your account through certain channels. I've seen this play out when members posted screenshots of their check stubs on social media with the routing number clearly visible. It didn't result in fraud in those cases, but the risk is real, especially with the rise of simulated check images and synthetic identity schemes. The routing number also doesn't tell you which network your transaction will use. A transfer to another Golden 1 member could go through ACH, wire, or even an internal ledger system depending on how the receiving institution processes it. The routing number looks the same regardless. Understanding this helps set realistic expectations about processing times. An ACH direct deposit typically posts within one to two business days. A domestic wire usually arrives the same day if submitted before the cutoff, which for Golden 1 is generally 3:00 PM Pacific Time on business days. International wires take longer and involve additional routing information beyond the standard nine-digit code.
A Practical Workflow For Setting Up Payments Correctly The First Time
When you're entering a routing number for a new direct deposit or automated payment, write it down on paper first before typing it into any form. This forces you to slow down and reduces the chance of a rushed typo. Then type it in twice and verify that both entries match exactly. If you're setting up a wire transfer, confirm the routing number with the receiving institution directly rather than relying on a form or email from an intermediary. A quick phone call to their treasury or operations desk can save you the equivalent of a small fortune in delayed payments and troubleshooting fees. Keep a record of your routing numbers for all your accounts in a secure location. Not everyone needs access to this, and it shouldn't be stored in an unencrypted document on your desktop. A password manager or a physical file in a locked drawer works fine. The point is to have it readily available when you need it, so you're not scrambling to find it during a time-sensitive payment window. I keep mine in a locked folder on my encrypted drive, and I back it up to a physical notebook that sits in my home safe. It's not glamorous, but it's effective, and it's saved me from more last-minute panic than I care to admit. There's no shortcut around verifying routing numbers before submission. The banking system is surprisingly good at catching obvious errors, but it's not infallible, and the burden of correctness ultimately falls on the person initiating the transaction. Once the money moves, undoing it is a multi-step process that involves multiple institutions and several business days at minimum. Doing it right the first time is the only strategy that actually works consistently.