Why PepsiCo's Beverage Moves Matter More Than You Think
PepsiCo doesn't just own Gatorade. It owns a sports drink ecosystem that includes Propel, Hammer Nutrition, and Pedialyte Sports, and the way these brands are positioned against each other creates genuine tension in how marketing dollars and R&D budgets get allocated. I learned this the hard way about three years ago when a client asked me to develop a launch strategy for a new electrolyte formula under the Gatorade banner, only to discover mid-pitch that our proposed flavor profile directly cannibalized a Propel SKU they had committed to protecting. The core problem isn't portfolio management theory. It's that PepsiCo's internal brand architecture forces you to navigate constraints that aren't obvious from the outside. Gatorade sits at the top as the flagship performance brand, but it's not allowed to expand into certain price tiers or consumer segments without creating internal conflict with adjacent labels. This has practical consequences for anyone working in sports nutrition marketing, product development, or distribution strategy.
The Gatorade Conundrum How Pepsicos Portfolio Strategy Shapes The Iconic Sports Drinks Future
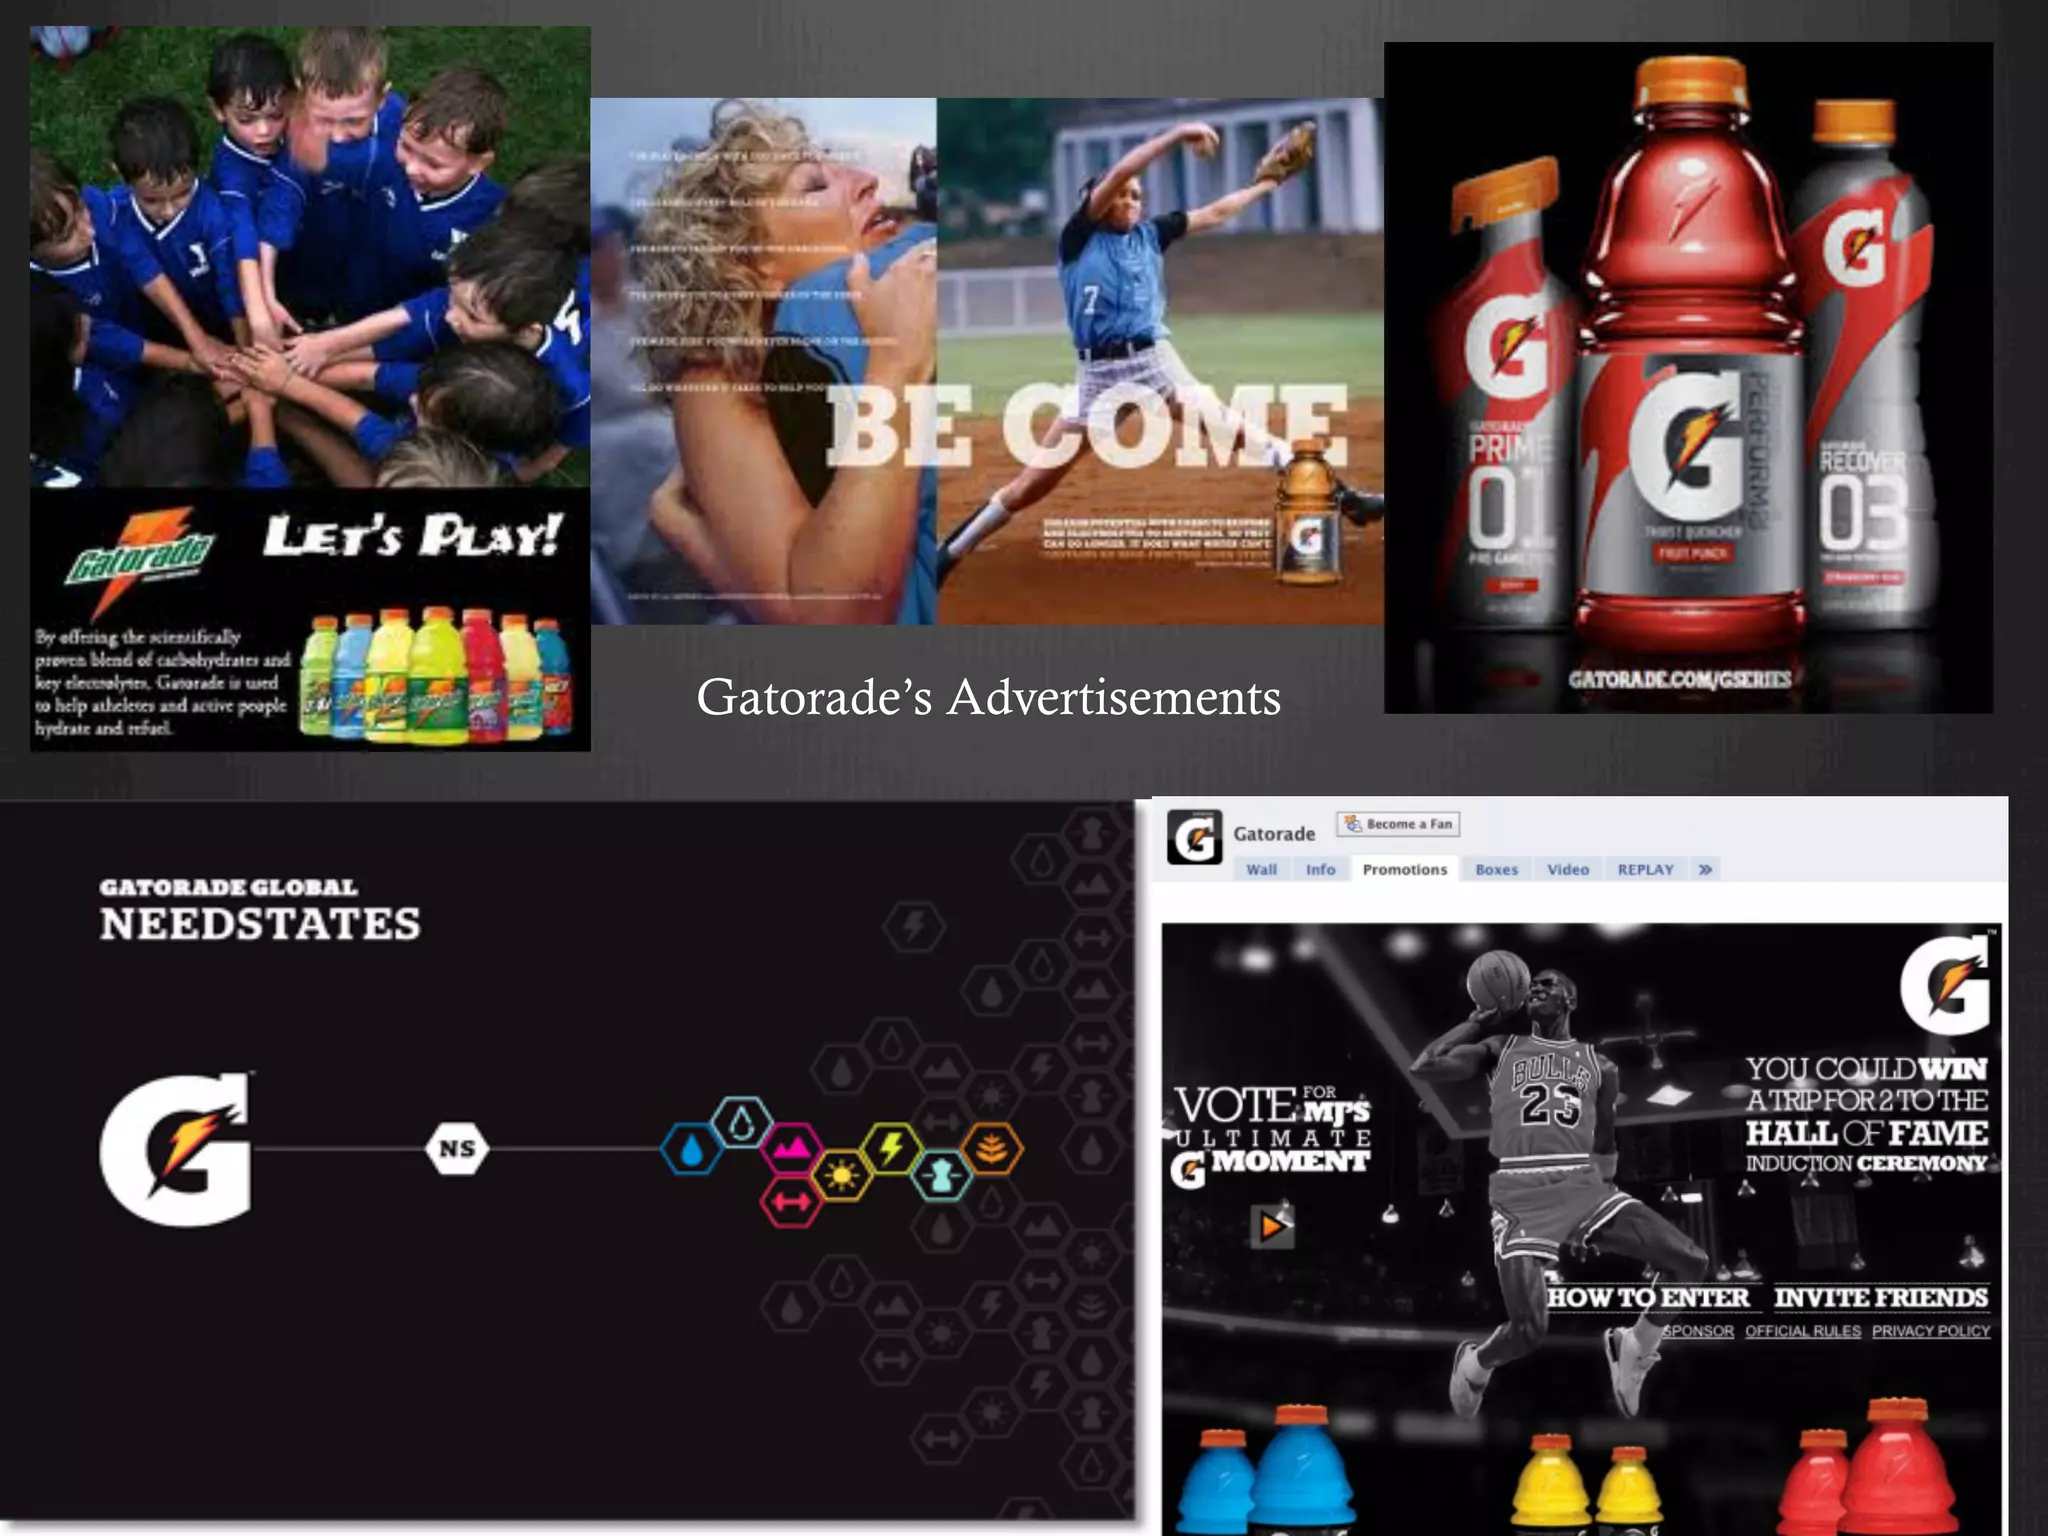
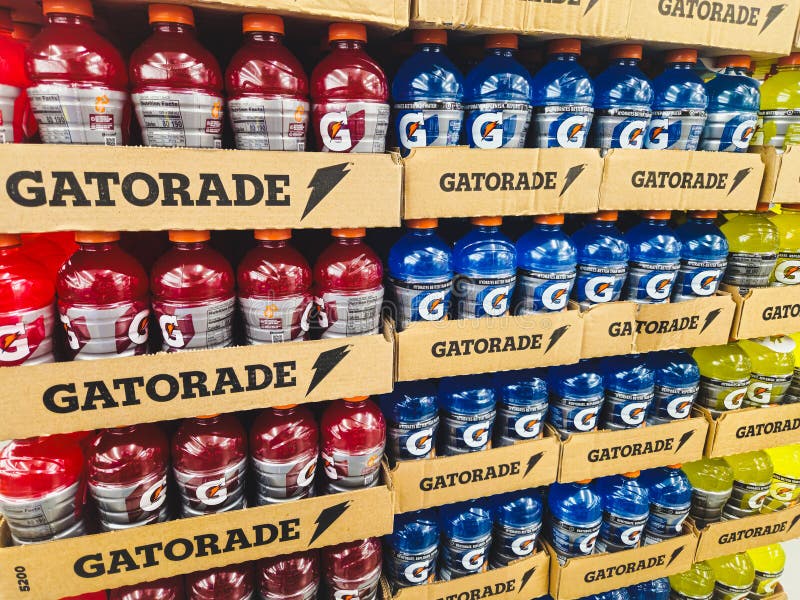
Here's how it actually works. PepsiCo evaluates each sports drink brand through a lens of category ownership. Gatorade owns the serious athlete hydration space. Propel owns the fitness and lifestyle segment at a lower price point. Pedialyte Sports (launched 2018) bridges the medical-adjacent hydration niche. Hammer Nutrition occupies the endurance sports territory, though it's positioned more as a fuel and gel brand than a pure sports drink. The strategic tension arises because consumer overlap is massive. Someone buying Propel for their morning gym session is the exact same demographic Gatorade is trying to capture with its G Series line aimed at younger athletes. PepsiCo manages this through deliberate product differentiation: different packaging formats, different price points, different retail placement strategies. Gatorade gets shelf space at sporting goods stores and stadium concessions. Propel shows up more in Whole Foods and Target. Pedialyte Sports stays in pharmacies and grocery stores near the main Pedialyte line. What most people miss about this portfolio strategy is the supply chain implication. These brands share manufacturing infrastructure and distribution networks, which creates efficiency but also creates bottlenecks. When Gatorade has a major promotional push before the NFL season, that manufacturing priority can delay Propel shipments to certain regional distributors. I've seen this cause actual stockouts in the Southeast market during a critical August sales window for a mid-market fitness retailer. The workaround involved coordinating directly with PepsiCo's regional supply chain team to schedule non-competing production runs, which added roughly two weeks to the timeline but prevented the retail relationship from deteriorating completely.
How the Portfolio Drives Product Decisions
The portfolio strategy directly influences what Gatorade can and cannot launch. PepsiCo conducted extensive consumer testing around a low-sugar Gatorade variant years ago and found that introducing it too aggressively would erode Propel's market position without generating sufficient incremental revenue. The result was Gatorade G2, a line that exists but receives minimal marketing support compared to the core Gatorade brand. This is a deliberate choice, not an oversight. Similarly, the introduction of Gatorade Zero in 2019 followed a careful calibration. PepsiCo already had sugar-free options in the Propel line and was facing competitive pressure from BodyArmor's sugar-free variants. The Gatorade Zero launch was designed to occupy the premium sugar-free hydration space without directly attacking Propel's value positioning. The pricing reflects this: Gatorade Zero sits at a higher price point than Propel, signaling to consumers that it occupies a different tier within the portfolio. The nutritional formulation strategy follows similar logic. Gatorade maintains higher carbohydrate concentrations (around 6%) compared to Propel (roughly 1%), which places them in different functional categories from a consumer perspective. This isn't accidental. It allows both products to coexist without direct substitution in most purchase decisions. The science here is straightforward: the 6% carbohydrate concentration in Gatorade aligns with research on optimal fluid and energy delivery during sustained exercise, while Propel's lower concentration targets casual hydration needs where excessive carbohydrate intake might actually be counterproductive.
Get the Full Details

What This Means for Market Positioning
If you're building a sports drink business or evaluating Gatorade as a competitive threat, understanding this portfolio structure is essential. Most new entrants position themselves against Gatorade directly, which is a mistake. The real competitive battles for PepsiCo happen internally, and external competitors can exploit gaps between portfolio segments rather than fighting the flagship head-on. BodyArmor's rise illustrates this perfectly. For years, BodyArmor occupied the premium sports drink space at a price point between Gatorade and craft beverage alternatives. They positioned themselves with natural ingredients and a potassium-forward formulation, which directly addressed a consumer segment that felt underserved by Gatorade's portfolio but wasn't quite ready to pay craft beverage prices. PepsiCo's acquisition of a majority stake in BodyArmor in 2021 was partly a defensive move to neutralize this competitive gap rather than purely an offensive play. The retail execution challenge is another area where portfolio strategy creates real friction. Store managers and buying teams at major retailers receive guidance from PepsiCo on how to allocate shelf space across the sports drink category. Gatorade typically receives the most prominent placement due to its category leadership, but this can create problems for smaller competitors and even for PepsiCo's own lower-tier brands. I worked with a regional distributor who noticed that their Propel shipments were being deprioritized at certain Walmart locations because the store's beverage manager was following PepsiCo's category planogram guidelines too rigidly. The fix involved providing the stores with shopper data demonstrating that Propel was driving incremental basket size rather than substituting Gatorade purchases, which shifted the narrative from cannibalization to category expansion.
The Limitations and Where It Breaks Down
This portfolio approach works well under normal market conditions. It breaks down when consumer preferences shift faster than the internal brand architecture can adapt. The current challenge is that the line between "serious athletic performance" and "everyday hydration" continues to blur. Younger consumers don't naturally separate these categories the way they did ten years ago. A teenager buying Gatorade for casual consumption isn't the edge-case scenario PepsiCo's portfolio model was built around. There's also a geographic limitation. The portfolio strategy is optimized for the North American market, where PepsiCo has deep distribution relationships and significant marketing resources. In international markets where Gatorade's brand recognition is lower and the competitive landscape differs, the portfolio constraints become less relevant but the resource support is also thinner. This creates an inconsistent global strategy that some competitors have exploited, particularly in European markets where local brands maintain stronger positions. The supply chain coordination issue I mentioned earlier is another persistent weakness. The shared manufacturing model that creates efficiency also creates dependency. If a production facility experiences downtime, the impact ripples across multiple brands simultaneously. This happened in 2022 when a midwestern facility faced a month-long production halt that affected Gatorade, Propel, and Pedialyte Sports inventory across multiple regions. The contingency plans existed on paper but proved inadequate for a disruption of that scale and duration.
For anyone operating in this space, the takeaway isn't that PepsiCo's portfolio strategy is flawed. It's that it creates specific predictable behaviors you can account for, and specific blind spots you can exploit if you're paying attention to the structure rather than just the surface-level brand positioning.