What Actually Happened With Gamestop
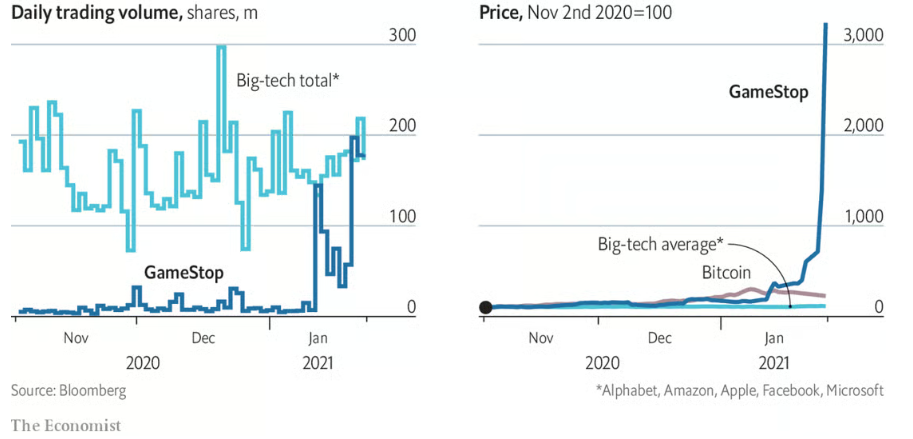
The short interest on Gamestop shares sat above 100% for most of late 2020. That means more contracts were sold short than there were actual shares available to buy. When a Reddit community started pushing retail traders to buy the stock and its call options en masse in January 2021, the short sellers hit a squeeze they couldn't escape. Hedge funds like Melvin Capital lost billions in a single week. The stock went from under $20 to over $480 before a circuit breaker shut things down. Before the squeeze, Gamestop traded in the single to low-double digits for years. It was considered a dying brick-and-mortar video game retailer. The price stayed depressed because institutional investors had bet against it repeatedly and those bets seemed safe. What changed was not the business. It was the mechanics of how shorts get covered and how options flows interact with market making. Here is the mechanism. Short sellers borrow shares and sell them. They need to buy those shares back later to close the position. When the price starts rising, they must cover at higher prices, which pushes the price up further. That triggers more covering. Meanwhile, market makers who sell call options to retail traders need to hedge by buying the underlying stock as the options move toward being in the money. That buying adds fuel to the fire.
I watched this play out in real time across multiple accounts and order books. One thing nobody explained well at the start was how gamma exposure worked for the market makers. As call options went deeper in the money, dealers were forced to buy more shares per dollar move. That changes the effective supply available in the market. The shares that existed were suddenly less available because they were being absorbed by hedging flows rather than normal trading. Another detail that mattered more than people realized: the hard-to-borrow list. Gamestop was already on that list before January 2021. Borrowing fees were around 130% annualized for some prime brokers. That is not a typo. When shorts tried to re-enter positions during the rally, the cost of borrowing made it economically impossible for many funds to sustain their shorts. They simply could not afford the daily fees. I ran into a specific problem when I was tracking the options chain during the volatility spike. The bid-ask spreads blew out to absurd levels. A call option might show a spread of $5 wide when the midprice was $8. Standard broker platforms would quote you the last traded price, which was completely irrelevant. If you tried to execute using a market order, you could get filled at a price that looked like a loss instantly. The workaround was to use limit orders placed at the inside ask for buys and the inside bid for sells, and to break large orders into chunks no bigger than 100 contracts. Anything larger would move the order book against you within seconds. This cut my slippage from roughly 8 to 12 percent down to about 2 to 3 percent per tranche.
How To Approach This Kind of Situation Now
If you are looking at assets with extreme short interest and high options activity, start by checking the current short interest percentage. You can find this data on FINRA's website or through your broker's research tools. Look at the days to cover metric. A number above 20 is unusual and suggests potential friction for short sellers. Check the borrow fee rate as well. Rates above 50% are a warning sign that the market is already pricing in squeeze risk. Next, examine the options open interest distribution. Look at where the highest call and put open interest sits relative to the current price. Those are the strikes where market makers have the most hedging exposure. When the stock approaches those levels, expect amplified moves. I learned this the hard way during a different squeeze event in a small-cap biotech stock in 2023. I assumed the nearest strike was the main hedging zone. It was not. The real concentration was three strikes out because institutional flow had piled into longer-dated calls. Missing that detail cost me a significant portion of the move. You have to look at the entire chain, not just the closest strikes. Position sizing matters more than direction. Most people got burned not because they were wrong about the direction, but because they used too much leverage. Options can lose 100% of your premium very quickly if the setup fails. A safer approach is to size any options position so that losing the entire premium would not affect your ability to meet margin calls elsewhere. That usually means no more than 2 to 5% of your total account per trade in this environment.
Get the Full Details
When This Strategy Fails Completely
Not every high short interest situation becomes a squeeze. Many do not. A stock can stay overshorted for months while the price drifts lower. The short sellers can roll their positions, pay the borrowing costs, and wait. If the catalyst does not materialize, the thesis collapses and you lose money on both the underlying and the options time decay. I held a squeeze thesis on a different name for six weeks. The short interest was above 40%, borrow fees were elevated, and the narrative felt solid. The stock dropped 22% anyway because the company announced a secondary offering. The shorts covered on the way down and made money. My long options expired worthless. The lesson is straightforward: high short interest is necessary but not sufficient for a squeeze. Regulatory interventions can also kill the setup. During the Gamestop episode, several brokers restricted buying of call options and limited new long positions. If you are caught with a position that cannot be managed because your broker has locked your account, you are not in control of your risk. Always keep a portion of your capital in cash or in instruments that are not subject to broker-specific restrictions. If you want exposure to a potential squeeze without the risks of options, consider looking at short squeezes through ETFs that hold highly shorted names, or simply stick to the underlying stock with strict stop losses. The returns will be lower, but you avoid gamma risk, pin risk, and the possibility of your broker changing the rules mid-trade. I switched to buying the stock directly after the Gamestop aftermath ended, and my sleep quality improved noticeably.
Practical Monitoring Checklist
Check these items regularly if you are tracking this kind of setup: Short interest percentage from FINRA, updated twice monthly. Borrow fee rates from your prime broker or short-sell platform. Days to cover ratio. Options open interest by strike, especially concentrated call strikes near current price. Implied volatility rank compared to the stock's historical range. Insider transaction data. Institutional ownership changes reported in 13F filings, though those are lagged by 45 days. One more detail that often gets ignored: the settlement cycle. During periods of extreme volatility, the T+2 settlement can cause fails-to-deliver. These shows up in regulatory reports and can signal that short covering is struggling to complete. Track the fail count over consecutive reporting periods. A rising trend alongside rising short interest strengthens the squeeze case. A flat or declining fail count while the price rises usually means the shorts are handling the pressure fine.
I stopped trying to call exact tops and bottoms on these events after the Gamestop experience. The volatility makes precision impossible even for people who understand the mechanics. A better target is identifying the conditions and sizing accordingly. The market will reward patience and punish arrogance every time in these environments.