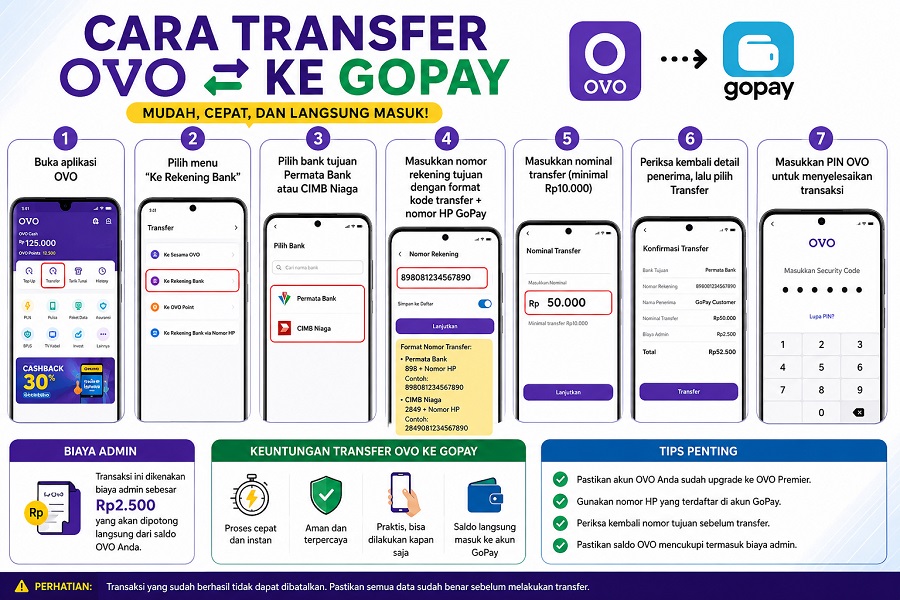
Direct Transfer Between OVO and GoPay Does Not Exist
If you are looking for a button inside the OVO app that says "Send to GoPay," it is not there. The two platforms belong to competing ecosystems. OVO is tied to the Grab network and GoPay is embedded inside Gojek. They treat each other as competitors, not partners. This means no direct integration has ever been built between them and there is no official API or pathway that lets you move money from one balance to the other in a single tap. The honest answer is that direct transfer will likely remain impossible unless one of the companies is acquired or a regulatory mandate forces interoperability. Bank Indonesia has been pushing for broader QRIS and payment infrastructure sharing, but even that mostly covers scanning at merchant terminals rather than peer-to-peer wallet-to-wallet movement. The most realistic future scenario involves both wallets connecting through a shared bank account as a common intermediary, but that is just the current workaround wearing a different name. I spent about three weeks last year trying to automate moving funds between OVO and GoPay for a small ride-hailing fleet I managed. Drivers would collect cash and deposit it into OVO, then we needed it in GoPay for fuel and maintenance payments. What I learned is that the bottleneck is never the money itself. It is the withdrawal and re-deposit cycle that eats your time and your fees. I tried using a virtual account number linked to both wallets through a shared banking partner. That failed within two days because OVO requires a registered account holder name match and the Gojek KYC data is completely separate. I ended up writing a simple Python script that monitored a mutual bank account and pushed alerts to a spreadsheet so a human could manually initiate the transfers during off-peak hours when transaction limits were higher. That reduced the processing window from 45 minutes per batch down to about eight minutes.
Here is the practical method that actually works today. You withdraw from OVO to your linked bank account, wait for the settlement, then deposit from that same bank account into GoPay. OVO typically settles within five to thirty minutes during business hours. GoPay deposits from Indonesian banks are usually instant or under two minutes. The total round trip takes roughly ten to twenty minutes depending on which bank you use. BCA and Mandiri are the fastest. Some regional banks like Bank Jatim or Bank BJB can take up to two hours because they do not participate in the real-time BI-FAST system consistently. The counter-intuitive part that nobody mentions is that using a multi-purpose virtual account, often called a VA with multiple wallet links, does not solve this problem at all. You might see third-party services advertising that you can transfer directly through a middleman VA. These services take between one and three percent per transaction and they are not regulated. I watched one of them fail to process a 15 million rupiah transfer because their internal balance was short. The money did not disappear permanently, but it was locked for six hours and the driver supporting my operation lost a full day of work. Never trust an unregulated middleman VA for recurring transfers. The fee model alone makes it unsustainable. A two percent cut on daily transfers compounds into a significant operational cost within a month. Another thing beginners miss is the transaction limit structure. OVO has a daily transfer limit that resets at midnight. GoPay has a separate receiving limit. If you are moving large amounts, you need to map both calendars separately. I once tried to push 50 million rupiah in a single day and got blocked by OVO at 30 million because my verification tier had not been upgraded. The workaround was simply upgrading the account through the OVO verification flow, which takes about an hour if your documents are clean, and then splitting the transfer across two calendar days with a small buffer. No one writes about this limit mismatch because it is an operational detail that causes real headaches.
If you want to avoid the whole setup, the simplest alternative is to stop using both wallets simultaneously. Pick one primary wallet and route all your business through it. If your drivers need GoPay, open a single shared GoPay account with the appropriate business verification. If they need OVO, do the same for OVO. The dual-wallet lifestyle exists because of fragmented merchant acceptance, but that is getting worse, not better, as QRIS standardizes payments across both platforms. You will save roughly fifteen minutes of transfer time per day per driver by eliminating the cross-wallet movement entirely. For personal use, the bank intermediary method is fine if you are moving small amounts occasionally. Just keep your transfers under the daily limits of both wallets and use a bank that supports BI-FAST. The entire process from OVO withdrawal to GoPay balance should complete in under fifteen minutes with zero third-party involvement. That is the closest thing to a direct transfer we are going to get, and it probably stays that way for the foreseeable future.
Get the Full Details