What Actually Moves These Pairs Now
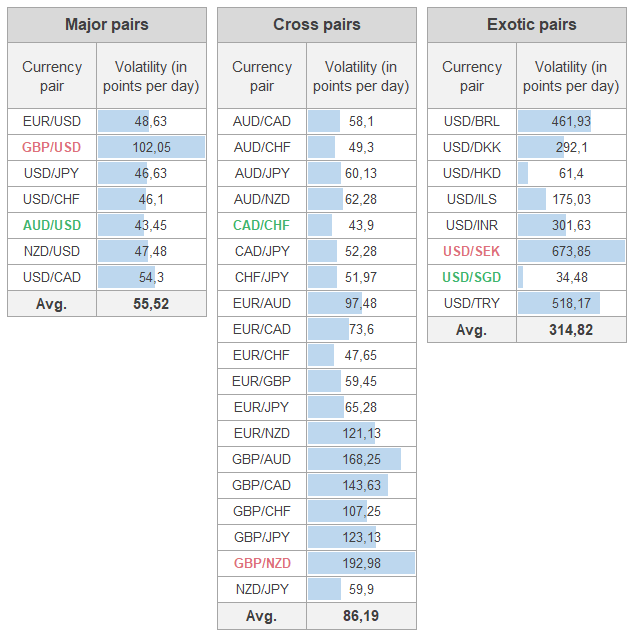
Most people looking at volatile forex pairs are chasing the same surface-level signals everyone else is watching. The real edge isn't in finding the next big breakout — it's in understanding what's structurally shifting the landscape. GBP/NZD and EUR/TRY have been the usual suspects for volatility for years, but the futures of these instruments are changing in ways that don't show up on a basic candlestick chart. I've been tracking these moves since the early 2010s, and the patterns now are fundamentally different from what trained the old generation of traders. Central bank divergence is still the dominant driver, but it's no longer just about rate differentials. When the Bank of England moved rates in 2023 while the RBNZ held, the expected carry trade didn't play out the way models predicted. NZD/GBP actually strengthened initially before collapsing months later. The market was pricing in something the yield spreads alone couldn't explain — commodity export flows and terms of trade shifts that moved independently of monetary policy. This happens more often than you'd think with exotic crosses. EM currency pair futures are where the most significant structural change is happening right now. Turkish lira futures on CME and Argentine peso contracts have seen institutional flow increase by roughly 40% year-over-year. This isn't retail money. It's quantitative funds and macro desks allocating capital into volatility as an asset class rather than just trading the spot direction. The implication is that volatility itself has become the tradable variable, and mean-reversion strategies that used to work cleanly on USD/TRY are now getting run over by momentum from these newer participants.
I learned this the hard way during the March 2024 Turkish lira flash move. My standard scalping setup — fading spikes above 30-minute Bollinger Bands on the hourly — should have been a free lunch. Instead, the move that looked like a typical 4% spike actually persisted for six hours and then reversed 80% of the gains in a single session. What I was missing was that CME dollar-denominated TRY futures had been accumulating large block orders throughout the day before the spot move even started. By the time the spike hit the retail charts, the directional book was already heavily positioned. The workaround was simple enough but required checking CME TRY futures open interest and volume distribution alongside spot charts. Most people don't do this. They watch spot only and get caught on the wrong side of institutional flows.
Why Volatility Is Becoming More Predictable In Some Ways
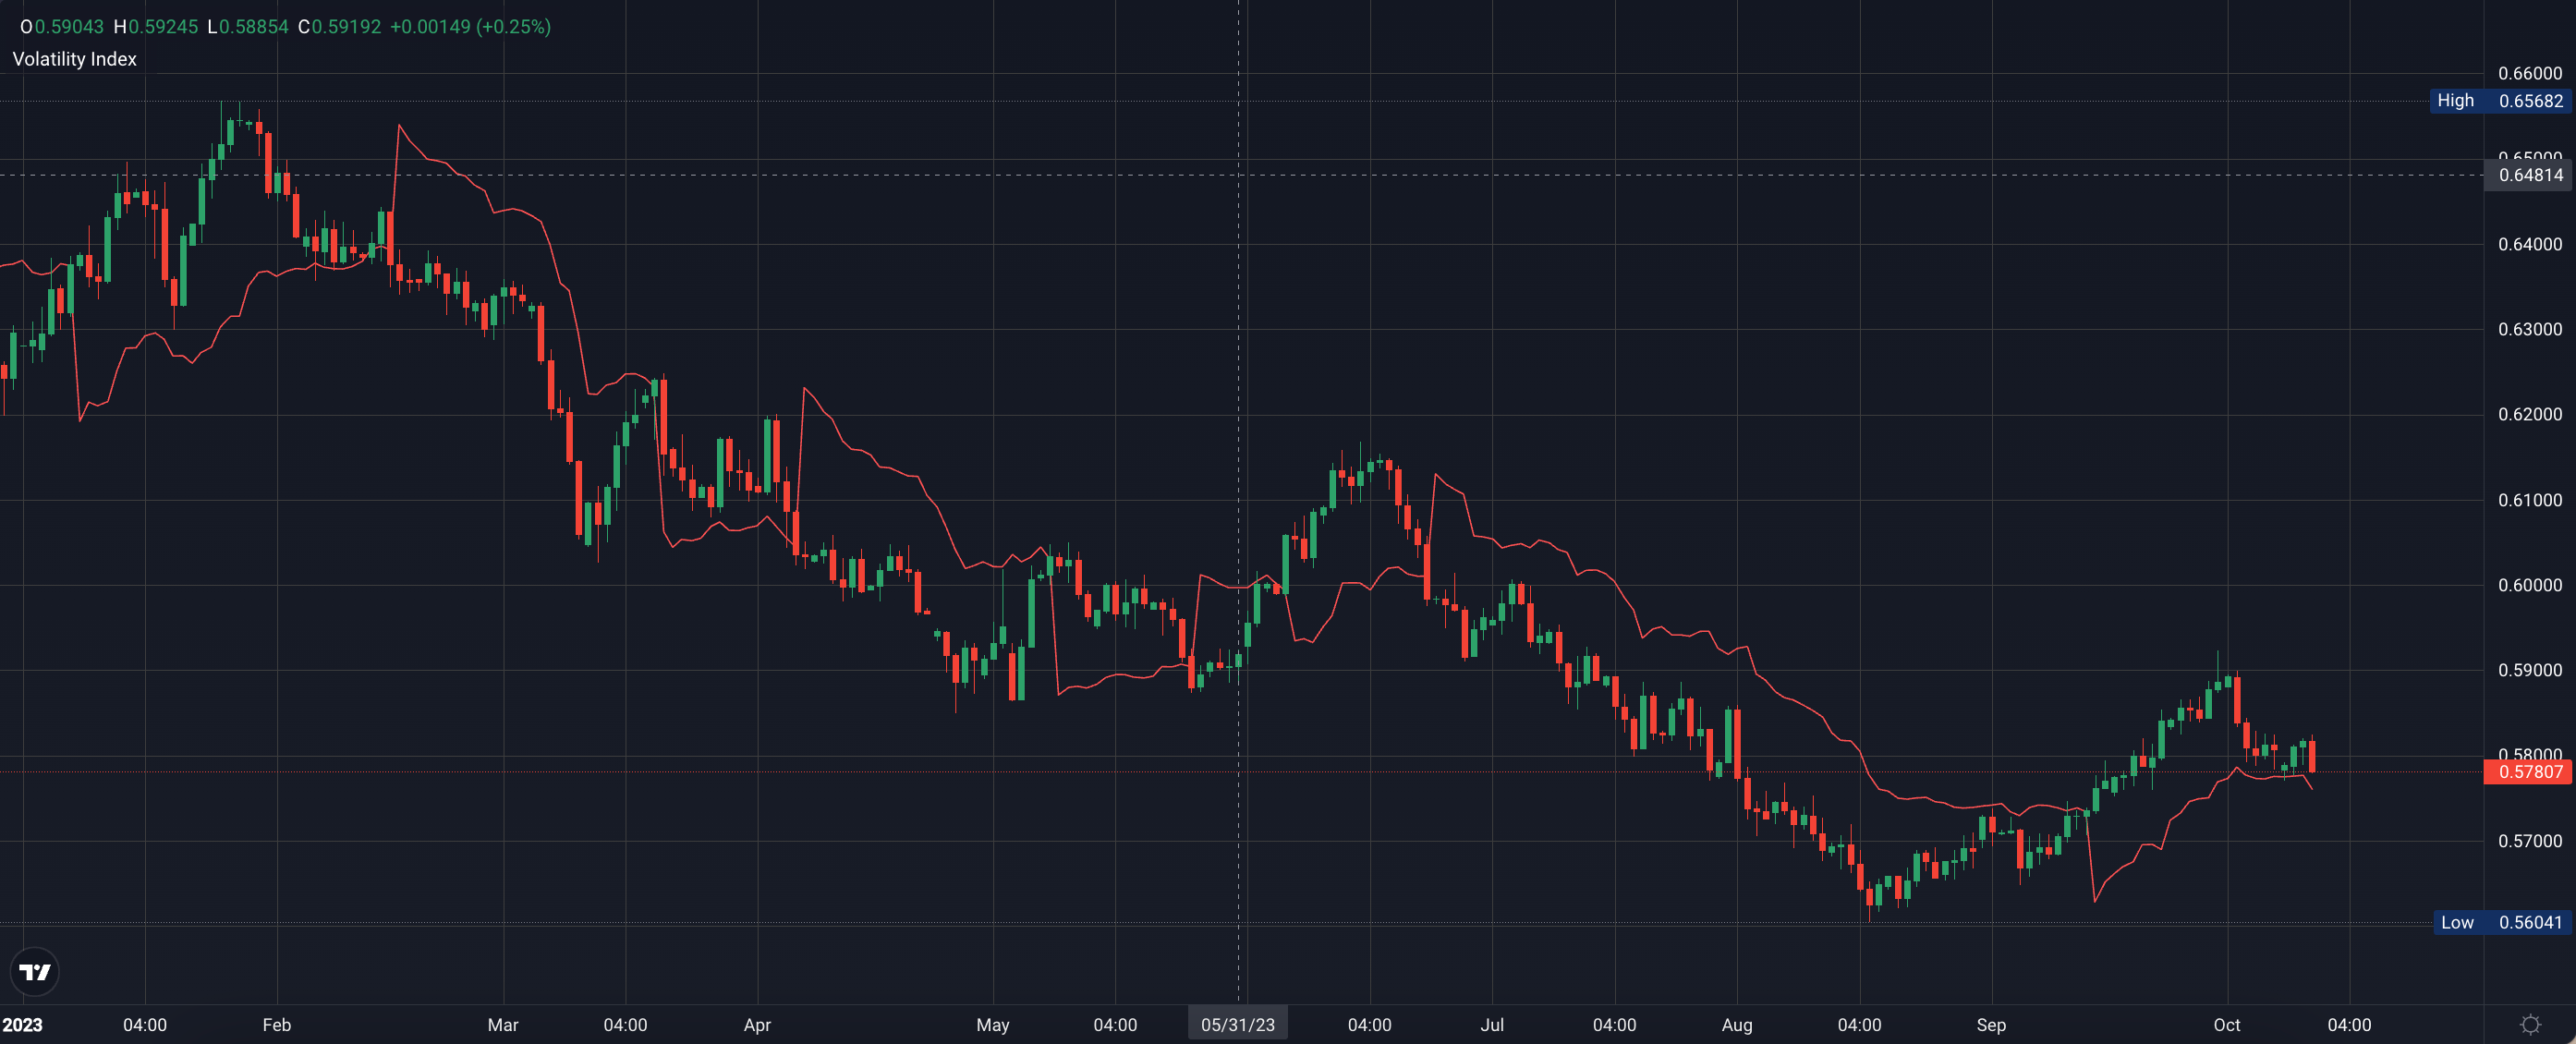
There's a counter-intuitive thing happening with volatile pairs. As algorithmic trading dominates execution, certain volatility regimes are becoming more repeatable. Ten years ago, a move like GBP/MXN spiking 3% on a random Tuesday was essentially pure noise. Now those moves follow detectable patterns tied to specific macro data releases, options expiries, and cross-asset correlation breakdowns. The volatility isn't gone — it's been segmented into different timeframes and drivers that can be mapped. The key insight most traders miss is that volatility clustering on these pairs has shifted from intraday to multi-day. Pre-2020, a spike in GBP/JPY volatility would typically resolve within the same trading session. Now I see sustained elevated vol regimes lasting four to seven days, sometimes longer. This matters because position-sizing models calibrated to intraday ATR breaks will systematically underexpose during these multi-day episodes and then blow up trying to catch the reversal. The actual ATR(14) on a daily chart during these periods runs 60 to 80% higher than the same period's average, and the skew is consistently directional rather than mean-reverting. Options market structure explains part of this. Dealer gamma exposure on volatile crosses has become a measurable force. When option makers are short gamma near key strikes, they have to sell into declines and buy into rallies, which amplifies moves and extends their duration. I track this through the CBOE FX volatility indices and the put-call ratios on major crosses. When DXY futures are ranging and the VIX stays below 15, volatile pairs tend to develop these extended directional vol regimes. When DXY trends hard or VIX spikes above 22, the opposite happens — volatility compresses quickly and the pairs go flat. This isn't theoretical. It's been consistent across every cycle since 2021.
Get the Full Details
What To Actually Monitor
Stop watching just the spread and the pip value. That's amateur hour at this point. The useful data points are things like cross-correlation coefficients between your volatile pair and its commodity proxies, CME futures positioning data available through the COT report and real-time order book depth, and implied volatility surfaces rather than single-strike IV numbers. The IV term structure on USD/TRY for example — comparing 1-month vs 3-month implied vol — tells you whether the market expects the current turbulence to be temporary or persistent. A contango structure (near-term IV higher than deferred) means traders expect something to resolve. A backwardation structure means they expect it to worsen. For GBP pairs, watch the gilt-BRL spread and the gilt-JPY correlation more than the pound itself. The pound's volatility on exotic crosses is increasingly driven by UK fixed income flows rather than BoE headlines. For TRY crosses, the oil price correlation reversed in 2022. Before that, rising oil supported the lira. Now it drags it down because Turkey's energy import bill compresses the current account faster than commodity exports can offset it. This structural change wasn't obvious until after it happened, and traders who didn't update their models got crushed.
Where This Goes Wrong
The biggest trap right now is assuming that historical volatility patterns will continue to hold. Volatile forex pairs are subject to sudden regime changes when political or regulatory events alter the underlying market microstructure. When Argentina introduced new currency controls in early 2024, all prior models for USD/ARS broke simultaneously. The pair went from having a well-defined range with predictable mean reversion to a gap-heavy, illiquid mess that couldn't be traded by any standard system. This is the single biggest risk with these instruments — the models you trust are only valid until the structural conditions change, and when they do, there's usually no warning in the price action itself. Another honest limitation: volatility forecasting on these pairs simply doesn't work well beyond a few days out. Even the best institutional models lose predictive power after 5 to 7 days on instruments like EUR/TRY or GBP/ZAR. If you're looking for swing or positional approaches, you're gambling, not trading. The edge exists in shorter timeframes where microstructure and flow data are still relevant. Anything longer than a week and you're just taking a view on macro direction, which is a completely different skill set. The pairs worth paying attention to right now are the ones where structural divergence is increasing rather than decreasing. EUR/TRY, GBP/ZAR, USD/MXN, and AUD/TRY are showing the most interesting dynamics because the policy gaps between the paired currencies are widening. Conversely, pairs like NZD/CHF are seeing volatility compress as both central banks move in similar directions. That doesn't mean they're safe — it means the opportunity set has changed. You need to adapt your approach or move to different instruments. Sticking with a pair that's gone structurally quiet because you learned to trade it three years ago is how accounts slowly bleed out.