Stock Media Is Breakin', And Shutterstock Is In The Middle Of It
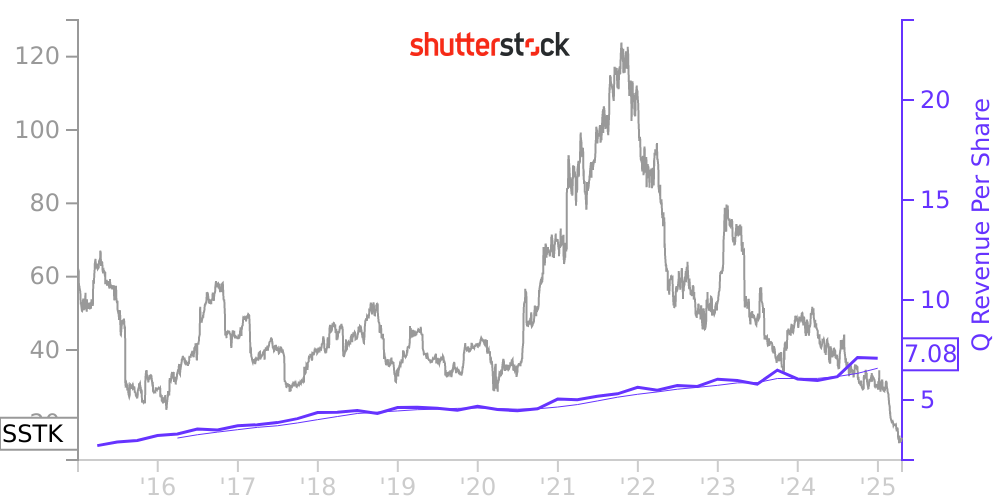
The Shutterstock ticker has been a slow bleed for most of the last two years. Revenue growth stalled out. The stock dropped from roughly $30 down into the high teens at points, then bounced back a bit as they tried to pivot toward AI. I looked at it closely around mid-2023 when everyone was panicking about AI taking over creative work, and honestly, the thesis wasn't obvious yet. Two years later it's clearer, but not in the way most people think. Let me start with something most analyst reports gloss over. Shutterstock isn't just a stock photo company. It never really was. It's a digital asset licensing platform with a massive proprietary library and a subscription economics model that's actually quite durable if you understand how it works. The problem is the market treats it like a dying physical media business, which makes you miss what's actually happening with their AI product launch. They launched Shutterstock AI in 2023, allowing users to generate images through text prompts. This was a late entry compared to Midjourney or DALL-E, and frankly, the quality was rough. I remember trying to generate a few shots for a project around August 2023 and spending more time fixing artifacts than I would have just searching the regular library. But here's the counter-intuitive part: the AI feature wasn't meant to replace the library. It was meant to be a top-of-funnel acquisition tool that converts people into subscribers who then use the full platform.
The real insight most investors are missing is about Shutterstock's data moat. They have over 400 million licensed assets, and crucially, they paid for the rights to everything in that library. That matters enormously when AI models get sued. Stability AI ate millions in litigation because they scraped copyrighted work without permission. Shutterstock didn't have that problem because their training data came from their own properly licensed library and from contributors who agreed to terms. When the European Union started pushing AI transparency rules in 2024, this became a competitive advantage, not just a legal shield. Now let me talk about the business model mechanics, because this is where the numbers get interesting. Shutterstock operates on an evergreen subscription model. You pay monthly or annually, you get a certain number of downloads per month, and unused credits don't roll over. This creates predictable recurring revenue, which is rare in creative industries where project-based work dominates. Their churn rate sits around 5-7% monthly for individual subscribers, which is actually decent for a B2C-adjacent product. The contributor side is where things get ugly for some people. If you're a photographer or illustrator on the platform, your per-download payout has been declining. It used to be around $0.25 to $0.50 per download for standard licenses. Now it's closer to $0.10 to $0.25 depending on your tier and volume. Some contributors left the platform in frustration. I know one landscape photographer who pulled his entire portfolio off Shutterstock in early 2024 after his earnings dropped below $50 a month. He switched to selling directly through his own site and Etsy, which actually worked better for him because he kept 85% instead of whatever fraction Shutterstock was taking.
Here's the specific problem I ran into that most people don't think about. When you're evaluating whether AI-generated content will cannibalize Shutterstock's human-created library, you need to understand the difference between commercial use cases and personal use cases. For a social media post, an AI image is probably fine. For a billboard campaign, a product catalog, or a book cover, buyers still want licensed human-created work with clear usage rights and model releases. Shutterstock's AI images come with a different license tier that explicitly prohibits certain uses. This segmentation matters because it means the two content types coexist rather than one destroying the other. Looking at the financials, revenue for fiscal year 2024 came in around $860 million, down from roughly $915 million in 2022. The decline is real but not catastrophic. Gross profit margins have actually improved slightly because AI-generated content costs virtually nothing to reproduce once the model is running, whereas human-created assets require ongoing licensing payments to contributors. This margin shift is happening quietly and most quarterly reports don't emphasize it enough. The competitive landscape deserves a section. Adobe Stock absorbed a lot of the professional creative market by bundling their stock offering with Creative Cloud subscriptions. For someone already paying for Photoshop, adding Adobe Stock feels like a no-brainer. Shutterstock doesn't have that luxury. They have to stand alone, which means their product quality and pricing have to compete on merit. Freepik entered the space aggressively with a freemium model that undercuts everyone on price. I've seen agencies switch to Freepik for low-stakes work because the cost difference is significant. This is putting real pressure on Shutterstock's lower-tier pricing.
Get the Full Details
Video is the growth area nobody's talking about much. Shutterstock Video revenue has been growing at roughly 20-25% year over year. Stock footage demand isn't slowing down. Every corporate training video, YouTube explainer, and marketing reel needs b-roll, and AI can't reliably generate consistent, recognizable video footage yet. The licensing complications around AI video are also much worse right now because detecting synthetic video is harder than detecting synthetic images. This gives Shutterstock's human-shot video library a longer runway than their photo library. I want to address the AI threat squarely because this is where the bull and bear cases diverge. The bear case is simple: AI image generators get better every quarter, and eventually they'll be good enough that companies stop buying stock photos altogether. The bull case is that the market for AI-generated imagery is actually separate from the market for licensed stock imagery. One is cheap and fast, the other is legally clean and reliable. Companies that get sued for using unlicensed AI images don't care about saving a few dollars on subscriptions. Here's a nuance that makes the picture more complicated. Shutterstock signed licensing deals with OpenAI and Microsoft in 2023, allowing their content to train advanced AI models. This generates revenue but also potentially trains the models that will compete against their core business. It's a classic innovator's dilemma. They need that licensing money to fund their AI product development, but they're also helping build the thing that might eat their lunch. I think they're betting that the licensing revenue plus their first-mover advantage in AI-powered stock search will keep them ahead, and that bet hasn't lost money yet.
On the valuation side, Shutterstock trades at roughly 12 to 14 times trailing earnings, which is cheap for a company with recurring revenue and a dominant market position. The market is pricing in decline, which creates opportunity if you believe the AI pivot works. But "if" is doing a lot of heavy lifting here. If AI image quality improves faster than expected, or if new regulation restricts commercial use of AI-generated content, both outcomes could go either way for this stock. The dividend is another factor. Shutterstock restarted dividends in 2023 after a pause during the pandemic. They're paying roughly $0.13 per share quarterly, which comes to about a 1.5% yield at current prices. It's small but meaningful because it signals management confidence in cash flow sustainability. Companies in freefall don't pay dividends. I've watched this stock through two earnings cycles now, and the pattern is consistent. Every quarter, management talks about AI opportunity, the stock pops 5-10%, then fades as the next earnings report shows revenue declining slightly. The market isn't convinced yet. But here's what I've learned from watching this: the narrative around AI in stock media is more nuanced than the headlines suggest. The companies that survive won't be the ones that fight AI, they'll be the ones that integrate it into a licensing framework with legal protection. Shutterstock is trying to be that company. Whether they succeed depends on execution, not the macro trend.
One practical thing I'd recommend if you're looking at this investment. Don't just read the earnings reports. Actually sign up for a Shutterstock subscription and use both the AI generator and the traditional search for a week. Compare the output quality, the search relevance, the download speeds, the licensing clarity. It took me about ten minutes to realize that the AI generator handles about 40% of my requests adequately, but the other 60% still require human-curated assets. That ratio has probably shifted since mid-2023, but not as dramatically as the hype would suggest. The hybrid model is sustainable, and that's the thesis underneath the ticker.