Understanding Monthly Budgeting For New Jersey Expenses
New Jersey is one of the more expensive states to live in, and that's not going to change soon. Property taxes, insurance premiums, and general cost of living adjustments keep climbing every year. If you're trying to figure out where your money goes each month, you need a system that actually accounts for real numbers instead of generic rules of thumb. I put together a practical framework after watching too many people blow through their budgets because they estimated housing costs wrong or ignored the tax drag that hits New Jersey residents harder than anywhere else in the Northeast. This guide is a working document, not a set of aspirations. I designed it around actual expense categories that show up in New Jersey household budgets, with projections built in so you're not just planning for today. Here's how it works in practice. Start with the fixed costs. That means your housing, property taxes, insurance, and any debt payments. In New Jersey, property taxes alone can eat 1.5 to 2 percent of your gross income for a typical middle-class home. I had a client in Morris County who was budgeting $2,200 a month for housing but his actual tax bill came in at $3,100 when the reassessment hit. He'd been using the previous year's numbers. The workaround was straightforward: pull your actual tax assessment from the municipality's site each January and update the budget template. Takes ten minutes and saves you from a $900 surprise every spring.
Track variable costs by category, not by month. Most people budget by saying they'll spend so much on groceries or utilities and move on. That doesn't work in New Jersey because utility costs swing wildly with weather. My approach is to track your variable spending in rolling three-month averages. You'll see patterns that a single month masks. For example, my gas bill in northern New Jersey runs about $180 in January and February, drops to $65 in May, spikes again in October, and hits $200 in December. If you budget $120 a month flat, you'll be short twice a year. Build in a 4.5 to 6 percent annual cost adjustment. New Jersey's inflation rate on everyday goods has tracked above the national average for the past several years. Food, healthcare, transportation -- all of it moves faster here. When I set up these budgets, I apply a compounding adjustment to next year's projections based on your current spend. It's not perfect, but it keeps you from being blindsided. People who use static numbers typically find themselves $200 to $400 short per month within 18 months. Include the New Jersey-specific line items. Most generic budget templates don't have rooms for things like NJ Clean Energy Program rebates (which can offset solar installation costs), municipal school contributions for families with non-public school students, or the state's high auto insurance premiums that run 30 to 40 percent above the national average. I've seen people miss $1,200 to $2,400 annually in potential savings just by not tracking rebate programs their utilities offer.
One thing this guide doesn't do well is account for sudden income changes. If you're self-employed or your income is seasonal, the fixed allocation percentages break down quickly. In those cases, switch to a zero-based budget where every dollar has a job before the month starts. It's more work upfront -- maybe 45 minutes per month instead of 15 -- but it's the only way to stay accurate when your income isn't predictable. I also don't handle multi-generational households well. The per-person allocations assume a standard nuclear setup. If you're supporting parents or adult children under roof, you need to manually adjust the dependents category rather than relying on the standard multiplier. The hardest part of making this work is consistency. Most people fall off after six weeks because they skip the update cycle. Set a calendar reminder for the first Sunday of every month. Thirty minutes is all it takes to plug in actual spending, adjust projections, and catch categories that are trending. After a year of this, you'll know your numbers within about five percent, which is as good as it gets for household budgeting.
Get the Full Details

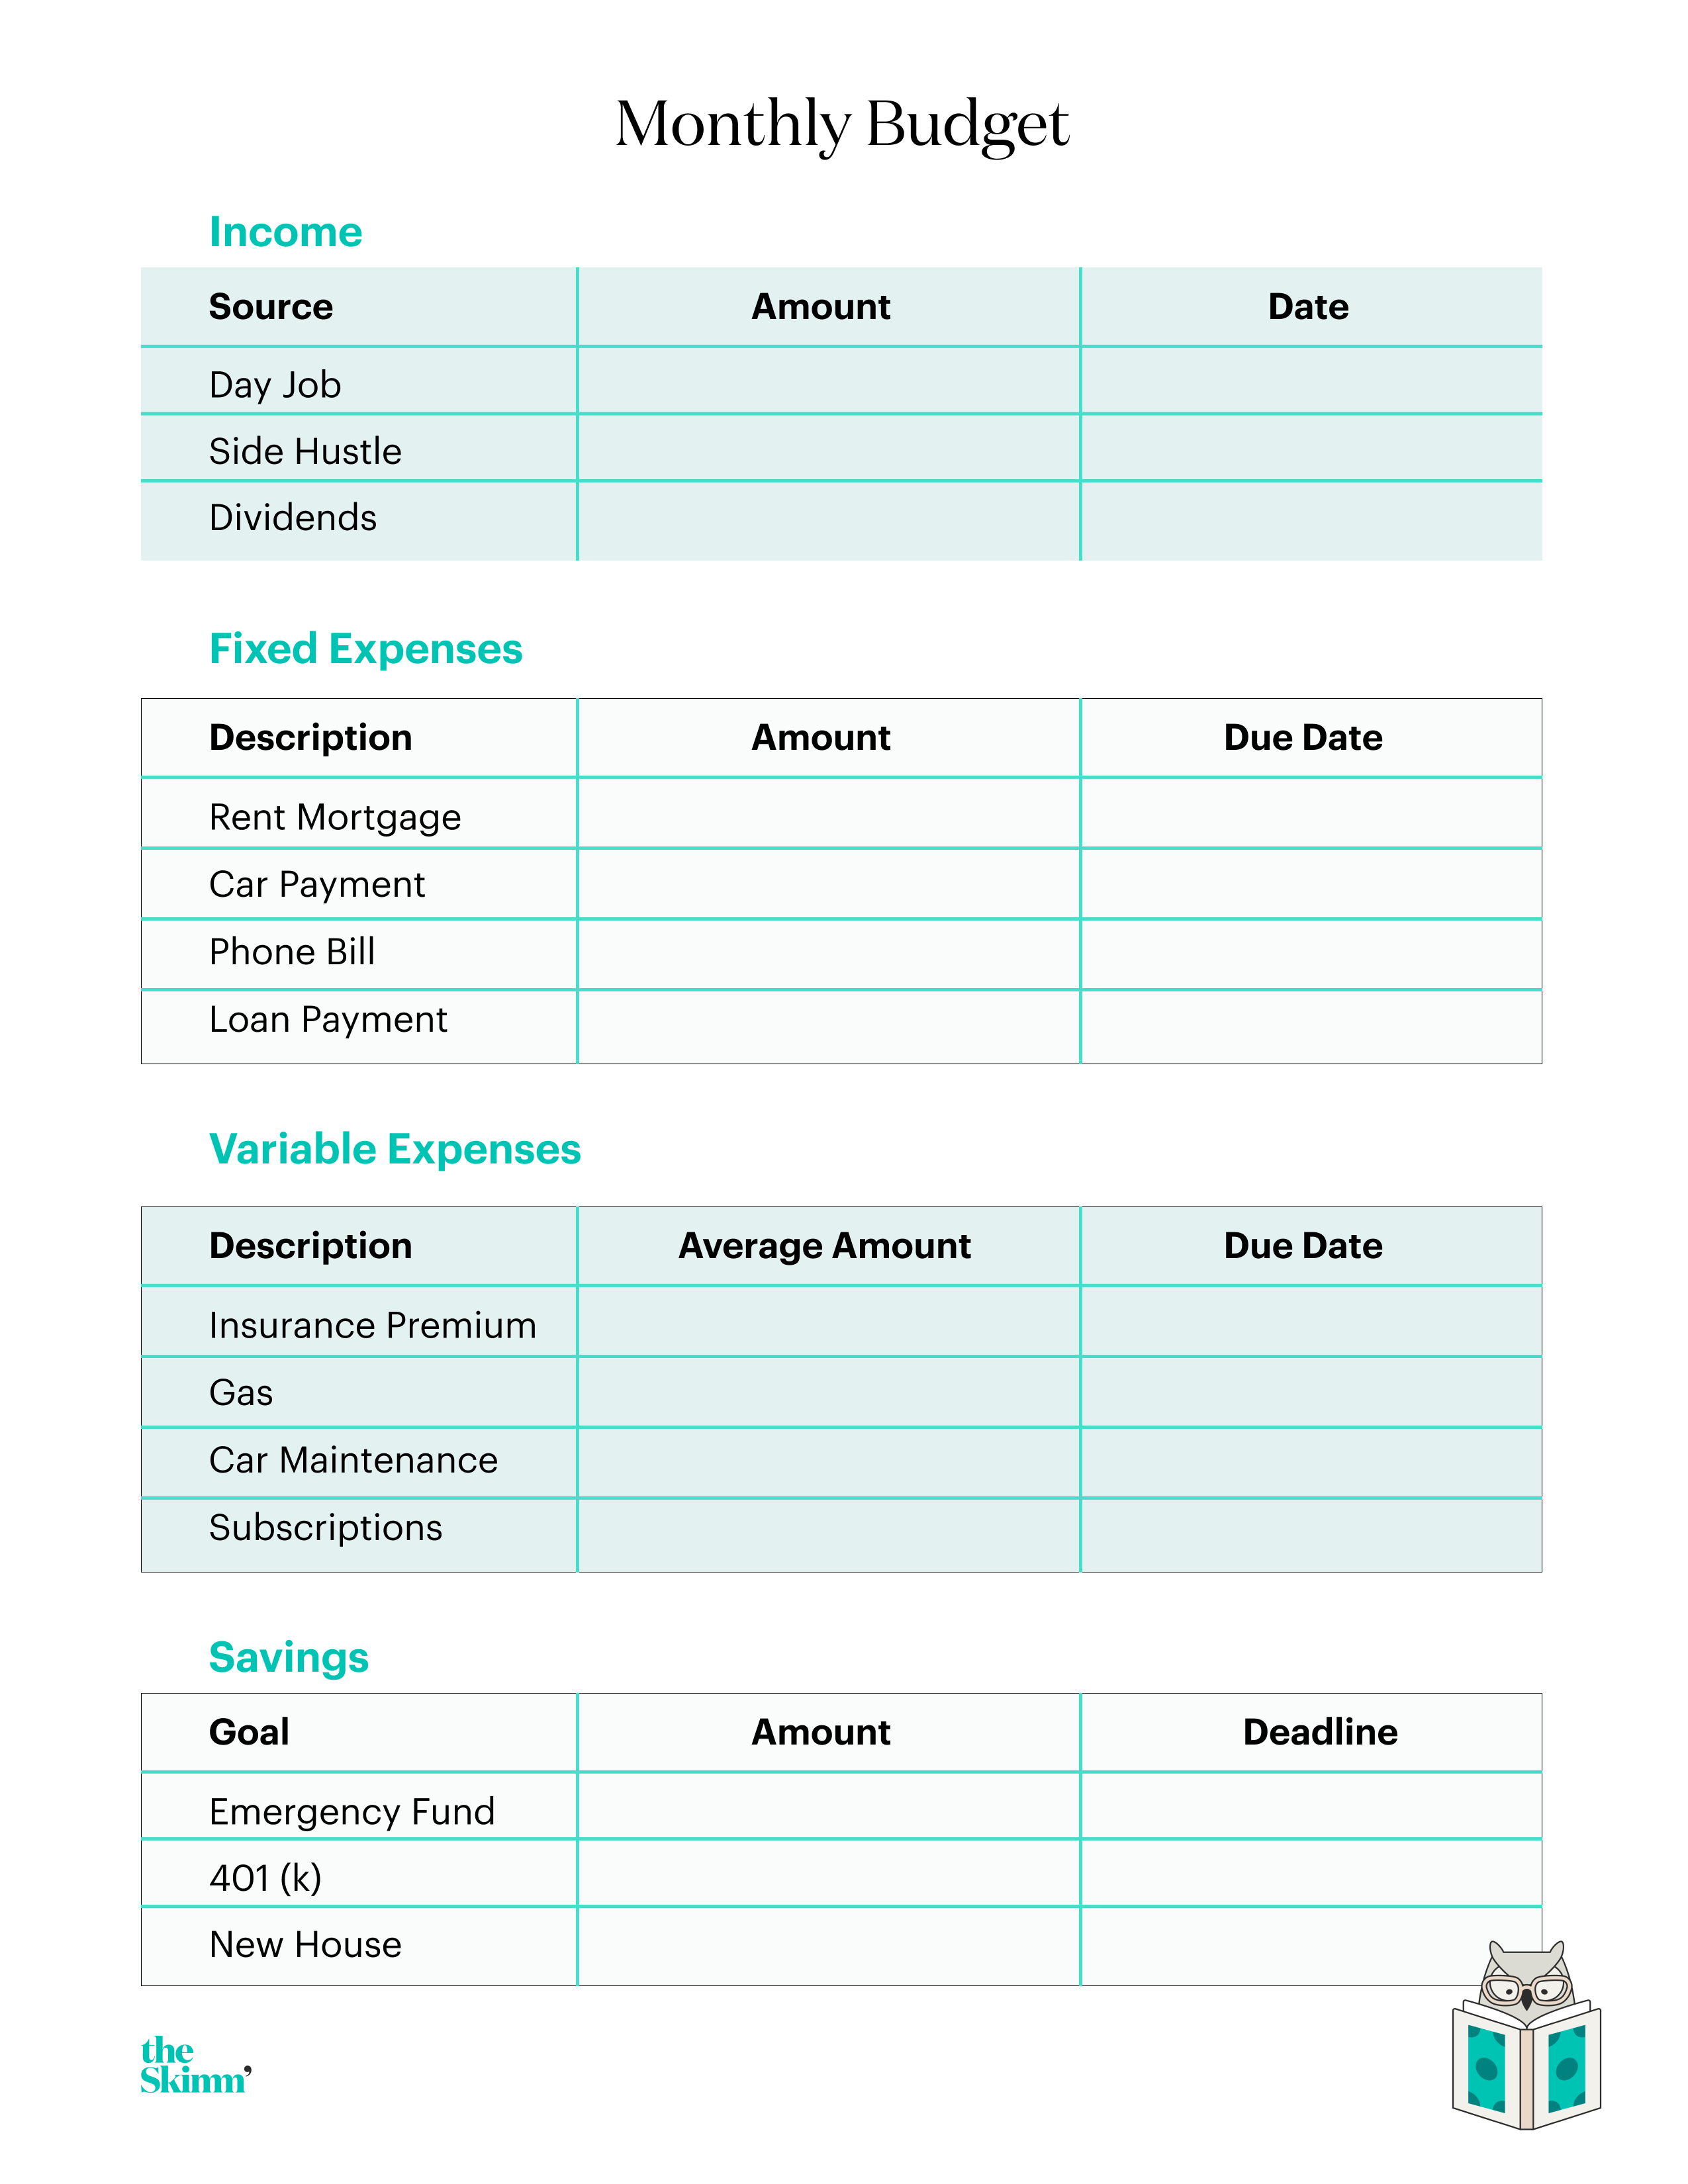
How To Use The Budget Template
Download the template and open it in whatever spreadsheet program you use. The first tab is your income section -- enter your gross monthly income and your net take-home pay. The difference matters because New Jersey state withholding is significant at higher brackets. Fill in the housing tab. This breaks down rent or mortgage, property taxes, homeowners or renters insurance, and maintenance reserves. The maintenance reserve is the part people skip. Set it at 1 percent of your home's value annually, divided by 12. On a $400,000 home, that's about $333 a month. You'll need it when the water heater dies in November and you can't wait until spring. Complete the variable expenses tab. Groceries, utilities, transportation, healthcare, and discretionary spending. Enter your actual averages from the past three months if you have them. If not, use the New Jersey median estimates and plan to revise after 90 days. The template auto-calculates variances so you can see where you're over or under.
Review the projections tab. This shows your projected spending for the next 12 months with cost adjustments baked in. Compare it against your income and flag any months where you're running negative. The template highlights problem months in red so you know where to preemptively cut back. The main pitfall I see is people filling it out once and never touching it again. That defeats the whole purpose. The accuracy comes from revisiting it monthly, not from the initial setup. Budget this way for three months straight and you'll have a much clearer picture of what your actual cost of living in New Jersey is, including where the hidden expenses are hiding.