Buy Now Pay Later Was Supposed To Be Temporary
I remember when Klarna launched in Europe. It felt like a novelty at first. A credit card you didn't need for the checkout page. Fast forward a few years and every retailer from Shopify to small DTC brands had some version of it baked into their stack. The infrastructure around it changed too. Real-time risk scoring, embedded finance APIs, split payments. That is what people mean now when they talk about the future of fintech. Not the buzzword version. The actual version where checkout flows are rewritten and merchants care more about conversion lift than annual percentage rates.
The Future Of Fintech How Okklarna Scinkasosc And Pair Finance Are Revolutionizing The Industry
The actual mechanism here is not a single product. It is a shift in how payment providers are built. Early BNPL was essentially delayed cash. The new generation uses soft credit pulls combined with merchant data, instant approval, and payment orchestration layers that split a single transaction across multiple sources automatically. A customer can pay fifty percent with a debit card, twenty-five percent via a stored credit line, and twenty-five percent over thirty days, all as one action at checkout. This matters because it changes how money moves. Merchants get paid upfront. Lenders get exposure with tighter risk models. Consumers get friction removed from the experience. The technical piece that makes it possible is a payment router that can evaluate multiple funding sources in parallel and commit the one with the lowest cost and highest approval probability.
How The Infrastructure Actually Works
When I first started integrating these systems into checkout flows, most vendors required you to send the full order amount to their API and wait for a yes or no. That worked for simple cases. It breaks when you are dealing with international shipping, high cart values, or customers with thin credit files. The newer approach splits the decision across signals before you even show the payment option to the shopper. The typical flow now looks like this. The merchant sends a payment intent with cart details, device fingerprint, and email hash to the provider. The provider runs a lookalike model trained on its own approval data, checks device risk, evaluates velocity across accounts, and then returns a set of available payment methods with dynamic terms. If the customer has a prior relationship, the provider may pre-authorize a portion and only run a full check at capture time. This cuts average decision latency to under four hundred milliseconds on warm sessions and still leaves room for fraud filters at settlement. One thing beginners miss is the difference between approval rate and profitable approval rate. A system that approves more transactions is not always better. If it is pulling in high-risk profiles just to boost conversion, the chargeback and loss reserve costs eat the margin. The companies that are winning now tune their models to maximize return after loss, not approval volume.
Get the Full Details
What Actually Changed In The Last Three Years
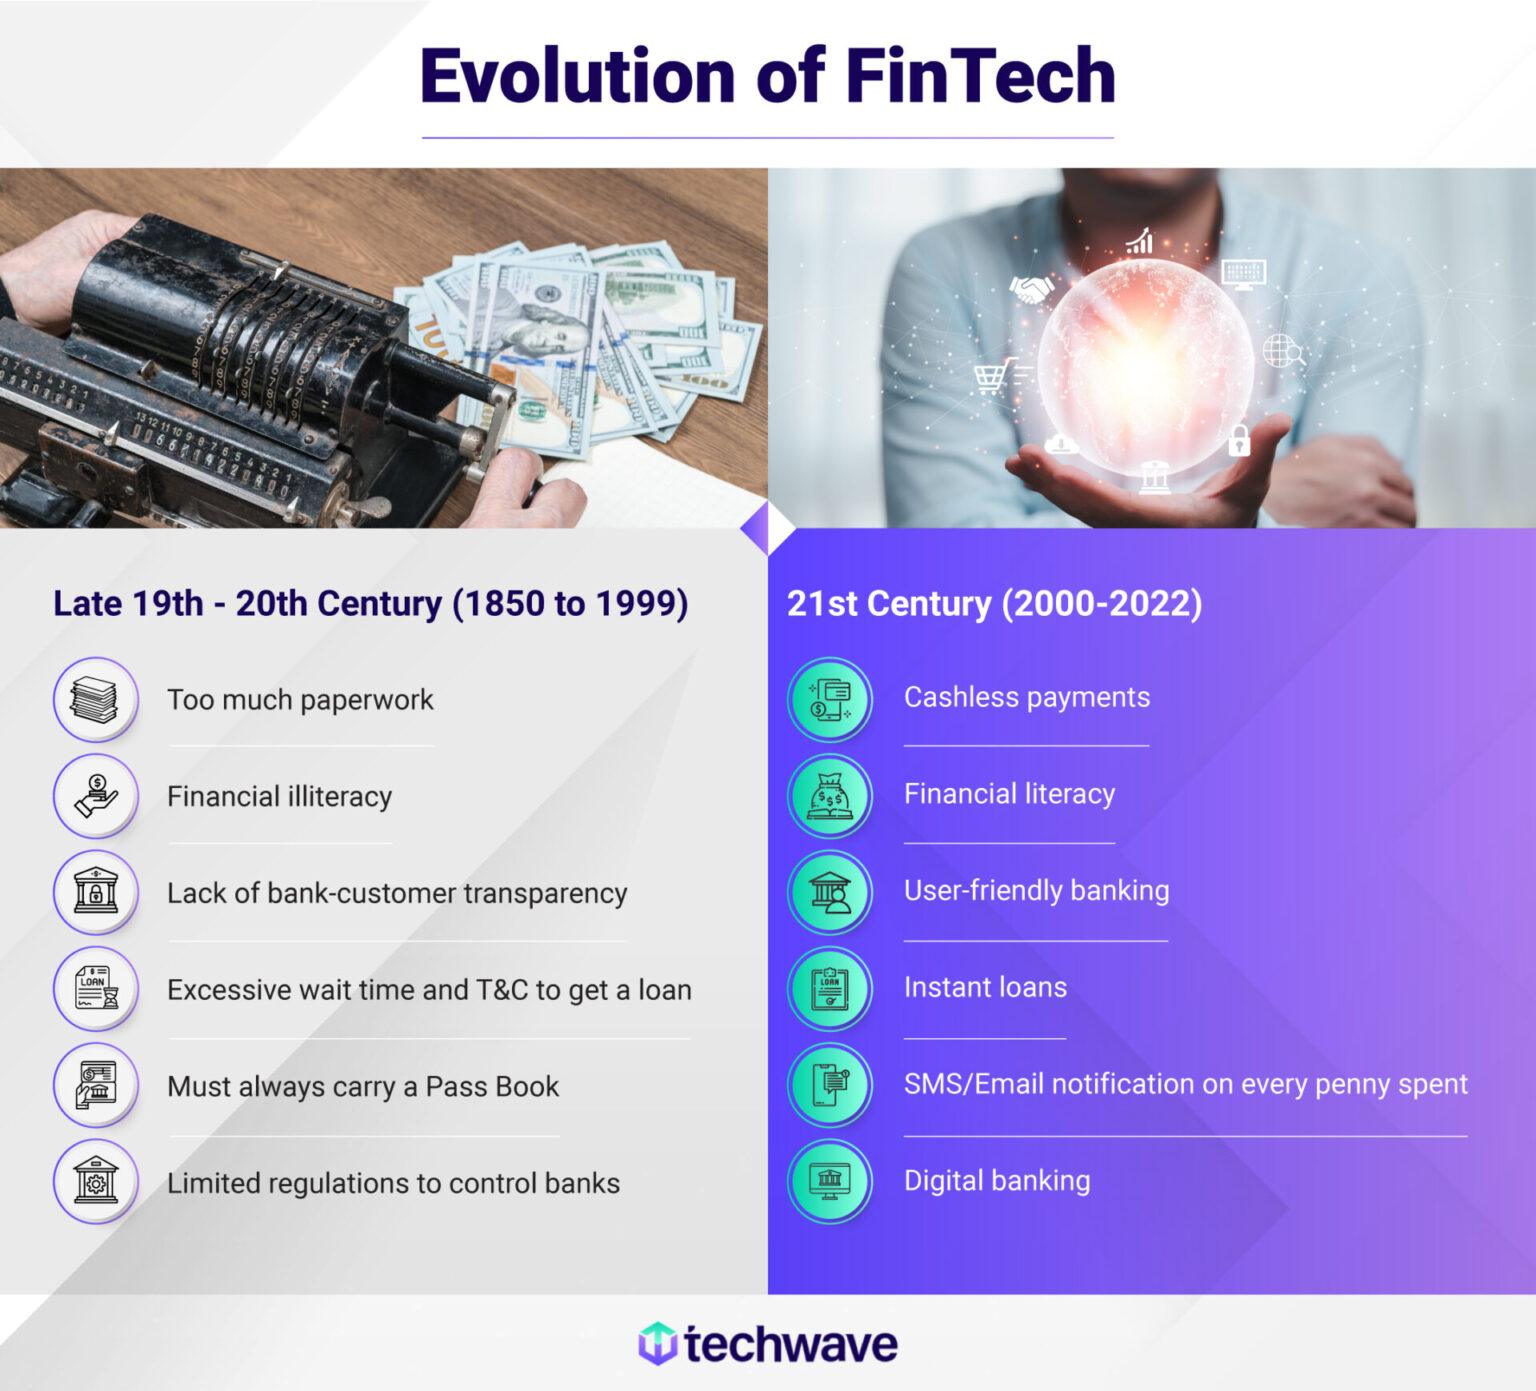
A few years back every fintech was pitching the same story. Embedded lending. Instant checkout financing. Now the category has bifurcated. On one side you have generalist platforms that power payment options across dozens of verticals. On the other you have vertical-specific lenders that underwrite using proprietary merchant data. The generalists are faster to integrate but have thinner risk moats. The vertical players take longer to build but can approve customers that generalists reject because they can see purchase history, return rates, and seasonal demand directly. Pair Finance operates closer to the vertical side of that split. The model is straightforward. Instead of relying purely on traditional credit bureau data, the underwriting layer incorporates transaction history and merchant-specific behavior signals. That lets the system extend credit to customers who would otherwise be declined, which lifts conversion for retailers. The tradeoff is that it only works well with merchants who have enough historical transaction data to feed the model. New stores with fewer than a thousand orders rarely see the same uplift because the system has nothing to compare against yet. On the other end of the spectrum, the major players expanded their scope past simple BNPL. They added virtual cards, subscription management, cross-border settlement, and open banking feeds. The effect is that a single integration can now handle card payments, wallet tokens, bank debits, and credit lines without the merchant managing separate connections. That consolidation is what actually makes these systems feel like the future rather than just another payment tab in the dashboard.
How To Evaluate Whether A Platform Fits Your Operation
Before you sign any contract, ask three questions. First, how does the provider calculate fees. Some advertise zero merchant discount rate and hide costs in interchange fees, subscription tiers, or per-transaction minimums. Second, what is the actual approval rate by customer segment, not the headline number. Third, how does dispute handling work. If a chargeback comes back, does the system auto-fabric evidence from transaction logs or do you spend thirty minutes pulling receipts each time. The setup itself is usually a matter of days if you are on a standard e-commerce platform. You install the SDK, switch to test mode, run through the sandbox transactions, and verify that the payment methods render correctly on mobile and desktop. Then you move to live mode. The part people underestimate is the risk configuration. Each provider ships with defaults tuned for broad use. You should adjust velocity limits, block list thresholds, and allowed geographies based on your actual order patterns. I spent two weeks adjusting these settings on a pilot store and saw chargeback rates drop from about 1.8 percent to under 0.6 percent without any noticeable hit to conversion.
Edge Cases That Will Waste Your Time If You Are Not Prepared
Here is a scenario I ran into that still comes up occasionally. A customer places an order using a BNPL option, the payment goes through, and then the customer opens a dispute claiming unauthorized use. The provider holds the funds while the dispute is investigated. Most platforms resolve this in ten to fourteen business days. The problem is that inventory may have already shipped. I started requiring a brief hold on physical goods when dispute flags appear, which added about a day to fulfillment but prevented the handful of cases where I was left holding both the product and the loss. Another edge case involves mixed carts. When a shopper adds both eligible and ineligible items to the same order, some providers reject the entire transaction rather than splitting the cart internally. The workaround is to ensure your storefront either filters out ineligible SKUs before checkout or routes the payment through a provider that supports partial eligibility. This is not a minor detail. It affects about eight to twelve percent of transactions in mixed carts depending on your product mix.

Where These Systems Still Fall Short
The technology is not magic. Approval rates still drop sharply for first-time customers with no device history. Fraud filters catch legitimate buyers sometimes, especially when IP addresses are shared across household members. Cross-border transactions introduce additional routing complexity and higher fees. And there is the regulatory side. Some jurisdictions are tightening rules around affordability checks and marketing disclosures, which means the product configurations that worked last year may need updates this year. If you are a small merchant with under five hundred orders per month, the cost of integration and the learning curve may outweigh the conversion lift. In those cases, sticking to standard card processing plus a single well-known BNPL provider is usually the cleaner path. The advanced orchestration layers only pay off when you have enough transaction volume to absorb the setup time and enough data to configure the risk parameters properly.
What To Expect Going Forward
The next wave is less about flashy checkout buttons and more about data portability. Open banking and payment account-to-account rails are starting to replace card networks for certain flows. Providers that build on top of those rails will offer lower fees and faster settlement. The risk models will also get better at predicting lifetime value rather than just single-transaction probability. That shift matters because it changes how lenders price credit. Instead of penalizing a customer for one missed payment, the model can weigh the rest of the relationship and adjust terms accordingly. The practical takeaway is to pick a platform that exposes its data cleanly. If you cannot pull approval reasons, fraud scores, and dispute outcomes through an API, you are flying blind. The companies that are going to win in this space are the ones that let merchants audit their own performance and iterate quickly.