Settlement Layers And Why They Matter More Than You Think
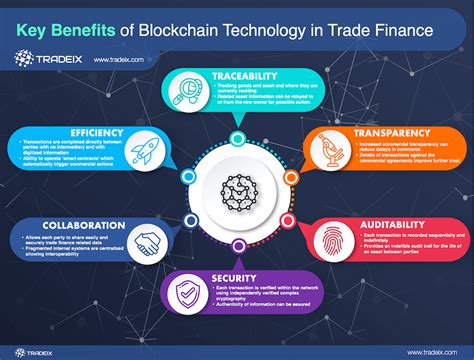
Most people talking about blockchain in finance are still stuck on the first wave — cross-border payments and stablecoin remittances. That stuff works, sure, but it's the lower-hanging fruit and the hype machine has already extracted everything useful from it. The real shift is happening in settlement infrastructure, collateral management, and the way institutions are starting to move legacy financial instruments onto distributed ledgers for actual operational reasons, not PR. I spent about two years working on a project where a mid-tier European bank wanted to replace their overnight repo reconciliation process with a permissioned ledger. The pitch was supposed to cut reconciliation time from end-of-day batch processing down to near-real-time. What actually happened is more interesting than the pitch.The core problem isn't the technology. It's that the technology exposes every single friction point that legacy systems have been quietly absorbing for decades. When you put two institutions on the same ledger, you can't afford to have one side processing trades in T+2 and the other side settling in T+1. The mismatch creates reconciliation gaps that are suddenly visible in real time instead of being buried under overnight batches. We ended up spending more time designing exception handling logic than we did on the smart contract implementation itself. The revolution isn't happening because blockchain makes everything faster. It's happening because blockchain forces a level of operational transparency that the old system could never sustain at scale. Think about what tokenized securities actually require under the hood: every participant needs standardized data formats, synchronized timestamps, shared definitions of what "settled" means, and automated compliance checks. Building that kind of alignment is painful. But once you have it, the downstream benefits compound in ways that aren't obvious from the outside. The major projects right now that aren't getting nearly enough attention are in three areas: tokenized money market funds, wholesale central bank digital currency pilots, and programmable compliance frameworks for equities.
Programmable compliance is the area I find most interesting and most neglected in public discourse. Instead of writing post-trade compliance checks, you can embed them into the token itself. A security can carry transfer restrictions, investor accreditation flags, and jurisdictional holding limits as machine-readable metadata. When someone tries to transfer it, the ledger validates the rules before accepting the transaction. This is actually how many institutional platforms are starting to think about it, and it's dramatically reducing the manual compliance overhead that used to dominate back-office workflows for cross-border securities trading. The downsides are real and worth stating plainly. Blockchain doesn't solve operational risk. If your smart contract has a bug, you lose money. Period. The Immutable Ledger narrative is partly marketing and partly truth — transactions can't be altered after confirmation, but that also means errors are permanent. We had one instance where a misconfigured token transfer function moved collateral to the wrong address, and there was no reversal mechanism built into the protocol. The team had to negotiate a manual correction with the counterparty, which took three weeks and required legal intervention. Nothing about this is futuristic. It's just a different category of operational risk. Another limitation that gets glossed over: performance degrades non-linearly as you add participants to a permissioned network. This isn't a theoretical problem. We watched a pilot network slow from sub-second finality to twelve-second confirmations when we added the fifteenth participant. The consensus mechanism had to process more validation paths, and the network topology wasn't designed for that scale. The fix was partitioning the network into sub-channels, but that introduced new complexity around cross-channel settlement that we hadn't budgeted for.
What Actually Works Right Now
If you're evaluating whether to adopt blockchain infrastructure for a financial use case, start by identifying the specific friction that requires multi-party trust. Blockchain is expensive compared to a centralized database. You should only use it when you have a genuine need for shared state that multiple independent parties need to agree on without a single administrator. If you can solve the problem with API-based integration between two systems, do that instead. It will be faster, cheaper, and easier to maintain.
Get the Full Details
The hard truth is that blockchain in finance isn't a technology problem anymore. It's an organizational and regulatory problem. The technology works. The question is whether the institutions involved can align their processes, agree on standards, and navigate a regulatory environment that hasn't caught up to the new mechanics. Most projects that succeed do so because they have patient capital and executives willing to absorb the initial inefficiency. Most projects that fail do so because the business case looked good on paper but collapsed under the weight of coordination costs.