The Historical Franc Zone and What's Left
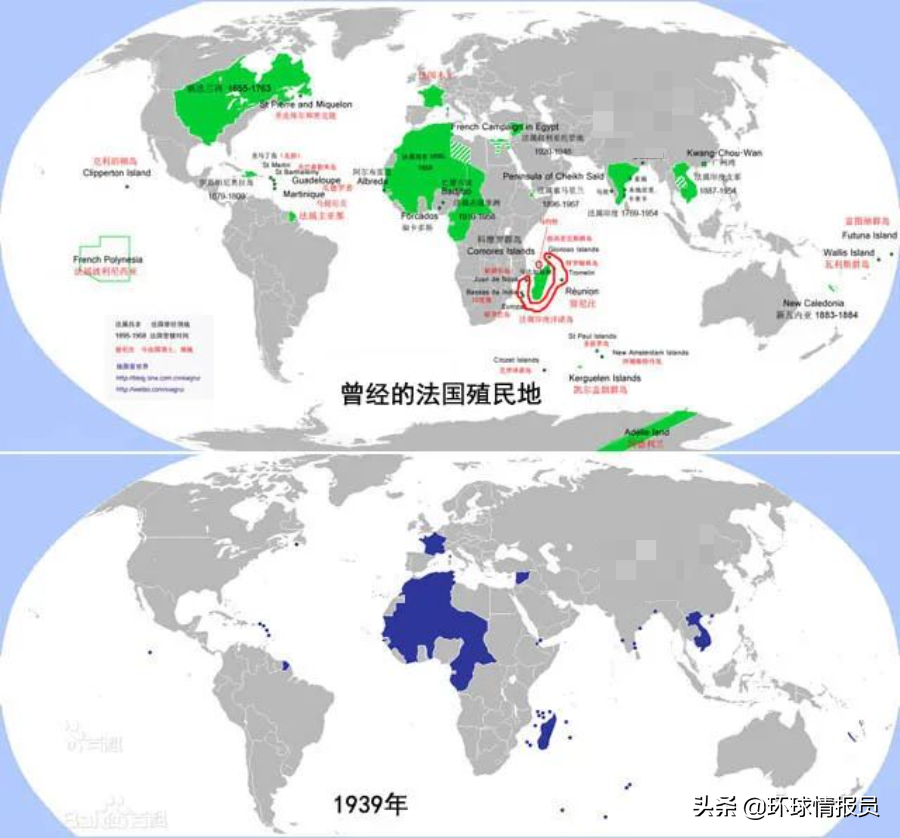
When people ask about franc influence, they're usually thinking of old French colonial money. The reality is messier than that. The CFA franc still moves through large parts of West and Central Africa, but the picture has shifted significantly since France abandoned the monetary system in 2019. Three monetary zones still operate under the name "franc" in some form: The CFA franc (West African CFA) is used by eight countries: Benin, Burkina Faso, Côte d'Ivoire, Guinea-Bissau, Mali, Niger, Senegal, and Togo. These nations share the Central African Development Bank and peg their currency to the euro. One of these countries, Mali, left the zone in 2022 along with Burkina Faso and Niger, which announced their exit from ECOWAS entirely before being suspended. Niger then introduced the eco as a replacement, though the transition remains incomplete.
The CFA franc (Central African) is used by six countries: Cameroon, Central African Republic, Chad, Republic of Congo, Equatorial Guinea, and Gabon. These share the Bank of Central African States and the same peg arrangement. Comorian franc operates independently in the Comoros. It's not pegged to the euro in the same way and floats separately. And of course Switzerland and Belgium still use their own francs. The Swiss franc (CHF) is one of the most traded currencies globally. The Belgian franc was replaced by the euro in 2002, but coins can still be exchanged at the National Bank of Belgium indefinitely.
How the CFA Franc System Actually Works
Under the original system established in 1945, member countries had to deposit 50 percent of their foreign exchange reserves into the French Treasury. That changed. The 2019 reform abolished that requirement for the West African zone and renamed it the "euro franc." Countries still maintain a minimum reserve of 35 percent with the French Treasury, but the arrangement is now structured differently and involves more transparency about the exact mechanics. The euro peg means these central banks don't set independent monetary policy. When the European Central Bank adjusts interest rates, those changes cascade directly into the CFA zone. This eliminates currency risk for trade with the euro area, which matters because France and other eurozone countries are major trading partners. But it also means these governments can't devalue their currency during a downturn, even when economic theory suggests it would help. I worked with a contractor in Côte d'Ivoire who tried to hedge a payment schedule against the CFA franc. The hedging instruments available were thin. Liquidity dries up fast outside major francophone business centers. The workaround was converting to euros first, then using a local correspondent bank in Abidjan to convert at near-market rates. It added roughly three business days to settlement but saved about 1.2 percent compared to the hedging options available locally.
Get the Full Details

Swiss and Belgian Franc Considerations
The Swiss franc carries different implications. Switzerland has never joined the EU or the eurozone. The franc's strength during European crises has made it a traditional safe-haven currency. If you're dealing with Swiss francs for cross-border transactions, the main friction point is that many international payment processors treat CHF like any other currency, which means less favorable conversion spreads compared to EUR or USD. Using a specialist forex provider instead of a standard bank can cut the spread by roughly 40 to 60 basis points. The Belgian franc is effectively historical at this point. Physical coins and banknotes can still be exchanged at the National Bank of Belgium, but only through specific channels. If someone still holds pre-2002 Belgian franc documents or coins, the exchange process requires mailing them to the bank or visiting their headquarters in Brussels. There's no online conversion service for this.
Common Pitfalls
Most people confuse the two CFA franc zones as a single currency when they're technically separate, each issued by different central banks. The peg to the euro is identical and the exchange rate is always 1 EUR = 655.957 CFA francs, but they're different monetary issuances. This distinction matters when you're doing accounting across both zones, because transfers between the West African and Central African zones are treated as cross-currency movements rather than domestic transfers. Another issue is that pricing on invoices sometimes shows "CFA francs" without specifying which zone. In practice the exchange rate is identical, but compliance systems and some banking software flag mismatches. Always label it FCFA for West African CFA or XAF for Central African CFA. The ISO 4217 codes are FCFA for the West African version and XAF for the Central African version, though both commonly use the symbol CF in informal contexts. The CFA franc system draws consistent criticism from economists on both sides. Proponents argue it provides stability and keeps inflation low, typically under 3 percent annually across the zone. Critics note that maintaining the peg requires surrendering a key monetary policy tool and that the reserve requirement, even after reform, represents an ongoing financial dependency. Neither side has a clear resolution path forward, and political dynamics around independence movements in parts of West Africa make the future uncertain.
For practical purposes, if you're conducting business in these regions, the main considerations are choosing the right conversion path for CFA francs, understanding which zone you're operating in, and planning for the settlement delays that come with thinner liquidity. The Swiss franc requires less special handling beyond recognizing its status as a strong currency that may appreciate during regional stress. And anything involving Belgian francs should be treated as a legacy issue rather than an active financial matter.