Why Most People Give Up on Form 990 Research After Five Minutes
Form 990 filings are publicly available, yes. The IRS makes them easy to find. Making sense of them is a different story. I spent three years pulling these for grant due diligence work, and I still lose time on the same mistakes every quarter. The standard route is ProPublica's nonprofit explorer or the IRS Tax Exempt Organization Search tool. Both work for basic lookups. Neither will save you when a nonprofit has filed amendments, operates multiple subsidiaries, or reports revenue through complex partnerships. I learned this the hard way during a site visit to a mid-sized arts org that showed $2.4 million in revenue on paper but reported nearly zero program expense ratio. The numbers were technically accurate. The reality was hidden in Schedule L related-party transactions and a footnote on Page 23 about a jointly-funded initiative with a for-profit partner.
The Form 990 Search Survival Guide How To Decode Nonprofit Financials Like A Pro
Start with the right filing. Not every organization files the same version. Large nonprofits file the full 990. Mid-sized ones file the 990-EZ. Small ones file the 990-N postcard. The 990-N contains almost nothing useful for financial analysis. If you are researching a potential grant recipient, partnership, or donor, verify the filing type before you invest time in it. The Part I statement of revenue is where most people stop and declare victory. Do not stop there. Line 1 through Line 22 contain legitimate income, but lines 18 through 20 specifically list fundraising gross receipts. A nonprofit reporting $800,000 in total revenue with $620,000 in fundraising income is not a high-impact program operation. It is a fundraiser with a program attached. This distinction matters more than people admit when writing grant reviews or donation decisions. Schedule B is mandatory disclosure for organizations receiving contributions above certain thresholds. It lists major donors. For public charities, the threshold is $5,000 or 2 percent of total revenue, whichever is lower. Private foundations have a higher contribution threshold but different reporting requirements. Reviewing Schedule B tells you whether an organization depends on a small number of donors, which is a sustainability risk that never appears on the face of the 990.
Here is a detail most guides skip: the difference between restricted and unrestricted net assets matters enormously. Page 1, line 15 shows total net assets or fund balances. But you need Schedule D, which breaks down those assets by purpose. A charity showing $3 million in net assets might actually have $2.1 million permanently restricted for an endowment or a building project. Their operational flexibility is a fraction of what the headline number suggests. I once passed on a $50,000 grant opportunity because Schedule D revealed the organization had less than $40,000 in truly unrestricted cash despite reporting $1.8 million in total net assets. The CFO confirmed this at a follow-up call and admitted they were three months from a cash shortfall. Schedule M covers non-cash contributions. This is where in-kind donations, donated services, and property transfers get reported. Some organizations inflate their apparent financial capacity by recording donated space or volunteer hours at aggressive valuation assumptions. The IRS does not require appraisals for most in-kind contributions under $5,000 per item. A well-meaning but poorly governed board can easily overstate these figures without malicious intent. Compensation discussion is in Part VII. Look beyond the top-five salaries that everyone checks. Form 990 requires disclosure of current and former officers, directors, trustees, key employees, and highest-paid employees. You will see columns for reportable compensation from the organization, from related organizations, and from other tax-exempt or governmental organizations. When the same person appears across multiple lines with different pay sources, that usually indicates a board member or staff person receiving supplemental income from affiliated entities. This pattern warrants a closer look because it can mask conflicts of interest or double-dipping structures.
Get the Full Details
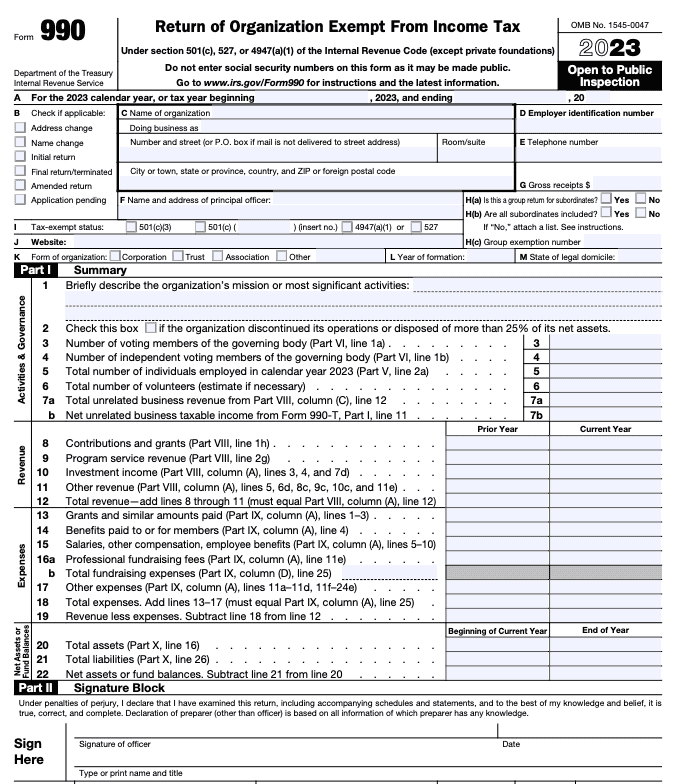
Part VIII, the statement of functional expenses, is the most critical schedule for understanding where money actually goes. The first four columns should add up to total expenses. If they do not, check the footnotes. Discrepancies here are common on amended returns. The six-line breakdown—program services, management and general, fundraising—gives you the expense ratio you need. But the real signal is in the detail. A program service line of $4.2 million could be legitimate direct costs, or it could include significant administrative overhead reclassified to look better. Check the notes. Organizations sometimes describe in Schedule 1 or Page 2 footnotes how they allocate shared costs between functions. A counter-intuitive point about the 990-EZ form. It is shorter. It reports fewer line items. But it includes the same core financial data in condensed format. Many researchers skip the 990-EZ entirely and assume the organization is financially opaque. That is wrong. The 990-EZ still reports total revenue, total expenses, and net assets. For smaller nonprofits under $200,000 in revenue and $500,000 in assets, the EZ version is all that exists. Do not dismiss it. Cross-reference it with the organization's website annual report or audit if available, because the gap between the two documents often reveals formatting choices or one-time adjustments. The IRS database has a bottleneck that frustrates everyone. Filing dates are not always accurate. An organization might show a 2023 990 as filed in March 2024 when it was actually submitted in October 2024 with a late filing penalty. The electronic IRS system does not always capture the actual receipt date correctly. If you need precise timing—say, for a fiscal year comparison—you should pull the PDF directly from the organization's website or request it through FOIA. This takes longer but gives you the actual submission timestamp.
Another practical problem: some organizations amend their returns. The IRS and ProPublica will show the amended version, but the original filing is still accessible if you know where to look. A nonprofit might amend to correct a misclassified expense or to update compensation data after an audit finding. The amendment itself, filed as a separate document, will reference the original and explain the change. If you are doing serious financial analysis, request both versions. The difference between them is often more informative than either document alone. I recently worked through a case where a regional food bank reported a 4 percent program expense ratio decline over two years. The initial read was concerning. The amended Schedule M showed they had reclassified $340,000 in donated perishable goods from program service expenses to fundraising expenses after an external auditor flagged the classification. The adjustment was technically correct but artificially depressed the program ratio. Without the amendment document, the trend line looked worse than it actually was. This kind of reclassification happens more often than you would expect, especially around fiscal year changes and staffing transitions. Free tools exist but they have real limits. ProPublica's Nonprofit Explorer is fast and covers most filings. Guidestar, now part of Candid, offers deeper access but requires a subscription for complete documents. The IRS EO Select Check tool only gives you basic identification data, not financials. For a thorough review, budget 45 to 90 minutes per organization depending on size and filing complexity. A simple 990-EZ review takes about 15 minutes. A full 990 with seven schedules and extensive footnotes takes closer to an hour if you are reading everything carefully.
The main limitation of all public Form 990 data is that it is self-reported and self-audited in most cases. The IRS does not review the vast majority of filed returns in detail. Errors are common. Omissions happen. Intentional misclassification is rare but not unknown, particularly around unrelated business income and program service expense calculations. If an organization's financial story does not add up after reviewing the schedules and footnotes, the next step is usually a direct conversation with their finance staff or a request for their audited financial statements, which carry a higher standard of verification. The most useful habit I developed was checking Page 4, Part III, the checklist of governing documents. It tells you whether the organization has a conflict of interest policy, whistleblower policy, and document retention policy. The answers are yes or no. A nonprofit answering no to all three is not necessarily fraudulent. But it is operating with minimal structural oversight, and that tends to show up later in the financial data as unexplained expense growth or donor concentration risk. If you need to pull filings in bulk for multiple organizations, the IRS provides bulk download files of all submitted 990s. These are available as raw XML and PDF packages. The files are large and the naming conventions are opaque, but they are free and comprehensive. I use a simple Python script to parse the XML headers and match organization names to EINs before downloading the full PDFs. This approach cuts research time significantly when you are evaluating a portfolio of potential grantees or partners.

Bottom line: the Form 990 is readable if you stop treating it like a single document and start treating it like a bundle of related documents with cross-references. The schedules are where the truth lives. The summary pages are the marketing material. Read both. Question the gaps between them. And always check for amendments before drawing final conclusions.