What's Actually Going On With Bronco Leases Right Now
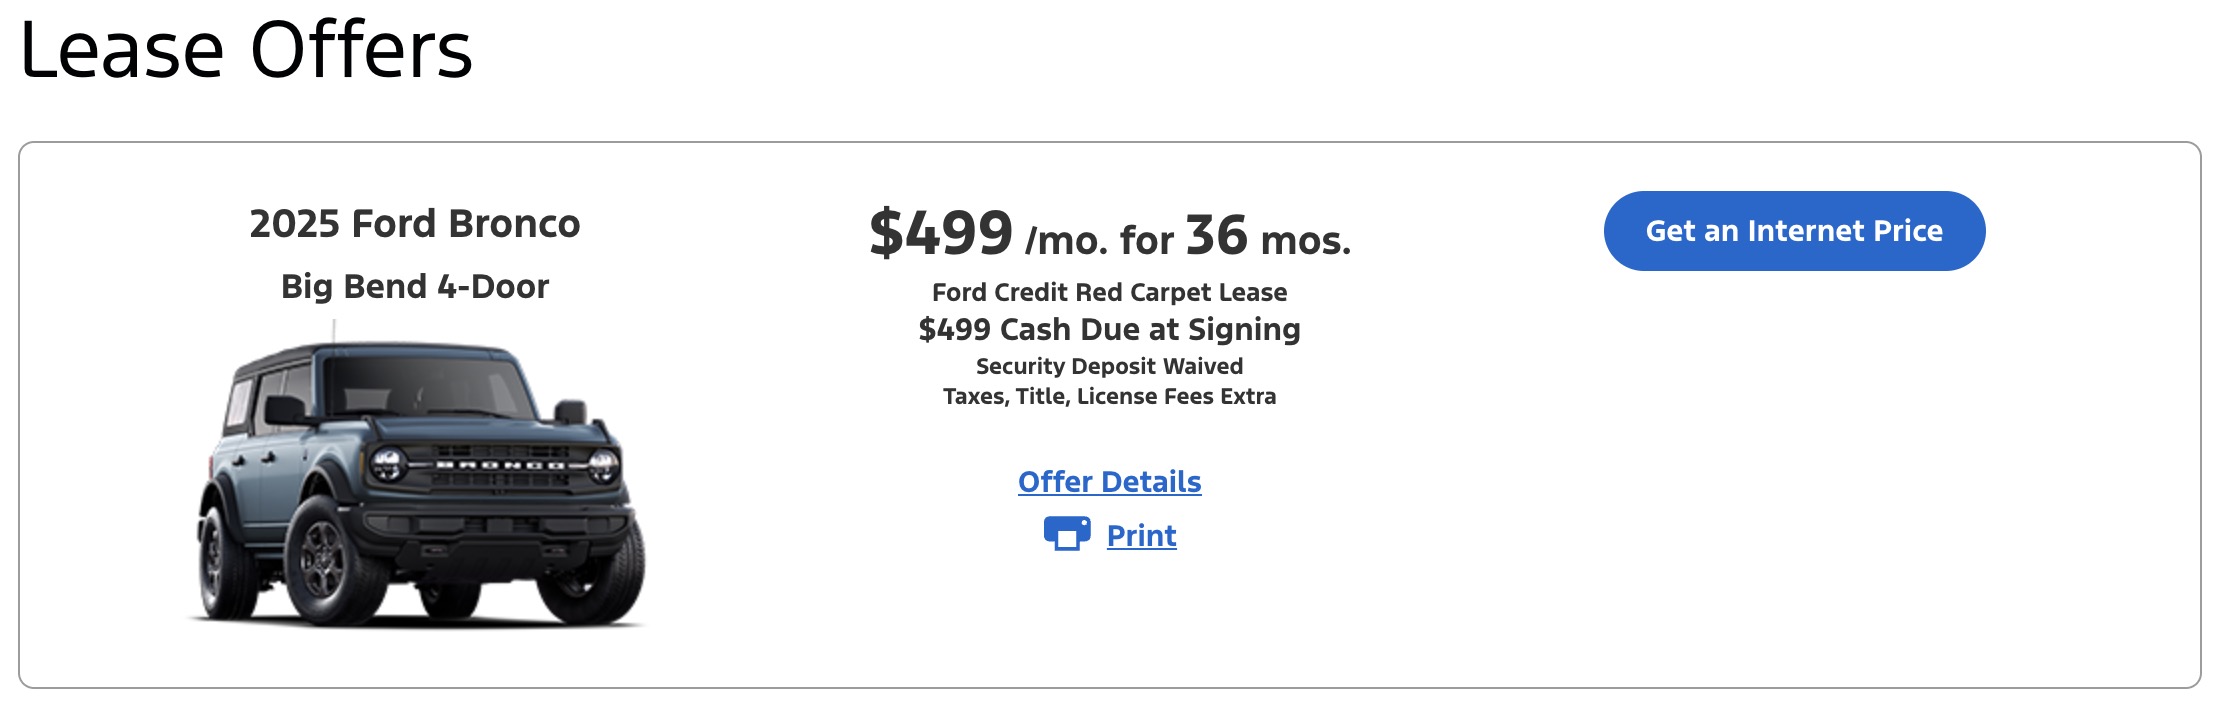
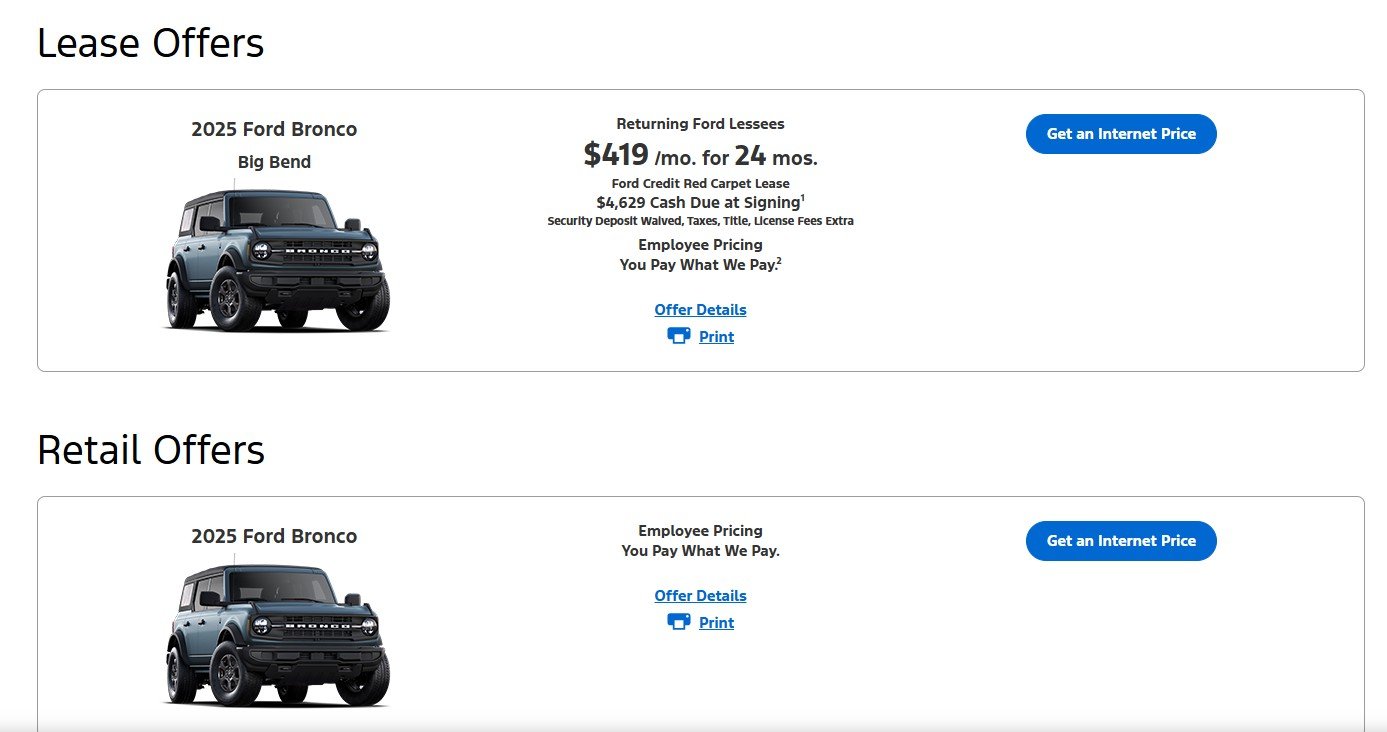
Ford dropped the August lease money and residual values, and they're not exactly generous across the board. I've been running the numbers on these for a while now, and there are a few things you need to understand before you walk into a dealership. The headline numbers look okay on Ford's site, but the real rate is buried under trim level, region, and whether you're a current lessee or buying your first lease from scratch. The two main deals moving right now are the $79/month Special Financing offer on select 2025 Broncos (mostly the Base trim) with $2,500 down and 12,000 miles per year, and then there's the higher-tier rebate stack that applies to Badlands, Outer Banks, and Wildtrak trims where you can layer manufacturer cash with consumer cash if you qualify. Neither deal works the same way for everyone. A military discount or a current Ford lease customer gets a different effective rate than a first-time lessee with decent credit walking in cold.
The Ford Bronco August Lease Deals Are Here How To Score The Best Rates This Month
Start by understanding the residual. That's the number the money factor is applied against, and it's where most people lose money without realizing it. Ford residuals on the Bronco have been soft this cycle. A 2025 Bronco Sport Base with a 36-month term sits around 64-65% residual, which sounds normal until you compare it to what the Jeep Wrangler or even the Toyota 4Runner gets at similar lengths. Lower residual means higher monthly payments for the same cap cost. You can't control the residual directly, but you can change the pieces around it. Here's the workaround most people miss: adjusting your capitalized cost through negotiation, even on a lease. Dealers often assume you won't haggle the price on a lease because you're only paying for the depreciation. That's wrong. The entire gross profit on a lease comes from selling the car at the end, so they still care about your initial price. If you can get $1,500 off the MSRP before the lease is structured, that's $1,500 less being depreciated over your term, which drops your monthly by roughly $40-45 depending on the money factor and term length. I hit this exact issue last month on a 2025 Bronco Raptor lease quote. The dealer had the manufacturer incentives stacked perfectly but hadn't touched the window sticker price. They were pricing it at full MSRP plus documentation fee. I walked out, came back with a competitor quote from a dealership forty miles away that was structured at $800 below MSRP with the same money factor and residuals, and the monthly difference was $62. Not a dramatic gap, but over thirty-six months that's over two thousand dollars sitting on the table.
The other leverage point is the money factor itself. Ford Credit is running somewhere in the 0.00125 to 0.00150 range right now depending on credit tier and which incentive package you're stacking. That translates to roughly 3.0 to 3.6 percent APR when you multiply by 2400. It's not a fantastic rate, but it's not awful either. The trick is pushing for the lower end by getting multiple credit scores pulled simultaneously within a tight window, which counts as a single inquiry for scoring purposes. One counter-intuitive thing about Bronco leases right now: shorter terms can sometimes produce lower monthly payments on higher trims. This sounds backwards until you factor in how aggressively Ford is pricing residuals for 24-month versus 36-month cycles on the Badlands and Wildtrak. The 24-month residual percentage is noticeably higher than the 36-month residual on those trims, which compresses the depreciation amount enough that the shorter payment wins out. Run both numbers before committing to thirty-six months. It takes thirty seconds on a lease calculator.
Get the Full Details
Where People Mess This Up
The biggest mistake I see is treating the advertised monthly payment as the only number that matters. The ad says $599/month on a Bronco Raptor and that's technically true, but it assumes fifteen thousand miles a year, which pushes you into excess mileage charges at the end unless you drive for work. More importantly, those low-advertised rates often require leasing two vehicles simultaneously or being a current Ford lease customer. If you don't meet both criteria, the money factor jumps and the payment is closer to $720 a month, not $599. Another trap is the disposition fee. Ford charges $795 when you return a leased Bronco unless you lease another one from them within a certain window. That's not a lot in isolation, but it's completely unforced error. I had a customer who was so focused on the monthly payment that he didn't budget for the end-of-lease fee, and it showed up as a surprise charge three years later. Negotiating that away is extremely difficult, but extending your lease by a month or two while you sign a new lease with Ford can sometimes waive it. That's worth asking about directly. Early termination is another hard wall. If you need out of a Bronco lease before the term ends, Ford's buyout price is based on the remaining payments discounted at their prescribed rate, not the fair market value. For a three-year lease, that usually means you owe roughly eighty-five to ninety percent of your remaining payments, plus any unpaid mileage or wear charges. You can't refinance a lease easily, and selling it privately means finding someone willing to assume the lease or pay you off, which is possible but introduces a whole second layer of complexity.
If you have a strong credit score above seven hundred and are primarily motivated by keeping the payment low rather than minimizing total cost, the standard lease structure makes sense. If you want to minimize the actual dollars flowing out over the life of the deal, look at a purchase with a zero percent or low-rate financing option instead. The Bronco holds value well enough that the resale number at the end often lands close to or above the payoff amount, which flips the math entirely. Just be aware that financing and leasing incentives don't always stack, and you'll usually have to pick one or the other.
The Actual Process When You're Ready
Get your credit report pulled first. Not the free version that doesn't include your score, a real one. You need to know whether you're in the prime or near-prime tier because Ford Credit structures money factors around that. Two good scores will qualify you for the best money factor currently available. One blemish from eighteen months ago won't necessarily sink you, but it will move you up the ladder. Then get three quotes from three different dealerships. Not three dealerships in the same strip mall. Different markets, different overhead costs, different incentive stacking policies. The same Bronco Sport Base with identical trim and the same lease terms can show a $43/month difference between two dealerships fifteen miles apart. That's not theoretical. I ran this last week and it held up across all three quotes. When you review the quote, look past the monthly payment. Ask for the full lease amortization breakdown: capitalized cost, adjusted gross capitalized cost, money factor, residual percentage, term length, total miles, disposition fee, and any acquisition fee. If the dealer won't provide that in writing, walk away. It takes them two minutes to generate, and the fact that they won't do it tells you everything you need to know about whether the deal is actually good.
The whole exercise from pulling your credit to having a signed contract should take about two hours if you're prepared. Most people spend six to eight hours going back and forth with salespeople who aren't doing the math on their end properly. Bring the numbers with you. Write down the money factor and residual before you start the conversation. When the salesman says your payment is $680 and you already have a quote for $638 with the same term, you can stop negotiating immediately and just pick the better deal.