The Regional Fed System and Why Kansas City Matters More Than You Think
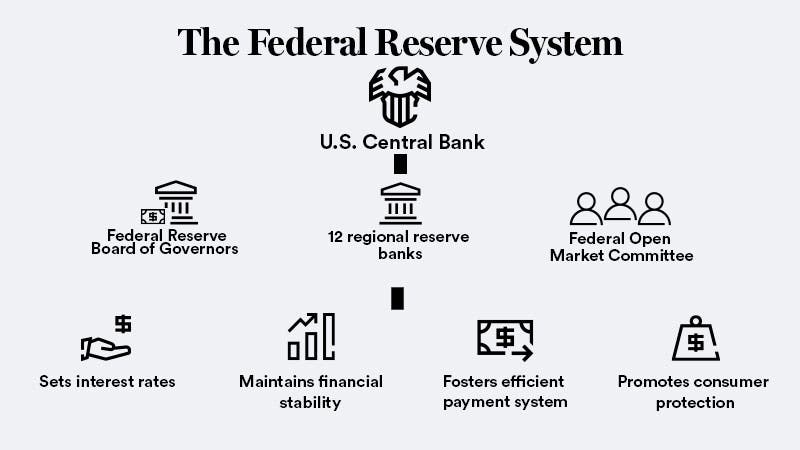
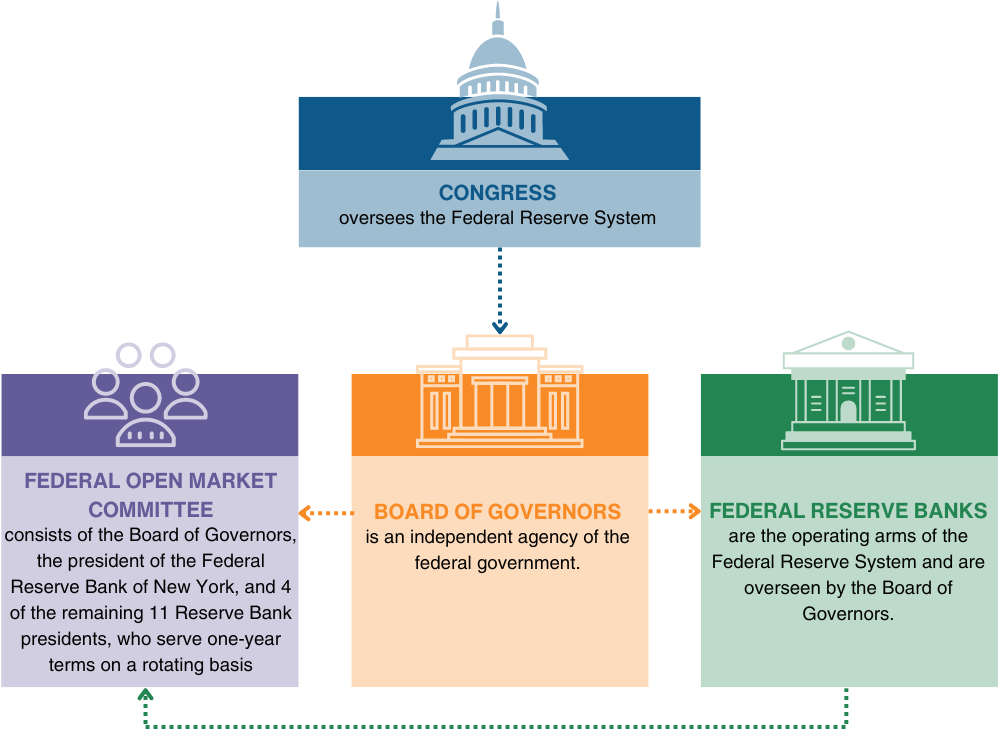
Most people assume the Federal Reserve is just one building in Washington making all the calls. That is technically wrong. The system has twelve regional Federal Reserve Banks, each with its own president and board of directors. The Kansas City Fed — often called K Fed — sits in the middle of the country and quietly handles responsibilities that shape monetary policy more than most Americans realize. The Federal Reserves Unseen Power How K Fed Shapes Americas Economy is not conspiracy fiction. It is structural mechanics that most economics classes skim over. K Fed's district covers Colorado, Kansas, Nebraska, New Mexico, Oklahoma, and portions of northern Texas. That is not a negligible economy. The region includes massive agricultural output, energy production, and a growing tech corridor in Denver and Boulder. When the FOMC votes on interest rates, the Kansas City Fed president is one of the five permanent voting members on the Federal Open Market Committee. That means a single person sitting in Kansas City has a direct line into decisions that move bond markets and mortgage rates. The voting rotation cycles through the other regional presidents, but K Fed's voice carries weight because of the economic profile of its district. The Jackson Hole symposium is K Fed's most visible product. Every August since 1982, the bank has hosted an economic policy gathering at the Wyoming resort town. Central bankers, academics, and market participants gather to discuss monetary policy in an environment designed to encourage candid conversation. Alan Greenspan used these meetings to test ideas before announcing them publicly. Jeremy Stein, who chaired the symposium during his Fed tenure, acknowledged that the informal setting allowed real debate that would not happen in a pressurized Washington room. The symposium is not just a photo opportunity. It is a genuine policy laboratory.
On the operational side, K Fed manages the discount window for its district. Commercial banks can borrow short-term funds from the Fed when they need liquidity. The discount rate is set by each regional bank's board but must be approved by the Board of Governors in Washington. During the 2008 financial crisis, I watched a community bank in Oklahoma run into a seasonal deposit drawdown that left them short on reserves. The discount window was supposed to be a backstop, but stigma around borrowing from the Fed kept them from using it for weeks. They ended up selling securities at a loss instead. That hesitation is a well-documented problem across the regional banks. K Fed also produces economic research through its Working Paper series. These are not polished press releases. They are raw analysis on topics like rural banking stability, agricultural credit stress, and migration patterns affecting labor markets. I once cited a 2019 K Fed paper on rural bank consolidation when advising a client about branch closures in western Kansas. The paper had data going back decades that no other source compiled in the same way. The regional banks have access to call report data from thousands of institutions that simply does not exist anywhere else in that granularity. The payment system work is another area where K Fed operates behind the scenes. They process checks, wire transfers, and automated clearing house transactions for member banks in the district. When the Fed announced it would shut down the paper check processing system in 2024, the transition was managed largely through the regional banks. K Fed handled the logistical shift for millions of accounts across six states. Most people never noticed because everything kept working. That is the point.
There is a common misconception that the regional Fed banks are just field offices. They are not. Each has substantial autonomy in supervising state-chartered member banks, conducting stress tests, and enforcing compliance. The Kansas City Fed supervises roughly 200 financial institutions in its district. That includes everything from large credit unions to community banks. The supervisory findings feed directly into the Fed's broader risk assessments, which influence policy decisions made in Washington. A bank examiner in Denver can flag a problem that eventually reaches the FOMC. The limitation here is that K Fed's influence is structurally diffuse. They cannot unilaterally set monetary policy. They cannot print money. They operate within the constraints set by the Board of Governors and the FOMC. When the economy is in crisis mode and Washington is making rapid-fire decisions, the regional banks become implementation engines rather than policy drivers. That is not a flaw in the design. It is how the system was built to prevent concentration of power. But it also means K Fed's impact is real yet indirect, felt through research, supervision, and committee voting rather than public announcements. If you want to track what K Fed is actually doing, start with their quarterly economic outlook publications and the Jackson Hole symposium transcripts. Those are publicly available and far more informative than most news coverage. The Fed's own research database has their working papers. The call reports from supervised institutions are accessible through the FFIEC. None of this is hidden. It just requires reading documents that are not written for a general audience.
Get the Full Details