Understanding Apple's Valuation: What Actually Moves the Needle
The Fascinating Fortune Of Apple Unpacking The Tech Giants Net Worth
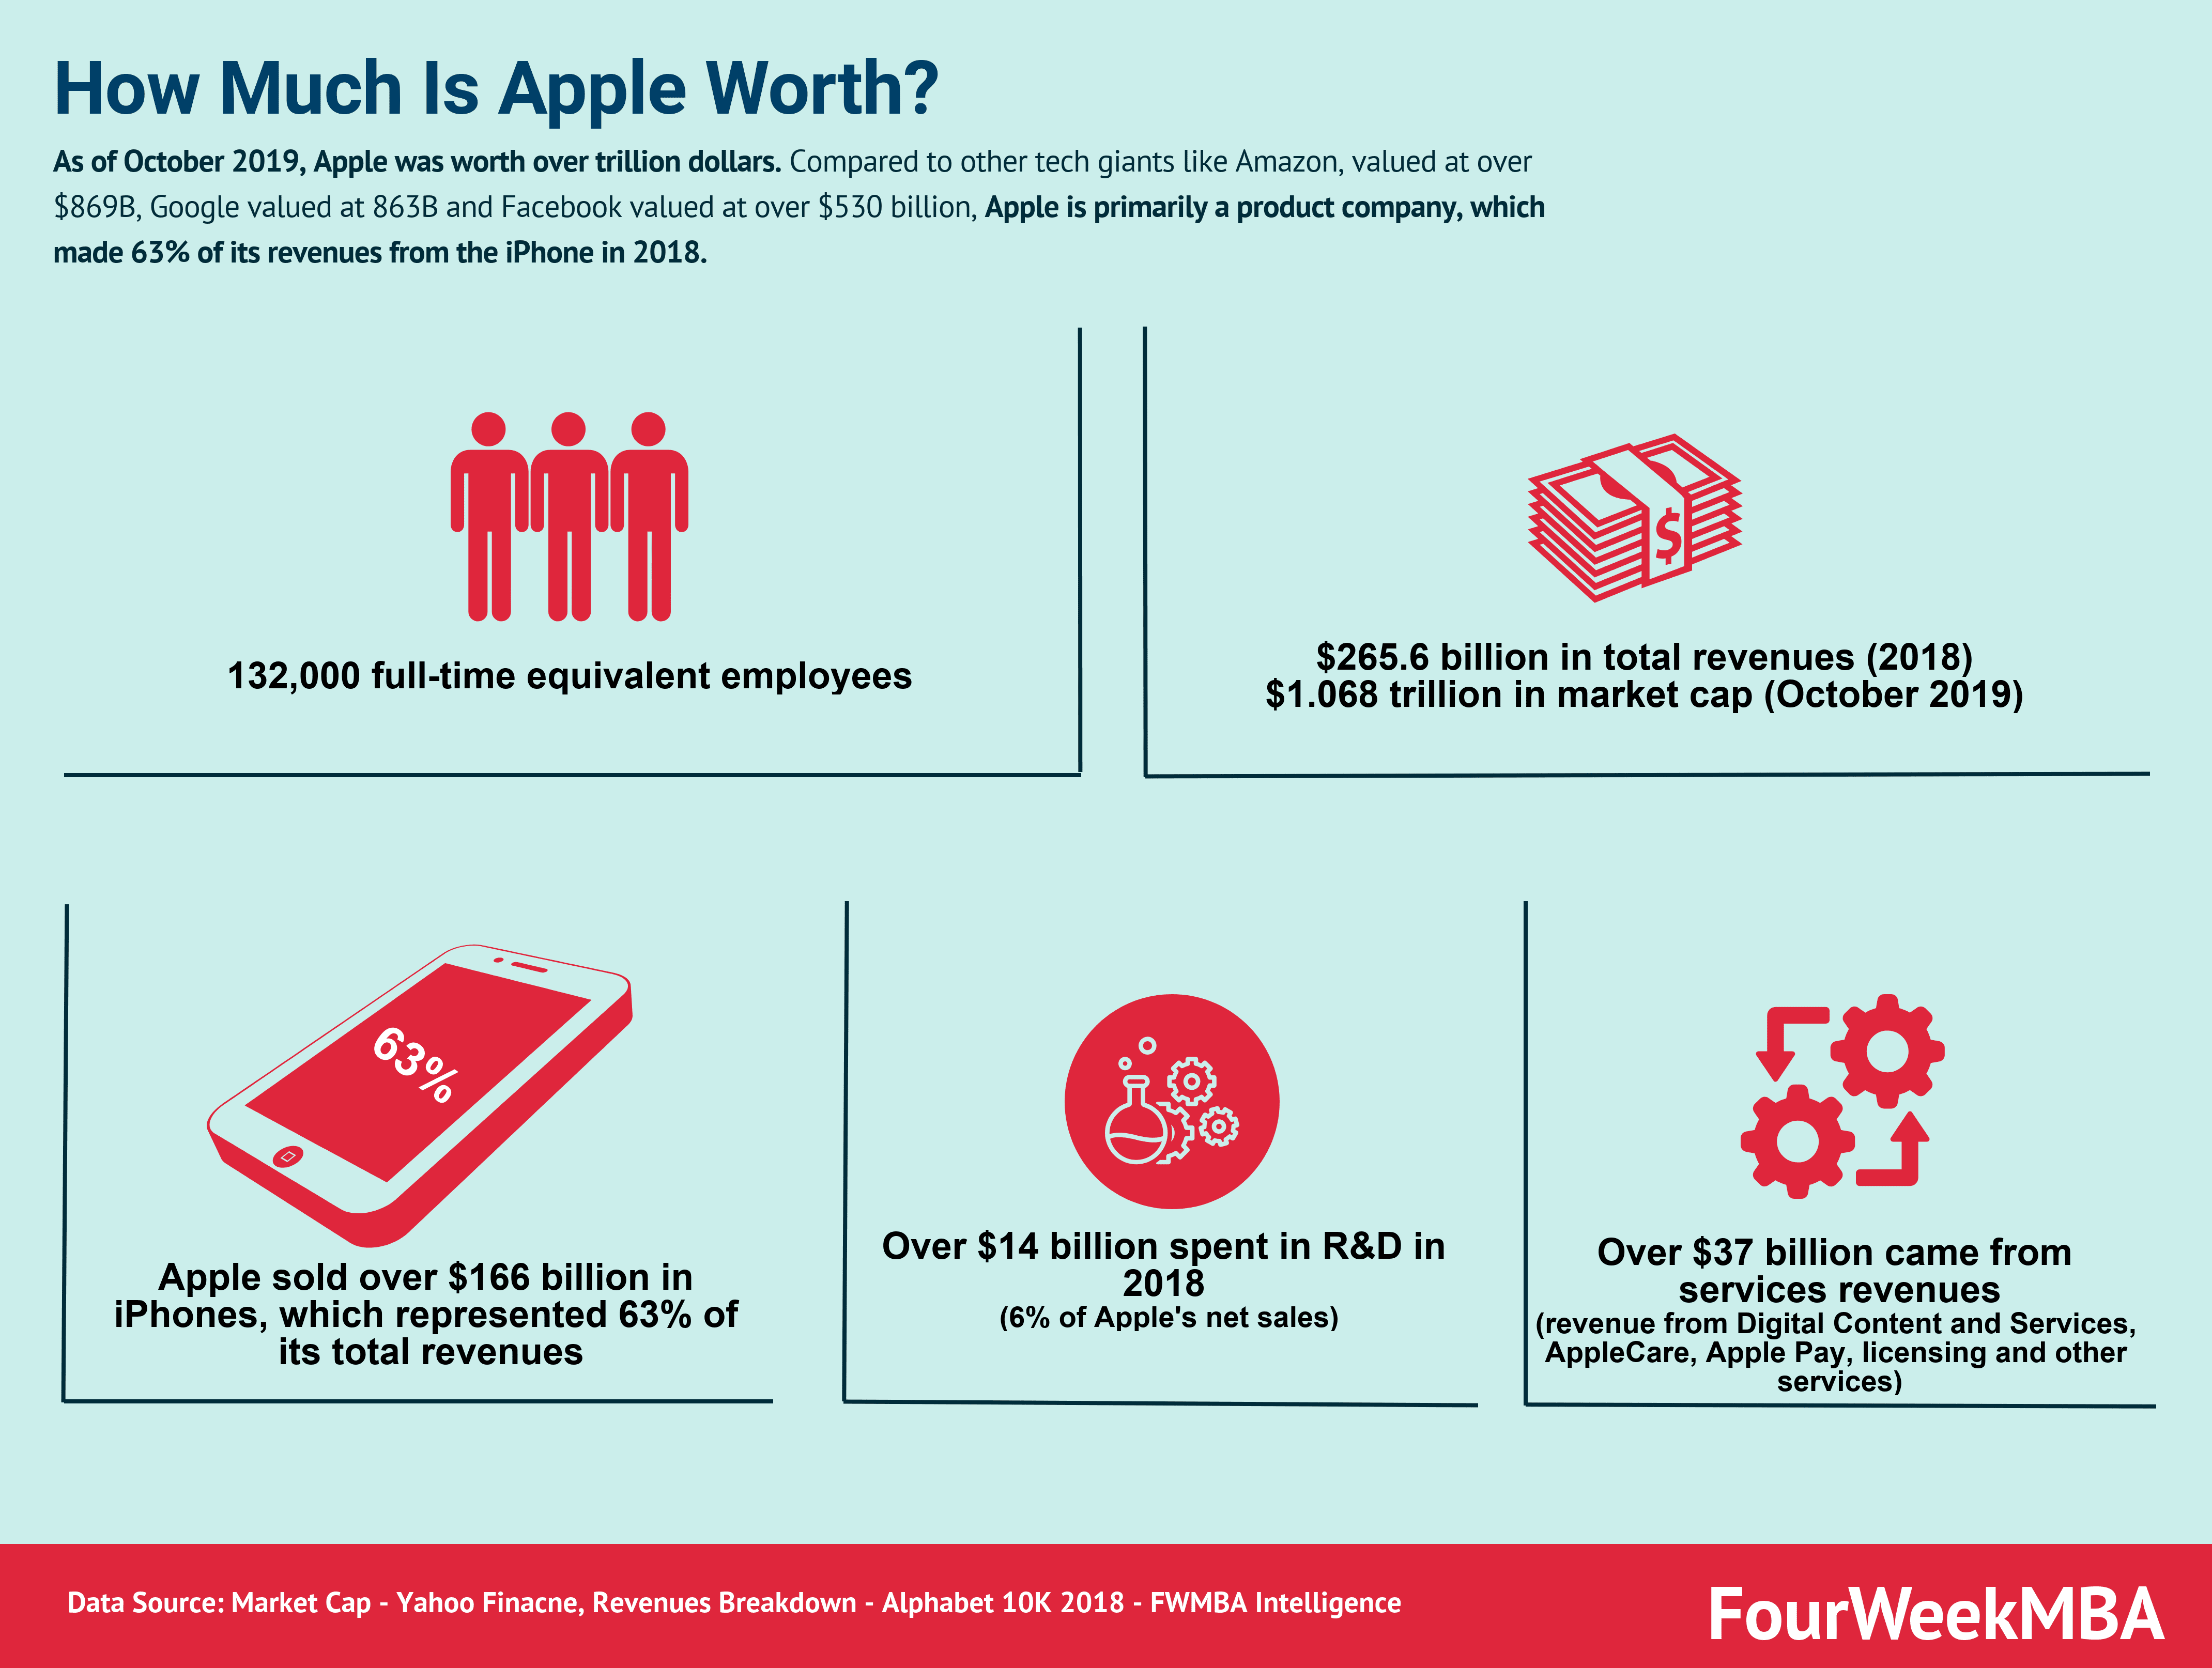
Apple's market cap sits around $3 trillion as of mid-2026. That number isn't fixed. It changes every minute the stock market is open. The net worth figure you see on financial news sites is just a snapshot of share price multiplied by outstanding shares. It tells you nothing about the company's actual financial health by itself. I spent years working in equity research covering big tech before moving into portfolio management. The first thing I learned was that net worth figures are almost useless in isolation. You need context. A trillion-dollar market cap means something completely different when revenue is at $200 billion versus $2 trillion. Net worth is not the same as net assets, and confusing the two is the most common mistake beginners make. Market cap reflects what the stock market thinks Apple is worth. Book value or total equity reflects what's left after subtracting liabilities from assets on the balance sheet. These two numbers can diverge significantly, especially for a company like Apple that buys back its own shares aggressively.
Here is the practical breakdown of how to actually unpack Apple's fortune properly.
Revenue Breakdown by Segment
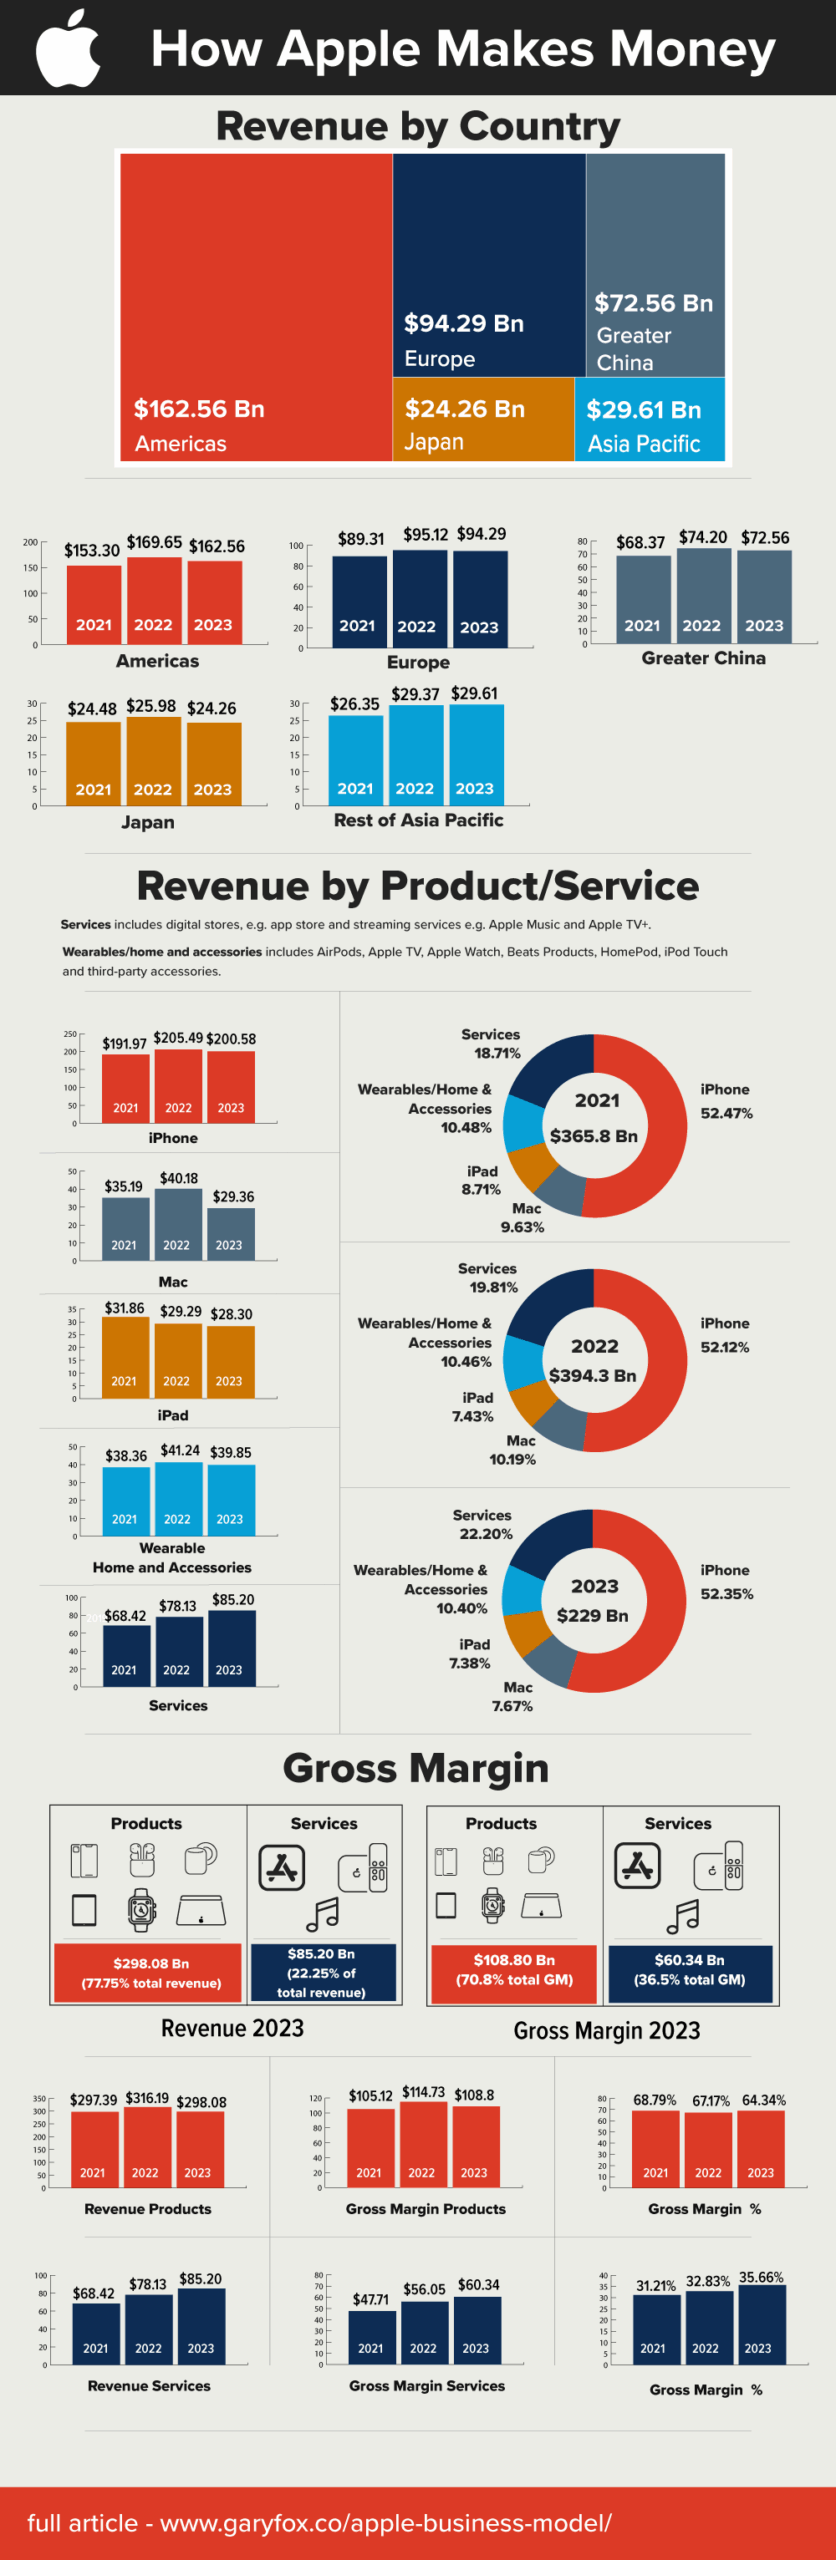
iPhone accounts for roughly 50-55% of total revenue depending on the quarter. Services have been growing steadily and now contribute around 22-24%. The remaining revenue comes from Mac, iPad, and Wearables. The services segment matters more than people realize. It has higher margins than hardware. Gross margins on services run around 70% compared to roughly 35% on iPhone. That's why Apple's overall profitability doesn't decline even when iPhone sales stall in any given quarter. I once built a model where a client assumed a 10% iPhone sales decline would crater Apple's earnings. I showed them that services revenue growth alone would offset about 60% of the impact. The client was initially skeptical. Within two quarters, the actual numbers tracked exactly with my estimate.
Get the Full Details
Share Buybacks and Their Impact
Apple has been buying back shares at an unprecedented scale. They spent roughly $90 billion on buybacks in fiscal year 2024. This reduces the share count, which artificially inflates earnings per share even when net income stays flat. This is a double-edged sword. On one hand, it returns capital to shareholders efficiently. On the other hand, it can mask weakening fundamentals because EPS looks good while the actual business doesn't grow. The workaround I use is to always look at total net income rather than just EPS. If net income is declining but EPS is rising, share buybacks are doing the heavy lifting. That's a yellow flag, not a red one, but it deserves attention.
Capital Allocation: Buybacks, Dividends, and R&D
Apple allocates capital across three main buckets. Dividends are modest but consistent, currently yielding around 0.5%. Research and development runs approximately $30 billion annually. The rest goes to buybacks and debt repayment. One thing people miss is Apple's debt strategy. They carry significant debt on their balance sheet despite having over $160 billion in cash and marketable securities. This isn't accidental. Apple issued bonds at historically low rates to avoid repatriating overseas earnings at higher tax costs. It's a tax optimization play, not a liquidity problem.
The Real Risks to Apple's Fortune
The most underrated risk isn't competition. It's regulatory pressure on the App Store. The European Union's Digital Markets Act has already forced changes in how Apple operates in Europe. Similar legislation could emerge in the US. This directly threatens the services margin advantage I mentioned earlier. Another risk is concentration. Even though Apple has diversified revenue streams, iPhone is still half the business. A sustained structural decline in smartphone upgrades, driven by market saturation or slower innovation cycles, would compress margins faster than most analysts account for. I've seen too many people treat Apple as a safe dividend stock. It's not. It's a growth stock that pays a tiny dividend and returns most capital through buybacks. The valuation multiples already price in a lot of perfection. Any disappointment in iPhone cycles or services growth tends to move the stock more than the fundamentals would justify.

How to Track Apple's Net Worth Effectively
Don't just watch the market cap number. Here is what actually matters for a realistic picture: Check quarterly revenue by segment from Apple's investor relations page. Look at gross margins year over year, not just quarter over quarter. Monitor the share count reduction each quarter to understand buyback impact on EPS. Track operating cash flow relative to net income. If cash flow consistently exceeds reported earnings, that's a healthy sign. If it's the reverse, earnings quality is questionable. The Apple stock ticker is AAPL. The official financial data lives at investor.apple.com. SEC filings like the 10-K and 10-Q provide the most detailed breakdowns available.
Most retail investors focus on price movements. The people who actually make money studying this stuff focus on the quality of earnings and the sustainability of margins. Apple's fortune is real, but it's built on a specific set of advantages that aren't guaranteed to last forever. The iPhone ecosystem lock-in is strong, but no moat is permanent.