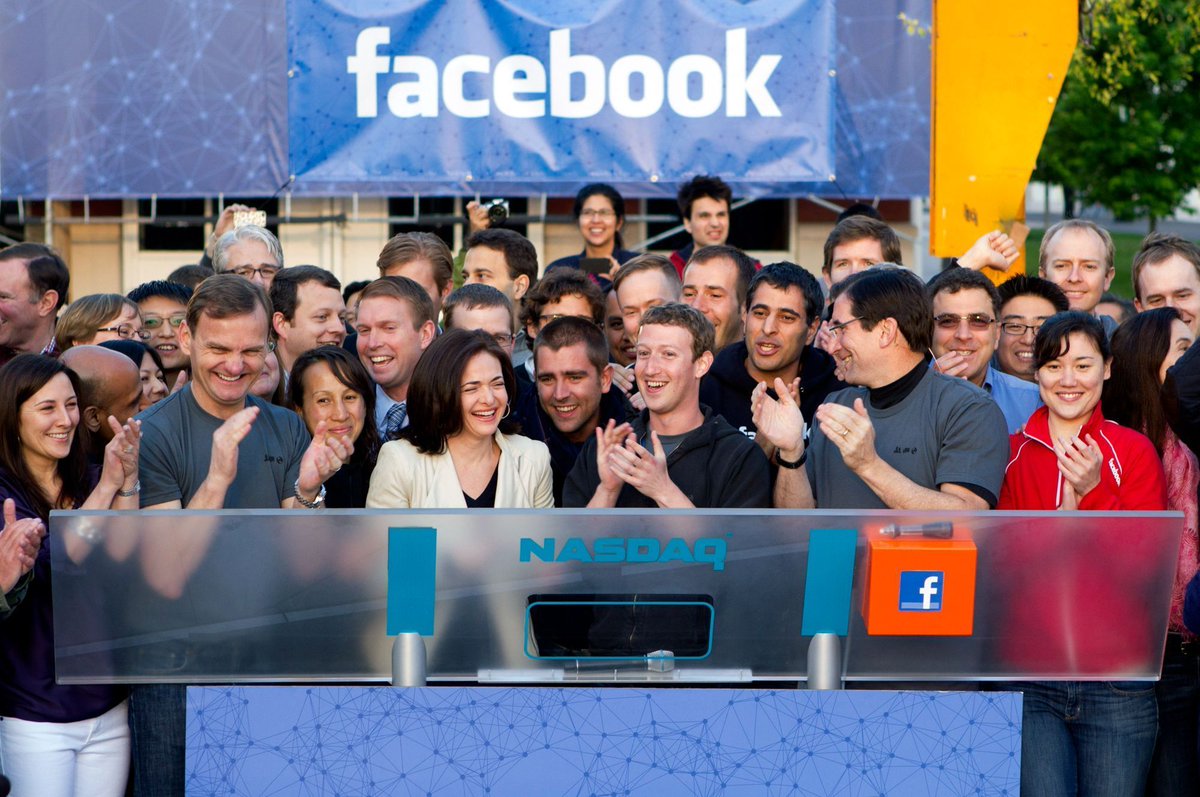
May 18th, 2012
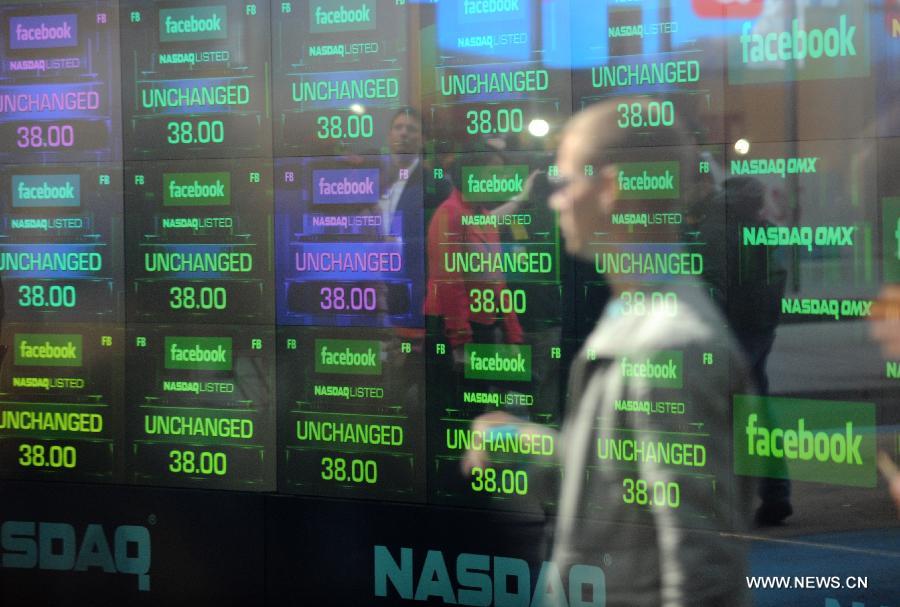
The opening bell rang at 9:30 AM and within minutes the trading engine essentially broke. That was the Facebook IPO. It wasn't the most dramatic public offering in history, but it was the one that made everyone realize how unprepared the financial infrastructure was for a generation of tech companies going public. I was watching the tape that day, not as an analyst or anyone important. I just had my Bloomberg terminal open and a bunch of chat windows. What I remember is the moment the stock opened at $38 and immediately started falling. It hit $34.57 on abnormally high volume before NASDAQ had to slow things down with trading pauses. By the time the market closed, it was down nearly 10 percent from the $38 offering price. Shares were still trading below IPO price months later.
The Facebook IPO Date That Defined A Era How Tech Went Public In 2012
Let me just lay out the facts before I get into what actually matters about that day. Facebook went public on May 18, 2012. The offering price was set at $38 per share, raising about $16 billion in what was then the largest tech IPO since Yahoo in 1996. Mark Zuckerberg sold roughly 44.3 million shares, and the company's valuation at the time was around $104 billion. That made it the most valuable technology company to go public at that point in history. But the number that actually stuck with people was the $38. It's now a cultural shorthand for any situation where something that seems invincible starts sliding immediately. People say "that's giving it a Zuckerberg" or reference the $38 opening price as proof that hype doesn't equal fundamentals.
Here's what most people miss about that IPO. It wasn't the stock price movement that was the real story. It was the technology failure underneath it.
Get the Full Details
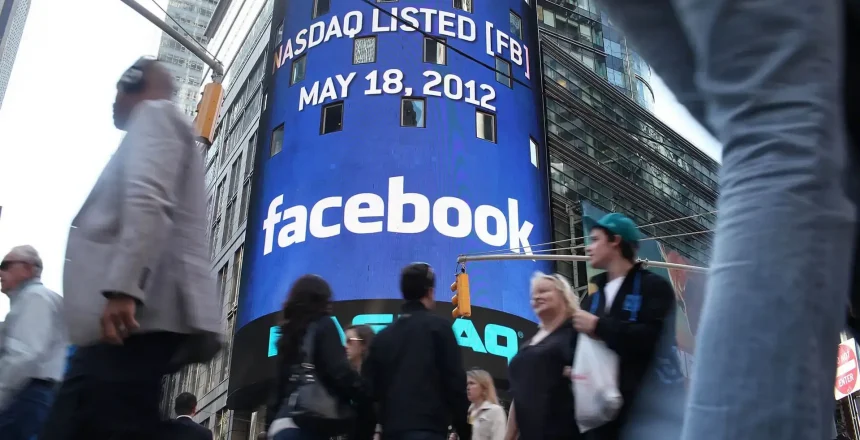
What Actually Happened That Day
NASDAQ's matching engine couldn't handle the order flow. I'm not being dramatic. The exchange literally lost track of somewhere between three and four million orders during the first hour of trading. The SEC later estimated that about 4 million orders were mismatched or lost, with some of them sitting unprocessed for hours or even days. This isn't a minor issue. When your matching engine drops orders on a IPO day, you have legitimate customers who placed valid buy orders at or above the opening price and simply never got filled. They called their brokers. The brokers called NASDAQ. Nobody could find the orders. NASDAQ had to publicly apologize. Their CEO Adena Friedman went on CNBC and essentially admitted they had a technology problem. The company faced scrutiny from the SEC and from Congress. Multiple class action lawsuits were filed against both Facebook and NASDAQ, which eventually settled for about $33 million to resolve claims from investors who said they were harmed by the order mismatches.
I remember one specific detail from that week that illustrates how bad it got. There were people on trading floors who had manually written down their client orders on paper because the electronic systems were moving so slowly or not updating correctly. Paper tickets. In 2012. That level of step-back happened because the digital infrastructure failed under pressure that nobody had fully stress-tested.
Why It Mattered Beyond The Stock Price
There's a reason this IPO is still talked about nearly fifteen years later, and it has nothing to do with Mark Zuckerberg's net worth. Before 2012, the assumption in Silicon Valley was that going public was something that happened to you eventually, like an rite of passage. You built the product, you got big, and then you called an investment bank and went through the process. The Facebook IPO changed how the industry thought about timing and preparedness. The secondary market had been pricing Facebook shares at valuations well above $38 for over a year before the IPO. Private market investors had been paying $25 to $30 per share in earlier funding rounds. When the IPO opened and immediately dropped, it created a repricing event that rippled through the entire private market. Companies that had been claiming billion-dollar valuations on venture funding suddenly had a public market reference point that looked generous by comparison.
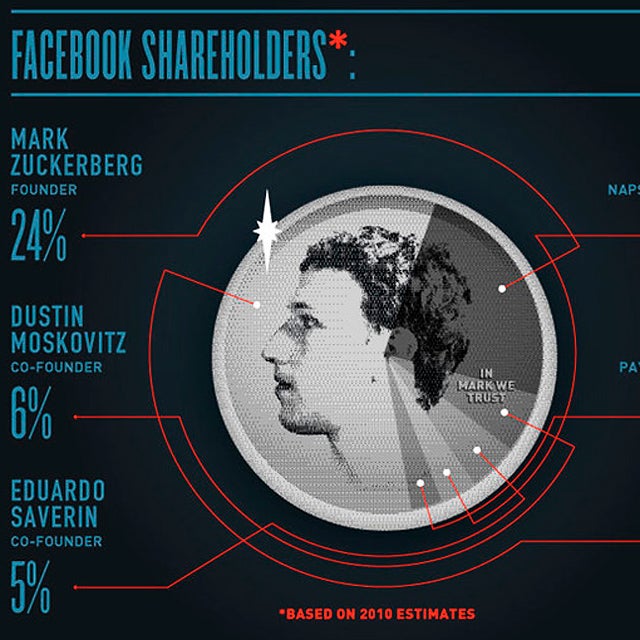
It also exposed the tension between retail and institutional investors that had been building for years. Facebook was marketed as a stock that everyday people should own. The social media platform itself was used to promote the IPO. But the trading mechanics and the post-IPO performance disadvantaged the very retail investors who were most enthusiastic about buying in. I've seen this pattern repeat. It's not unique to Facebook. Every major tech IPO since 2012 has had to navigate the same dynamic where public marketing creates retail FOMO while the actual trading mechanics and early insider selling advantages institutions.
The Aftermath And The Workaround
Here's a practical detail that comes up if you ever research this. If you're looking at historical trade data for Facebook stock around May 18-20, 2012, a lot of the records are messy. The order mismatches meant that some trades appeared on tapes that weren't real transactions. They were artifacts of NASDAQ's reconciliation process, not actual matched buys and sells. If I'm pulling historical data for something like a research project or a personal review of that period, I avoid using the raw NASDAQ trades tape for those dates and cross-reference with consolidated data sources. It saves you from analyzing phantom trades that inflated volume numbers artificially. This is something you won't find in most summaries of the IPO, but it matters if you're actually trying to understand what happened versus what the data says happened. The SEC's investigation into the matching engine failure took about eighteen months. Their final report, released in December 2013, concluded that NASDAQ's risk controls were inadequate and that the exchange should have halted trading much earlier once it became clear the system was struggling. NASDAQ implemented several changes afterward, including better order management systems and revised circuit breaker protocols for future large IPOs.
Facebook's stock took about two years to reclaim its IPO price. It didn't exceed $38 again until mid-2014. Investors who bought at the opening price and held through the rough patch were eventually rewarded, but that's a longer story and not particularly useful advice for anyone reading this.
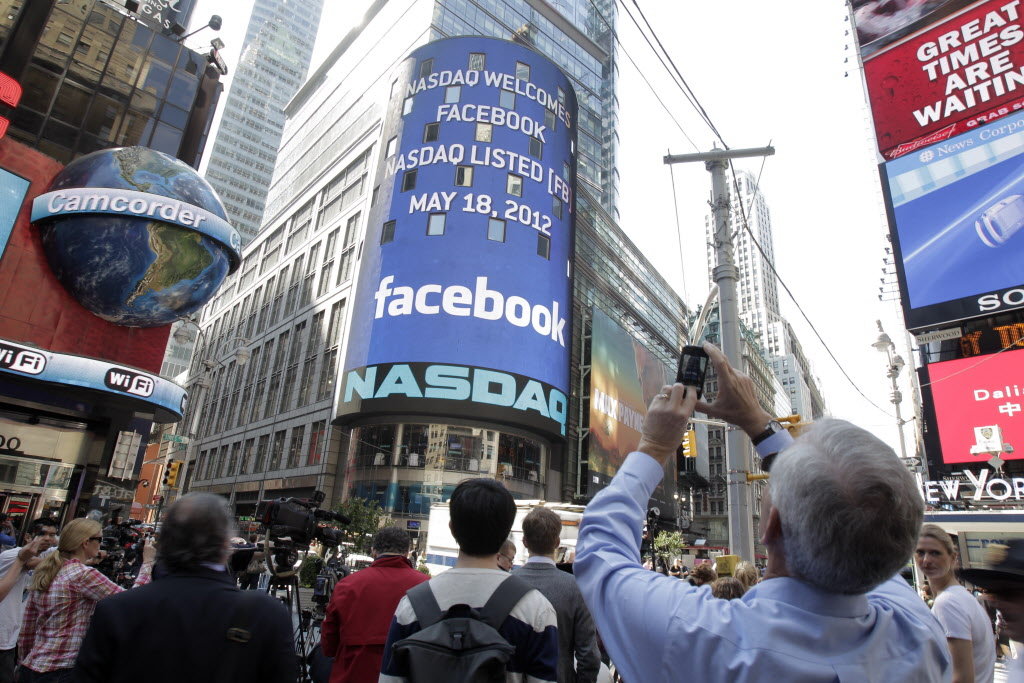
What This IPO Revealed About Tech Going Public
The years since 2012 have shown a clear pattern in how technology companies approach public offerings, and the Facebook IPO is the anchor point for all of it. First, companies became much more selective about timing. The gap between the last private funding round and the IPO widened significantly. Several major companies that would have gone public in 2013 or 2014 based on previous norms stayed private for another two to four years. Uber, Airbnb, and Pinterest all deferred their IPOs after observing the post-IPO pain that Facebook and LinkedIn experienced in 2011 and 2012. Second, the underwriting process changed. Investment banks became much more conservative about setting opening prices. The era of pricing at the top of the range to maximize proceeds faded somewhat after Facebook's experience. Banks started leaving more money on the table at the offering stage to reduce the risk of immediate post-IPO declines that damage both the issuer and their reputation.
Third, direct listing became a viable alternative for some companies. SPAC mergers emerged as another path that companies considered instead of traditional IPOs. Coinbase went public via direct listing in 2021, and the discussion around that process always referenced the 2012 IPO as a cautionary tale about market mechanics and investor protection. The thing nobody talks about enough is how the Facebook IPO changed the relationship between social media companies and their own users as investors. Facebook used its own platform to promote its IPO. That was unprecedented and controversial. regulators and market observers questioned whether a company should be using its product to generate retail demand for its own stock. It set a precedent that other companies have followed and that the SEC has yet to formally address in its rules.
The Numbers Nobody Remembers
The offering raised $16 billion. At the closing price on May 18th, the market cap was roughly $94 billion, down from the $104 billion implied by the $38 offering price. On May 20th, the stock hit an intraday low of around $29. It recovered somewhat through the summer and into 2013, but the memory of that opening day persisted. About 885 million shares changed hands on the first day of trading, which was roughly double the average daily volume for large-cap stocks at the time. The volume was partly driven by the order mismatches, since some orders were processed multiple times during reconciliation. The class action settlement of $33 million was split between claims against NASDAQ and claims against Facebook. The NASDAQ portion was larger because their failure to match orders was deemed the more significant cause of investor harm. Facebook's portion reflected the fact that their marketing and pricing created the initial conditions that led to the chaotic trading environment.
If you want to understand why this IPO date still comes up in conversations about technology and finance, it's because it was the moment the industry realized that going public is not just a financial event. It's a technology event, a regulatory event, and a cultural event all at once. The $38 price is a meme at this point. The actual lesson is about infrastructure and preparation, and that part of the story doesn't get nearly enough attention.

